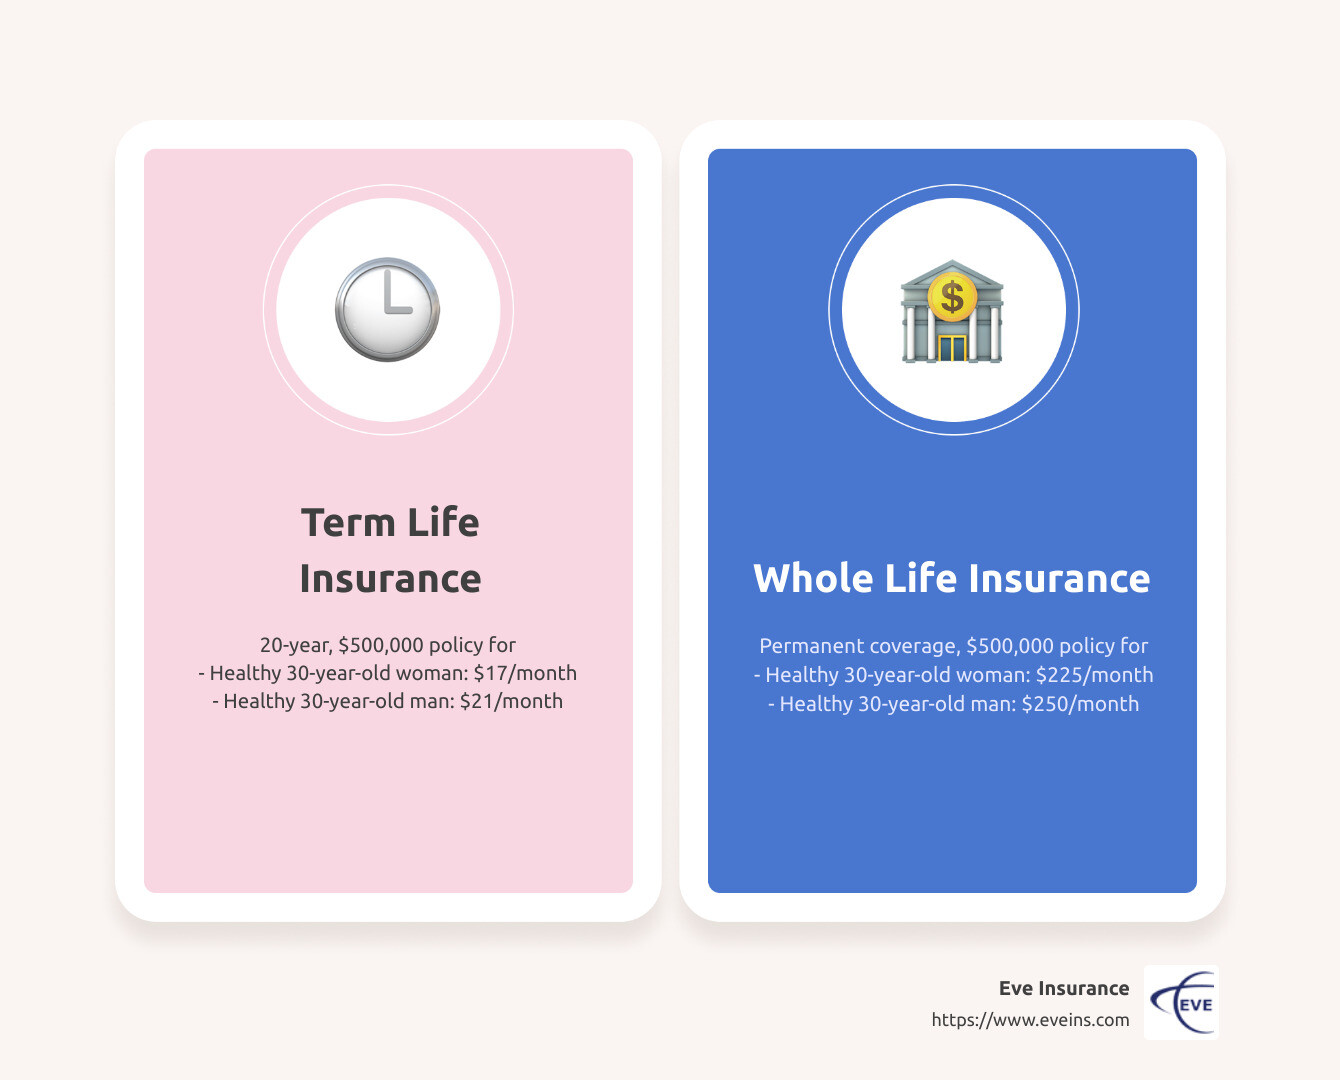
Voluntary life insurance allows employees to purchase supplemental life insurance coverage through their employer at negotiated group rates. Unlike basic employer-provided life insurance, voluntary life is funded entirely or largely by the employee through automatic monthly payroll deductions. Understanding voluntary life insurance monthly options helps workers tailor their financial protection, balance monthly budgets, and secure adequate coverage for dependent family members.
What Is Voluntary Life Insurance and How Do Monthly Options Work?
Voluntary life insurance—often called supplemental group life insurance—is an optional benefit offered by employers that enables workers to buy additional life insurance coverage beyond any basic policy provided by the company. Employers typically offer basic life insurance equal to one times an employee's annual salary at no cost to the employee. However, basic policies rarely cover the full financial obligations of a growing household. Voluntary life insurance fills this gap by allowing workers to elect higher benefit amounts funded directly from their paychecks.
The "monthly options" in voluntary life insurance refer to the choices employees have regarding payment frequency, coverage tiers, premium calculation models, and policy types (such as term or permanent life). Because employers negotiate group rates with insurance carriers, voluntary life insurance often provides lower monthly premiums than individual policies purchased directly on the open market, particularly for older workers or individuals with minor health conditions who qualify under guaranteed issue limits.
Monthly options are structured around payroll cycles. While an employee may view their election as a monthly dollar amount during benefit enrollment, employers convert this annual or monthly rate into corresponding payroll deductions based on how often the worker is paid (bi-weekly, semi-monthly, or monthly). The carrier calculates premiums per unit of coverage—typically expressed as a monthly dollar rate per $1,000 of benefit—making it straightforward for workers to scale coverage up or down to fit their personal budget.
Monthly Premium = (Total Coverage Amount / $1,000) x Monthly Rate per $1,000
Core Types of Voluntary Life Insurance Monthly Plans
When reviewing open enrollment materials, employees usually encounter distinct plan structures. Selecting the right option requires understanding how monthly premiums behave over time and whether the coverage generates long-term cash value.
1. Voluntary Term Life Insurance
Voluntary term life insurance is the most common option offered in workplace benefit packages. It provides coverage for a specific period—typically for as long as the employee remains with the employer—and pays a cash benefit to named beneficiaries if the insured passes away during the term.
- Monthly Premium Structure: Rates are calculated based on age brackets (age bands) and normally increase every five years (e.g., at ages 30, 35, 40, 45).
- Cost Efficiency: Offers the highest benefit amount for the lowest initial monthly cost.
- Cash Value: Accumulates no cash value or savings component. If the policy lapses or the employee leaves without electing portability, coverage ends without cash return.
2. Voluntary Permanent or Universal Life Insurance
Some employers offer voluntary permanent life insurance (often universal life or whole life). These policies combine a death benefit with an accumulating cash value component.
- Monthly Premium Structure: Premiums remain level and locked in at the age of purchase, meaning monthly payments do not automatically jump when entering new age brackets.
- Cash Value Accumulation: A portion of each monthly premium goes into a tax-deferred cash value account that grows over time.
- Portability: Permanent plans are designed for long-term ownership, allowing employees to take the exact policy and level monthly rate with them if they change jobs or retire.
3. Voluntary Dependent Life Insurance Options
Employees can often extend voluntary coverage to immediate family members through monthly payroll deductions:
- Voluntary Spouse Life: Coverage available in fixed increments (e.g., $10,000 increments up to 50% or 100% of the employee's elected coverage). Monthly rates are based on the spouse’s age and tobacco status.
- Voluntary Child Life: Coverage for dependent children (from live birth or 14 days up to age 26). Unlike spouse coverage, child life is usually sold as a flat monthly fee covering all eligible children in the household for a single benefit amount (e.g., $10 per month for $10,000 of coverage per child).

How Voluntary Life Insurance Monthly Premiums Are Calculated
Understanding the underlying pricing structure helps employees predict how their monthly deductions will evolve over their working years. Voluntary life rates are governed by several core factors.
| Key Monthly Rate Factors |
|---|
| 1. Age Band (Rates adjust every 5 years: 30-34, 35-39, 40-44, etc.) |
| 2. Tobacco Status (Tobacco users pay higher monthly rates per unit) |
| 3. Coverage Increment (Purchased in units of $10,000 or salary mult.) |
| 4. Underwriting Status (Guaranteed Issue vs. Evidence of Insurability) |
Age Banding Schedules
Group voluntary term life premiums are indexed to five-year age brackets (e.g., ages 20–24, 25–29, 30–34, up to 70+). When an employee transitions into a higher age band, their monthly rate per $1,000 increases automatically on the policy renewal date (usually January 1 of the plan year following their birthday).
For example, a non-tobacco employee might pay $0.05 per $1,000 per month in their 20s, which translates to $10.00 per month for $200,000 of coverage. By age 50, that same rate per $1,000 might increase to $0.23, raising the monthly cost for $200,000 to $46.00.
Guaranteed Issue (GI) Limits vs. Evidence of Insurability (EOI)
During initial employment or open enrollment, insurers set a Guaranteed Issue (GI) limit. This is the maximum amount of voluntary life insurance an employee can purchase without answering medical questions or taking a physical exam.
- At or Below GI Threshold: Employees can select coverage (e.g., up to $150,000 or 3x salary) with automatic approval. Monthly deductions begin immediately on the plan effective date.
- Above GI Threshold: If an employee requests coverage exceeding the GI threshold (e.g., selecting $300,000 when the GI limit is $150,000), they must complete an Evidence of Insurability (EOI) medical questionnaire.
- Payroll Timing: The premium for the guaranteed portion is deducted immediately, while the premium for the excess requested amount is not deducted until the insurer officially reviews and approves the EOI.
Tobacco and Gender Pricing Tiers
Depending on state regulations and corporate group contract structures, rates may be unbundled by tobacco usage and gender. Non-tobacco users receive significantly lower monthly premium rates compared to tobacco users. In unisex plan designs, male and female employees in the same age band share identical monthly rates.
Monthly Voluntary Life Insurance Options Compared
To help evaluate how voluntary options compare against standard basic coverage and private individual life insurance, the table below highlights key operational differences:
| Feature / Dimension | Basic Employer Life | Voluntary Group Term Life | Voluntary Universal / Whole Life | Private Individual Term Life |
|---|---|---|---|---|
| Funding Source | 100% Employer Paid | 100% Employee Paid | 100% Employee Paid | 100% Individual Paid |
| Monthly Cost | $0 (Free to employee) | Low group rate; increases with 5-year age bands | Moderate; locked level monthly rate | Locked level monthly premium for set term |
| Underwriting | None (Automatic) | Guaranteed Issue up to threshold; EOI required above | Guaranteed Issue limits or simplified health questions | Full medical underwriting (often exam required) |
| Cash Value | None | None | Yes (Builds tax-deferred cash value) | None |
| Portability | Typically ends at termination | Convertible or portable at higher direct billing rates | Highly portable at standard locked rates | Fully portable (independent of employer) |
| Payment Method | N/A | Automatic payroll deduction | Automatic payroll deduction or direct bill | Direct bank draft / Credit card |
| Spouse/Child Options | Rarely included | Optional monthly add-on riders available | Optional individual or rider policies | Separate policies required |
Payroll Deductions and Tax Implications of Monthly Options
Managing monthly options requires understanding how contributions flow through payroll systems and how the Internal Revenue Service (IRS) treats life insurance payments and death benefits.
Post-Tax vs. Pre-Tax Payroll Deductions
In almost all benefit plans, voluntary life insurance premiums are deducted from an employee's paycheck on a post-tax basis (after federal, state, and FICA taxes are calculated).
- Tax-Free Death Benefit: Paying voluntary life insurance premiums with post-tax dollars ensures that if the insured passes away, the entire death benefit is paid to beneficiaries completely income-tax-free.
- Pre-Tax Exception: If an employer allows pre-tax deductions for voluntary life insurance under a Cafeteria Plan (Section 125), any death benefit payout exceeding $50,000 could expose the beneficiary or employee to unexpected tax liabilities or imputed income tax under IRS rules. Therefore, benefits administrators almost universally mandate post-tax deductions for voluntary policies.
IRS Section 79 and Imputed Income
Under IRS Section 79, the cost of employer-provided group term life insurance up to $50,000 is tax-free. If an employer provides basic coverage over $50,000 at no cost to the worker, the value of the coverage over $50,000 (calculated using IRS Uniform Premium Table I rates) is treated as taxable imputed income.
However, because employees pay the full cost of voluntary life insurance out of their own post-tax income, voluntary coverage generally does not generate imputed income, provided the employee pays the full standard group rate.
Portability, Conversion, and Post-Employment Options
A major consideration when selecting monthly voluntary coverage is what happens to the policy if an employee leaves the company, resigns, or retires.
- Employment Termination Event
- Elect Portability
- Continues as Group Term
- Lower initial monthly cost
- Subject to group rate revisions
- Age-band rates continue
- Elect Conversion
- Converts to Individual Permanent
- Higher monthly rate (Whole Life)
- No medical exam required
- Permanent guaranteed rates
- Elect Portability
1. Portability Options
Portability allows departing employees to retain their group term life insurance coverage as a term policy.
- Payment Transition: Monthly premiums shift from automatic payroll deduction to direct monthly billing or automatic bank draft with the insurance carrier.
- Portability Rate Tables: The monthly premium rate often changes from the active employee group rate to a designated "portability rate table," which may be slightly higher. However, no medical exam is required.
- Age Limits: Portability typically has age ceilings (e.g., available until age 65 or 70).
2. Conversion Options
Conversion allows departing workers to convert their group term life insurance policy into an individual permanent whole life insurance policy without answering medical questions or undergoing health screening.
- Monthly Premium Impact: Conversion rates are based on the employee's attained age at the time of conversion and whole life rate structures. This results in significantly higher monthly premiums compared to voluntary term rates.
- Protection for Uninsurable Workers: Conversion is an important safety net for employees with severe health conditions who leave their jobs and cannot qualify for new individual policies on the open market.
Step-by-Step Guide to Choosing the Right Monthly Coverage Amount
Selecting the optimal voluntary life insurance coverage requires balancing long-term protection needs against current monthly household cash flow.
- Step 1: Calculate Total Financial Needs (DIME Method)
- Debt & Final Expenses (Credit cards, auto loans, funeral costs)
- Income Replacement (Annual salary x years needed)
- Mortgage Balance (Remaining home loan payoff)
- Education Costs (College funds for dependents)
- Step 2: Subtract Existing Protections
- Employer-Paid Basic Life Insurance Coverage
- Existing Private Policies & Savings
- Step 3: Determine Required Voluntary Coverage Gap
- Step 4: Calculate Monthly Premium & Check Guaranteed Issue (GI) Limits
- Step 5: Finalize Payroll Deduction Election During Open Enrollment
Step 1: Apply the DIME Formula
Financial planners frequently use the DIME framework to estimate baseline life insurance needs:
- D (Debt): Sum all non-mortgage debts (credit cards, personal loans, student loans, auto loans) plus estimated funeral costs ($10,000–$15,000).
- I (Income Replacement): Multiply annual salary by the number of years family members need financial support (e.g., $75,000 x 7 years = $525,000).
- M (Mortgage): Include the exact principal balance required to pay off the primary home mortgage.
- E (Education): Estimate future tuition and living expenses for dependent children (e.g., $50,000 to $100,000 per child).
Step 2: Subtract Basic Coverage and Existing Assets
Subtract any existing employer-paid basic life insurance (e.g., $50,000 or 1x salary) and personal savings from your total DIME figure. The remaining number represents your insurance gap.
Step 3: Match Coverage to Budget Tiers
Look at your employer's voluntary life insurance monthly cost table. Calculate the exact monthly payroll deduction for different coverage tiers (e.g., $100,000 vs. $250,000 vs. $500,000). Ensure the chosen deduction aligns comfortably with your monthly net pay without straining daily living expenses.
Step 4: Maximize Guaranteed Issue Thresholds
If you have underlying health issues, elect up to the maximum Guaranteed Issue (GI) threshold during your initial enrollment period. This guarantees coverage at standard group monthly rates without risk of medical denial. If you require coverage above the GI limit, be prepared to submit an EOI form.
Frequently Asked Questions
Can I adjust my voluntary life insurance monthly amount outside open enrollment?
Generally, no. Voluntary life insurance elections are governed by cafeteria plan guidelines and carrier contracts. You can typically change your coverage amount only during annual open enrollment or within 31 days of a qualifying life event (QLE), such as marriage, divorce, birth of a child, adoption, or a spouse losing their job.
What happens to my monthly voluntary life insurance if I am on unpaid medical leave?
If you go on approved unpaid leave (such as Family and Medical Leave Act / FMLA leave), your employer may allow you to continue coverage by submitting direct monthly checks to human resources or by setting up an automated direct payment schedule. Alternatively, some plans permit cumulative arrears deductions from your paycheck once you return to active work.
Are voluntary life insurance premiums cheaper through an employer than buying an individual private policy?
It depends on your age and health status. For younger workers (under age 40) in excellent health, private individual term life insurance often offers locked, level monthly rates over 20 or 30 years that are cheaper long-term than workplace group rates that increase every five years. However, for older workers, individuals with pre-existing health conditions, or those seeking coverage without a medical exam, group voluntary life rates under Guaranteed Issue limits are usually more affordable.
Is the cash death benefit from voluntary life insurance taxable to my beneficiaries?
In almost all cases, life insurance death benefit payouts received by beneficiaries are excluded from federal income tax under Internal Revenue Code Section 101(a). However, if the benefit is paid in installments that accrue interest, the interest portion earned after the insured’s death is subject to standard income tax reporting.
How does smoking or tobacco use affect my monthly voluntary life insurance cost?
Insurance carriers establish separate rate schedules for tobacco users and non-tobacco users. Employees who use cigarettes, e-cigarettes, cigars, or chewing tobacco typically pay monthly rates per $1,000 of coverage that are two to three times higher than rates for non-tobacco users within the same age band.
Summary and Practical Next Actions
Voluntary life insurance monthly options provide a practical, cost-effective mechanism for employees to secure supplemental financial protection for their families. By utilizing group purchasing power and automated payroll deductions, workers can customize their coverage amounts while maintaining control over their monthly household cash flow.
When evaluating your workplace options during open enrollment or a qualifying life event:
- Review your basic employer coverage to understand your baseline protection.
- Calculate your financial gap using the DIME formula (Debt, Income, Mortgage, Education).
- Check your plan’s Guaranteed Issue limit to secure instant, medical-exam-free approval.
- Compare group voluntary rates against private individual quotes if you are young and in good health, ensuring you secure the most cost-effective long-term protection.
Disclaimer: This article is provided for educational and informational purposes only and does not constitute financial, legal, or professional insurance advice. Specific policy rules, group rates, rate schedules, and benefit options vary by employer, jurisdiction, and insurance carrier. Consult your corporate human resources department or a licensed financial professional for tailored guidance.
Image Gallery
Select an image to open it in a new tab.


Celine Dubois
Contemporary Living and Global Arts Columnist
