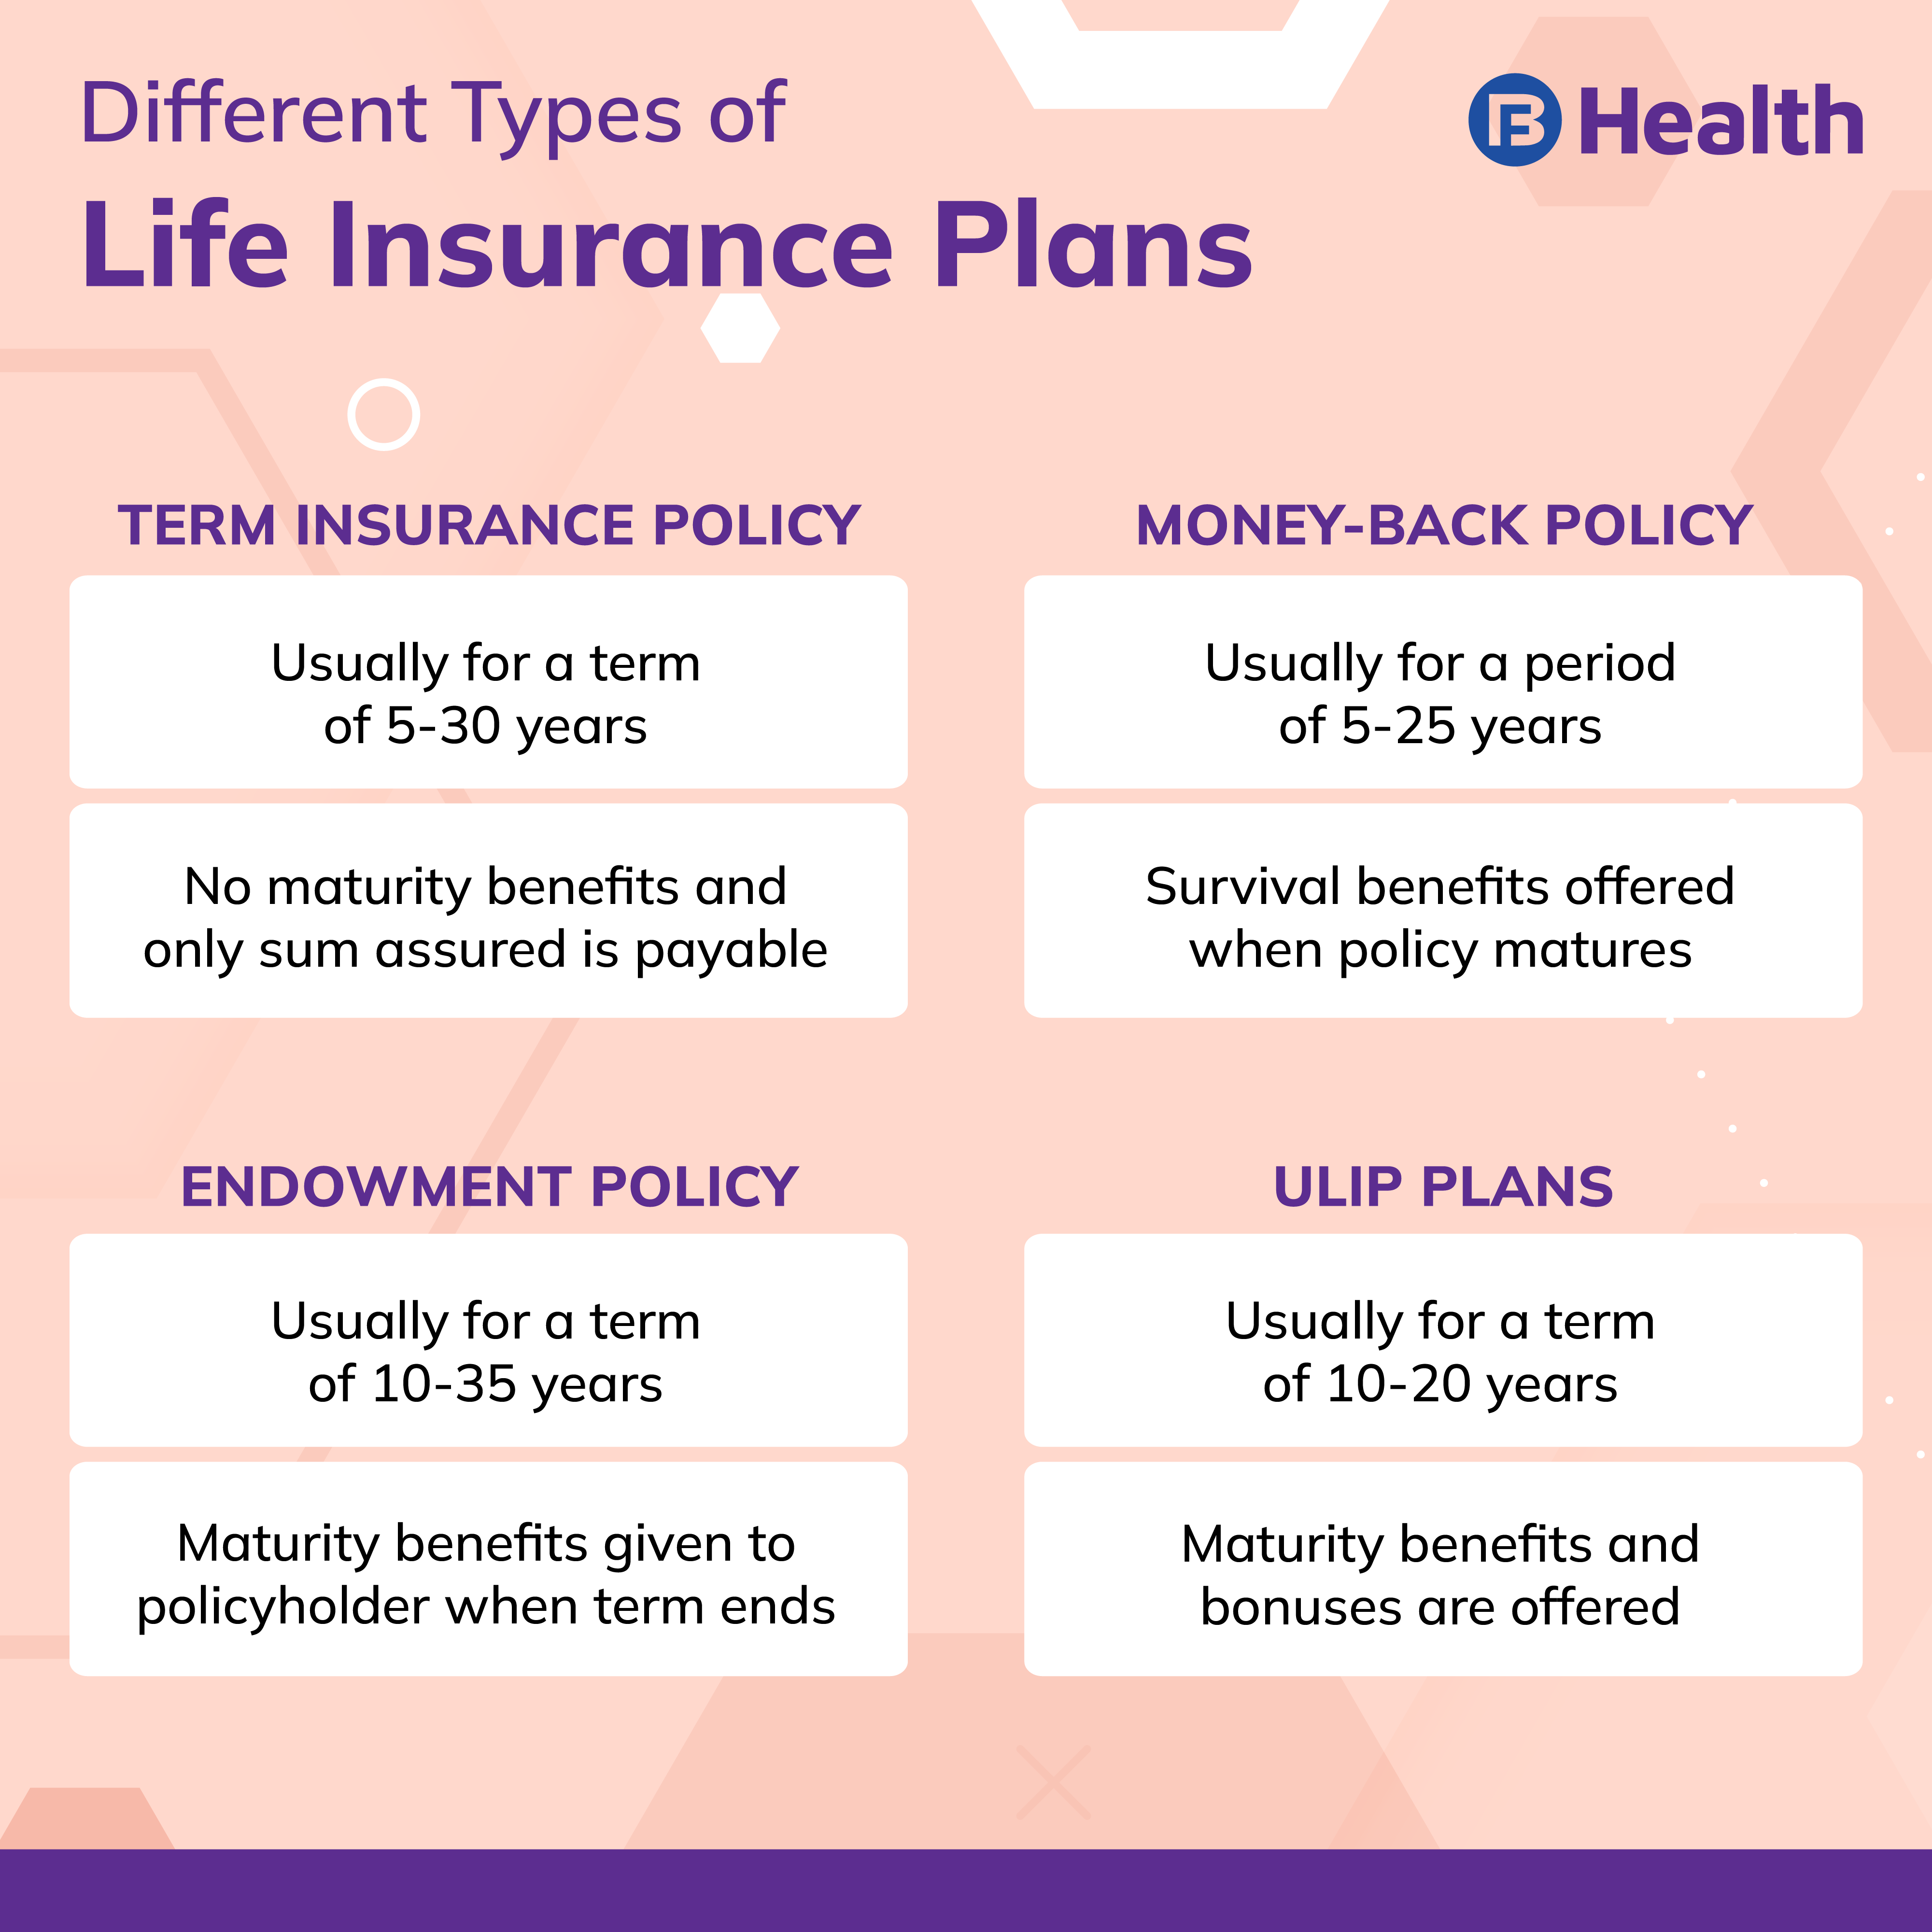
Donating a life insurance policy is often less effective than other charitable strategies because the tax benefits are frequently capped at the policy's cost basis rather than its death benefit or fair market value. Additionally, the administrative costs, appraisal requirements, and loss of financial flexibility usually outweigh the perceived advantages for both the donor and the recipient.
While the concept of "leveraged giving"—turning a small premium into a large future gift—is romantically appealing to many philanthropists, the reality of the United States tax code and the operational needs of non-profit organizations in 2026 paint a different picture. For most individuals, the process of transferring ownership of a life insurance policy to a charity creates a series of technical and financial hurdles that diminish the ultimate impact of the gift.
The Disconnect Between Face Value and Tax Deductibility
The primary reason donating a life insurance policy is rarely worthwhile is the significant gap between what the donor perceives as the "value" of the gift and what the IRS allows as a deduction. Most donors believe that if they donate a policy with a $500,000 death benefit, they should receive a substantial tax break. However, tax law dictates a much more restrictive valuation process.
The Cost Basis Limitation
Under IRS guidelines, the charitable deduction for a donated life insurance policy is generally limited to the lesser of two values: the policy's fair market value (FMV) or the donor’s cost basis. The cost basis is essentially the total amount of premiums paid into the policy, minus any dividends received or loans taken against the policy.
For many permanent policies (such as Whole Life or Universal Life), the fair market value—often calculated as the interpolated terminal reserve plus any unearned premiums—might be higher than the premiums paid if the policy has been held for decades. However, because the deduction is capped at the cost basis, the donor cannot "capture" the growth of the policy’s internal value for tax purposes. This makes life insurance one of the most tax-inefficient assets to donate compared to appreciated securities or real estate, where donors can often deduct the full current market value without paying capital gains tax.
The Zero-Value Problem for Term Insurance
If you are considering donating a term life insurance policy, the financial case becomes even weaker. Term insurance has no cash accumulation component. Because it only provides a benefit if the insured dies within a specific window, its "fair market value" for a healthy individual is essentially zero in the eyes of the IRS. Consequently, a donor attempting to transfer a term policy would receive no immediate income tax deduction, despite the potential future value to the charity.
The Burden of Qualified Appraisals
In 2026, the IRS remains incredibly stringent regarding the valuation of non-cash charitable contributions. If a donor claims a deduction for a life insurance policy that exceeds $5,000, they are required to obtain a qualified appraisal from a qualified appraiser.
This creates an immediate "out-of-pocket" friction point. A qualified appraisal for a life insurance policy is not a simple letter from the insurance agent or the carrier. It requires an actuary or a specialized valuation firm to calculate the fair market value based on the insured's health, current interest rates, and the policy's specific internal mechanics.
The costs for these appraisals can range from $1,500 to $5,000. For a policy with a modest cash value, the cost of the appraisal can consume a significant portion of the tax savings generated by the deduction. Furthermore, if the IRS deems the appraisal insufficient or the valuation inflated, the donor faces the risk of penalties and the total disqualification of the deduction.

The Ongoing Cost of Maintenance
One of the most overlooked reasons why this strategy is rarely worthwhile is the ongoing financial obligation. Unless a policy is "fully paid up," someone must continue to pay the premiums to keep the coverage in force.
Donor-Paid Premiums
Most charities do not have the liquid budget to pay premiums on donated policies. Therefore, the donor usually agrees to continue making annual payments. Technically, the donor makes a cash gift to the charity, and the charity then pays the insurance company. While these subsequent cash gifts are tax-deductible, the donor is essentially committing to a long-term liability for an asset they no longer own. If the donor’s financial situation changes in 2027 or 2028 and they can no longer afford the premiums, the policy may lapse, rendering the previous years of payments and the initial donation entirely worthless.
The Charity’s Perspective: "Illiquid Risk"
From the charity's side, a donated life insurance policy is a "long-term" and "uncertain" asset. Charities generally prefer cash today over a promise of money at an unknown date in the future. Managing a portfolio of donated life insurance policies requires administrative oversight, tracking the health of donors, and ensuring premiums are paid on time. Because of this, many smaller non-profits actually discourage the donation of policies, preferring to receive the cash that would have been spent on premiums instead.
Loss of Control and Financial Flexibility
When you donate a life insurance policy, you must transfer all incidents of ownership to the charity to qualify for a tax deduction. This is an irrevocable decision. Once the transfer is complete, you lose the right to:
- Borrow against the cash value for personal emergencies.
- Change the beneficiary back to a family member if your personal circumstances change (e.g., a child’s medical crisis or an unexpected divorce).
- Surrender the policy for its cash value to fund your own retirement.
In an era of economic volatility, giving up control of a liquid or semi-liquid asset is a high-risk move. Many financial advisors in 2026 suggest that clients maintain control of their assets as long as possible, using "testamentary" giving (giving upon death) rather than "inter vivos" giving (giving during life) for insurance products.
Comparison of Charitable Giving Methods
To understand why life insurance is often the least favorable option, consider how it compares to other common forms of giving.
| Giving Method | Immediate Tax Deduction | Valuation Basis | Complexity/Cost | Impact on Charity |
|---|---|---|---|---|
| Cash Donation | Full amount | Face value | Very Low | Immediate |
| Appreciated Stocks | Full market value | Current FMV | Low | Immediate |
| Life Insurance (Ownership Transfer) | Limited to Cost Basis | Lower of Basis or FMV | High (Appraisal needed) | Delayed (at death) |
| Life Insurance (Beneficiary Only) | None | N/A | Very Low | Delayed (at death) |
| Life Settlement & Cash Gift | Full amount of cash | Face value of cash | Medium | Immediate |
Better Alternatives: Why They Are More Worthwhile
If the goal is to support a charity using the vehicle of life insurance, there are two primary methods that are almost always superior to transferring ownership of the policy.
1. Naming the Charity as a Beneficiary
The simplest and most effective way to use life insurance for charity is to remain the owner of the policy but name the non-profit as a primary or contingent beneficiary.
Advantages:
- Flexibility: You can change the beneficiary at any time if your family's needs change.
- No Appraisal Costs: Since you aren't claiming an immediate income tax deduction, you don't need a qualified appraisal.
- Estate Tax Benefits: While you don't get an income tax deduction now, the death benefit is removed from your taxable estate through the charitable estate tax deduction. For high-net-worth individuals, this can be a massive benefit.
- Control: You retain access to the cash value during your lifetime.
2. The Life Settlement Strategy
In 2026, the life settlement market has become highly transparent and regulated. If you have a permanent life insurance policy that you no longer need—perhaps your children are grown and your mortgage is paid off—selling the policy to a third party for cash (a life settlement) often yields a much higher return than surrendering it to the insurance company or donating the policy directly to a charity.
Once the policy is sold, the donor receives a lump sum of cash. They can then donate that cash to the charity. This results in:
- An immediate, high-impact gift for the charity.
- A clean, easy-to-calculate tax deduction for the donor (based on the cash amount).
- The elimination of the need for the charity to track the donor or pay future premiums.
Common Mistakes When Attempting to Donate
Despite the downsides, some still pursue this path. Those who do often fall into traps that can lead to IRS audits or financial loss.
- Relying on "Replacement Cost": Donors often try to use the "replacement cost" (the premium a similar person would pay for the same policy today) as the deduction amount. The IRS specifically prohibits this for most life insurance donations, insisting on the Interpolated Terminal Reserve.
- Ignoring the $5,000 Threshold: Many donors fail to realize that even if the cash value is $5,001, the lack of a qualified appraisal (Form 8283) will result in the total rejection of the deduction.
- Donating Policies with Loans: If you donate a policy that has an outstanding loan, the IRS may treat the loan forgiveness as "bargain sale" income. This means the donor could actually owe taxes upon making the gift, creating a "taxable event" out of a charitable act.
Frequently Asked Questions
Can I deduct the premiums I pay on a policy owned by a charity?
Yes, if the charity is the absolute owner and beneficiary of the policy, any premiums you pay on their behalf are considered charitable contributions. However, you must keep meticulous records, and the charity must provide you with a written acknowledgment of the gift each year.
What is "Interpolated Terminal Reserve" and why does it matter?
Interpolated Terminal Reserve (ITR) is a technical insurance term for the value the insurance company holds on its books for a policy. It is often slightly higher than the cash surrender value but lower than the total premiums paid. The IRS uses this, plus unearned premiums, to determine the Fair Market Value of a policy that is not "paid up." It requires an actuary to calculate, which is why appraisals are expensive.
Why wouldn't a charity want my life insurance policy?
Charities prioritize liquidity. A life insurance policy is a "future" asset that requires management. If the charity has to pay premiums to keep the policy active, it is effectively gambling that the death benefit will be higher than the total premiums paid plus the "opportunity cost" of not having that cash to spend on their mission today. Many non-profits find this risk unappealing.
Is it ever worth donating a term life policy?
Almost never. Since term policies have no cash value, there is no immediate tax deduction. Furthermore, if you stop paying premiums, the policy vanishes. The only scenario where it might make sense is if the insured is terminally ill and the charity is willing to take over the final few premium payments to collect the death benefit shortly thereafter—but even then, the legal and ethical complexities are significant.
What is the "Three-Year Rule" for estate taxes?
If you transfer ownership of a life insurance policy to a charity (or anyone else) and die within three years of the transfer, the IRS may pull the value of that policy back into your estate for tax calculation purposes. While the charitable deduction usually offsets the estate tax, this adds a layer of legal complexity that many prefer to avoid.
Final Recommendation: A More Practical Path
Unless you have a very specific, fully paid-up permanent policy with a cost basis that significantly exceeds its cash value, donating a life insurance policy is rarely worthwhile in 2026.
For the vast majority of donors, the most efficient way to give is to designate the charity as the beneficiary of the policy while retaining ownership. This provides the donor with total financial security and flexibility, avoids the high costs of actuarial appraisals, and ensures that the charity eventually receives the full death benefit without the administrative burden of policy ownership. Alternatively, if you seek an immediate tax benefit, consider selling the policy through a life settlement and donating the resulting cash. This maximizes the value for the charity and simplifies your tax filing, ensuring your philanthropic legacy is defined by its impact rather than its complexity.
Image Gallery
Select an image to open it in a new tab.



Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
