Understanding the Life and Health Insurance Exam Example: A Comprehensive Guide

Mastering the life and health insurance licensing exam requires a strategic approach that blends conceptual knowledge of industry regulations with the practical application of policy types and underwriting standards. Candidates must navigate complex legal frameworks, product features, and ethical requirements, moving beyond rote memorization to achieve a passing score on the state-administered certification exam.
The Landscape of the Life and Health Licensing Process
In the United States, the life and health insurance examination is not a standardized national test; rather, it is a state-specific requirement administered by various testing vendors, such as Pearson VUE or Prometric, acting on behalf of state insurance departments. Because insurance is regulated at the state level under the McCarran-Ferguson Act, the "example" or content of the exam reflects the specific statutes, administrative codes, and consumer protection laws of the jurisdiction where you intend to practice.
When reviewing exam materials or practice questions, you are essentially engaging with a dual-layered curriculum. The first layer consists of national general knowledge—concepts that remain constant across all states, such as the basic principles of risk pooling, the legal definition of a contract, and the distinction between whole life and term insurance. The second layer is state-specific law, which covers how those national principles are codified locally, including licensing procedures, rebating, twisting, and the specific duties of a producer or agent.
Core Components of the Exam Curriculum
To succeed, you must understand how the exam is structured. Most state exams are broken down into two primary sections: the Life Insurance section and the Health Insurance section. Some states allow you to take these separately, while others require a combined exam.
1. General Insurance Principles
This foundational section tests your understanding of the risk management process. You will be expected to define "risk," "hazard," and "peril," and distinguish between pure and speculative risk. The exam will challenge you to identify the essential elements of a legal contract: offer and acceptance, consideration, competent parties, and legal purpose. Understanding these concepts is vital because they form the "rules of the game" for every policy you will eventually sell.
2. Life Insurance Products
The exam will present examples requiring you to distinguish between types of policies. You must master the differences between:
- Term Life: Temporary protection with no cash value.
- Whole Life: Permanent protection with a savings component and fixed premiums.
- Universal and Variable Life: Flexible-premium policies that may involve equity market participation, which introduces the concept of securities regulation (often requiring a FINRA license in addition to the state insurance license).
3. Health Insurance Products
This portion of the exam focuses on medical expense insurance, disability income protection, and long-term care. You will encounter scenarios involving "deductibles," "coinsurance," "out-of-pocket maximums," and "co-payments." A critical area here is the coordination of benefits and the specific provisions regarding group versus individual health plans.
4. Federal and State Regulations
This is often the most challenging part of the exam. You will be tested on the National Association of Insurance Commissioners (NAIC) model acts, which many states adopt as law. Topics include:
- Market Conduct: Preventing unfair trade practices like misrepresentation, defamation, and intimidation.
- Licensing Maintenance: Understanding continuing education requirements, change of address notifications, and appointment procedures.
- Ethics: The fiduciary duty of the producer to the applicant and the insurer.
Analyzing Exam Examples: Moving from Theory to Application
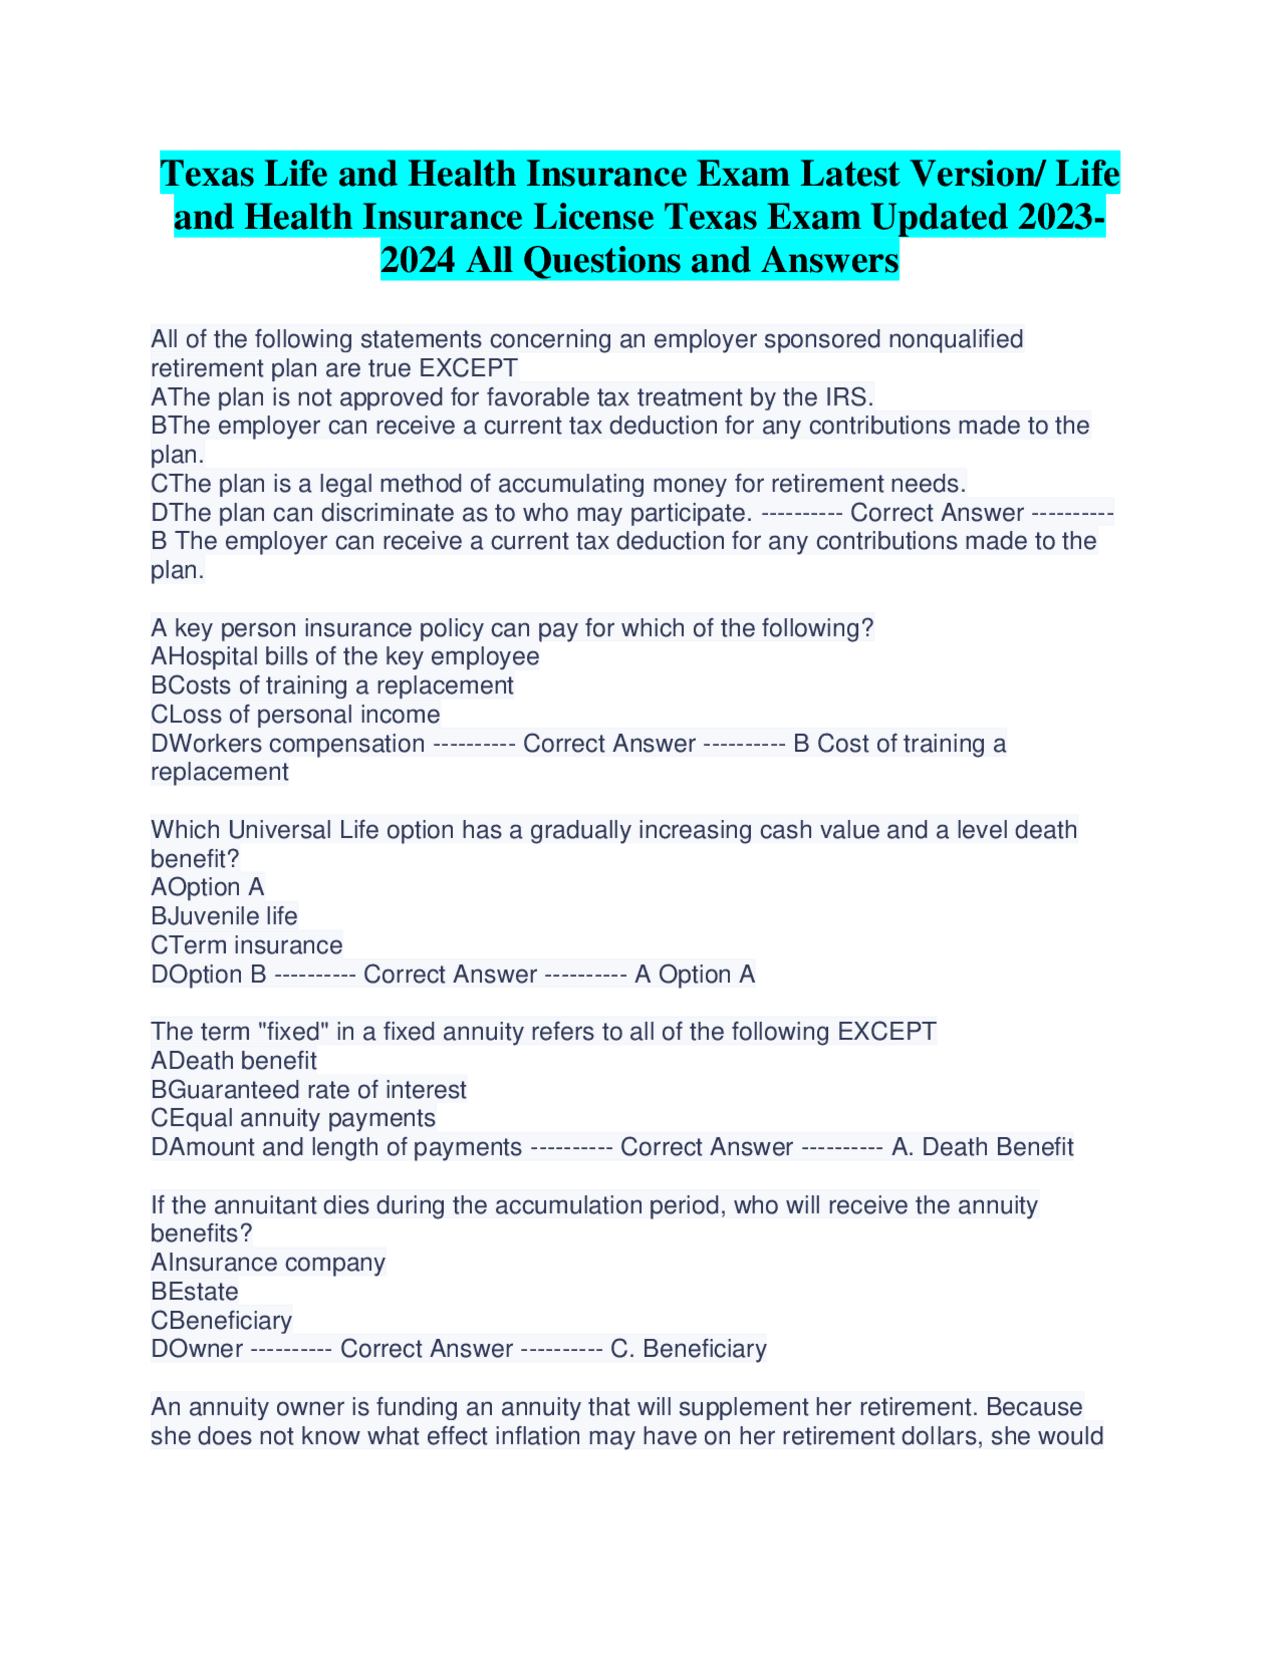
When you encounter an "example" in a study guide, it is rarely a simple definition-based question. Instead, these exams use situational vignettes. For instance, instead of asking "What is a Grace Period?", the exam might ask: "An insured has failed to pay their premium by the due date. The policy remains in force for an additional 30 days during which the premium can be paid without interest. What provision is being described?"
To interpret these examples effectively, you should apply a four-step diagnostic method:
- Identify the Policy Type: Is the scenario referring to a Life or Health policy? Certain provisions, like the "Incontestable Clause," apply differently in these contexts.
- Determine the Role of the Parties: Is the question asking from the perspective of the insurer, the insured, or the producer?
- Locate the Legal Trigger: Is there a specific law or ethical guideline being violated? For example, if a producer tells a client a policy is "guaranteed to pay dividends," you should immediately recognize this as "misrepresentation," a common prohibited practice.
- Eliminate Distractors: Most multiple-choice questions have two clear "wrong" answers and two that seem plausible. By filtering out the legally impossible options, you narrow the margin for error.
Comparative Analysis of Policy Provisions
The following table outlines common concepts tested in the exam, providing the baseline logic required to answer scenario-based questions correctly.
| Concept | Primary Purpose | Key Application |
|---|---|---|
| Free Look Provision | Consumer Protection | Allows a policyholder to review a policy and return it for a full refund within 10–30 days. |
| Grace Period | Policy Retention | Prevents immediate lapse due to an unintentional missed payment. |
| Reinstatement | Recovery | Allows a lapsed policy to be restored, usually subject to proof of insurability and back-payment. |
| Nonforfeiture Options | Cash Value Protection | Protects the owner’s equity if they stop paying premiums on a permanent life policy. |
| Incontestable Clause | Fraud Prevention | Limits the time an insurer can contest the validity of a contract due to misstatements on the application. |
Prerequisites and Preparation Strategies
Before scheduling your exam, you must fulfill the state’s pre-licensing education (PLE) requirements. Many states require a specific number of credit hours (e.g., 20 or 40 hours) through an approved provider. Do not treat these hours as a checklist; they are the baseline for your technical knowledge.
Effective Study Habits:
- Practice Exams: Utilize the simulation tools provided by your exam prep course. Aim to score consistently above 85% on practice tests before booking your official date.
- Focus on Weaknesses: If your scores are high in Life concepts but low in Health or State Law, dedicate specific study blocks to those domains.
- Flashcards for Terms: Use flashcards for acronyms and definitions of common policy riders (e.g., Waiver of Premium, Accidental Death Benefit, Cost of Living Rider).
- Environment Simulation: When taking practice tests, remove all distractions. Ensure you are familiar with the computer-based testing (CBT) interface, as some states use specialized software that limits navigation.
Navigating Common Pitfalls and Misconceptions
One of the most frequent errors students make is attempting to apply their own personal insurance experiences to the exam. Your personal policy or the policies of your relatives may have specific riders or non-standard provisions that do not align with the "textbook" definitions provided by the state. Always prioritize the manual provided by your state’s chosen testing vendor over outside anecdotal evidence.
Another common pitfall involves confusing "Disability Income" insurance with "Long-Term Care." While both are health-related, their definitions of "benefit triggers" are vastly different. Disability insurance triggers based on the inability to perform job duties (or daily activities), while Long-Term Care is triggered by cognitive impairment or the inability to perform Activities of Daily Living (ADLs) like bathing or dressing. Knowing the difference between these triggers is a standard high-value question on the exam.
The Professional Regulatory Environment
In 2026, the regulatory environment continues to emphasize consumer transparency. You are likely to see increased focus on the "Suitability and Best Interest" standards. This means that when the exam asks about recommending a product, the correct answer will almost always favor the option that best serves the client’s financial needs, rather than the product that provides the highest commission to the agent. Understanding this ethical framework is not just for the exam; it is a prerequisite for maintaining your license once you are active in the field.
Next Steps for Success
To successfully pass the life and health insurance exam, follow this logical progression:
- Verify State Requirements: Access your state's Department of Insurance website. Confirm the required pre-licensing hours and identify the testing vendor for your jurisdiction.
- Select an Accredited Provider: Choose a reputable study course that offers simulated "exam-mode" testing.
- Execute the Curriculum: Complete your PLE hours. Use the provided textbooks to build a conceptual map of insurance law.
- Simulate and Refine: Take multiple practice exams. If you fail a practice section, revisit the specific chapter in your material until you understand the underlying principle, not just the answer to that specific question.
- Schedule the Exam: Do not wait until you "feel" perfect; wait until your data indicates a high probability of passing. Register through the official vendor portal.
- Final Review: On the day before the exam, review your notes on state-specific laws and ethical guidelines, as these are easy points to gain if your memory is fresh.
The life and health insurance exam is a hurdle that rewards diligence and logical thinking. By treating the exam materials as a foundational regulatory roadmap rather than just a test of memory, you position yourself to not only pass the examination but to serve your future clients with a high degree of technical competence and ethical integrity.
Frequently Asked Questions
How long does it take to prepare for the life and health insurance exam? Most candidates spend between 40 to 80 hours of total study time, including the required pre-licensing education. The exact time depends on your prior familiarity with financial concepts and your ability to retain regulatory details.
Are all questions multiple-choice? Yes, most state insurance licensing exams are composed of multiple-choice questions. Some states have transitioned to computerized testing that may include "scenarios" where you must select the best course of action among several options.
What happens if I fail one section of the exam? Rules vary by state. In many jurisdictions, you can retake the failed section without needing to repeat the portion you already passed, provided you do so within a certain timeframe. Always check your specific state's rules regarding re-testing limits.
Is it necessary to memorize every state law? You should focus on the "Market Conduct" and "Producer Responsibilities" sections of your state law manual. While you cannot memorize the entire insurance code, you must be able to identify prohibited activities and standard administrative procedures.
How does the exam account for 2026 updates in insurance regulation? The exam content is updated periodically to reflect current statutes. Your study materials, provided by your approved education provider, are required to be updated to match the current examination syllabus for the 2026 calendar year.
What should I bring to the testing center? You must bring a valid government-issued photo ID that matches the name you used during registration. Check your specific appointment confirmation for any additional requirements, such as a confirmation number or secondary identification.
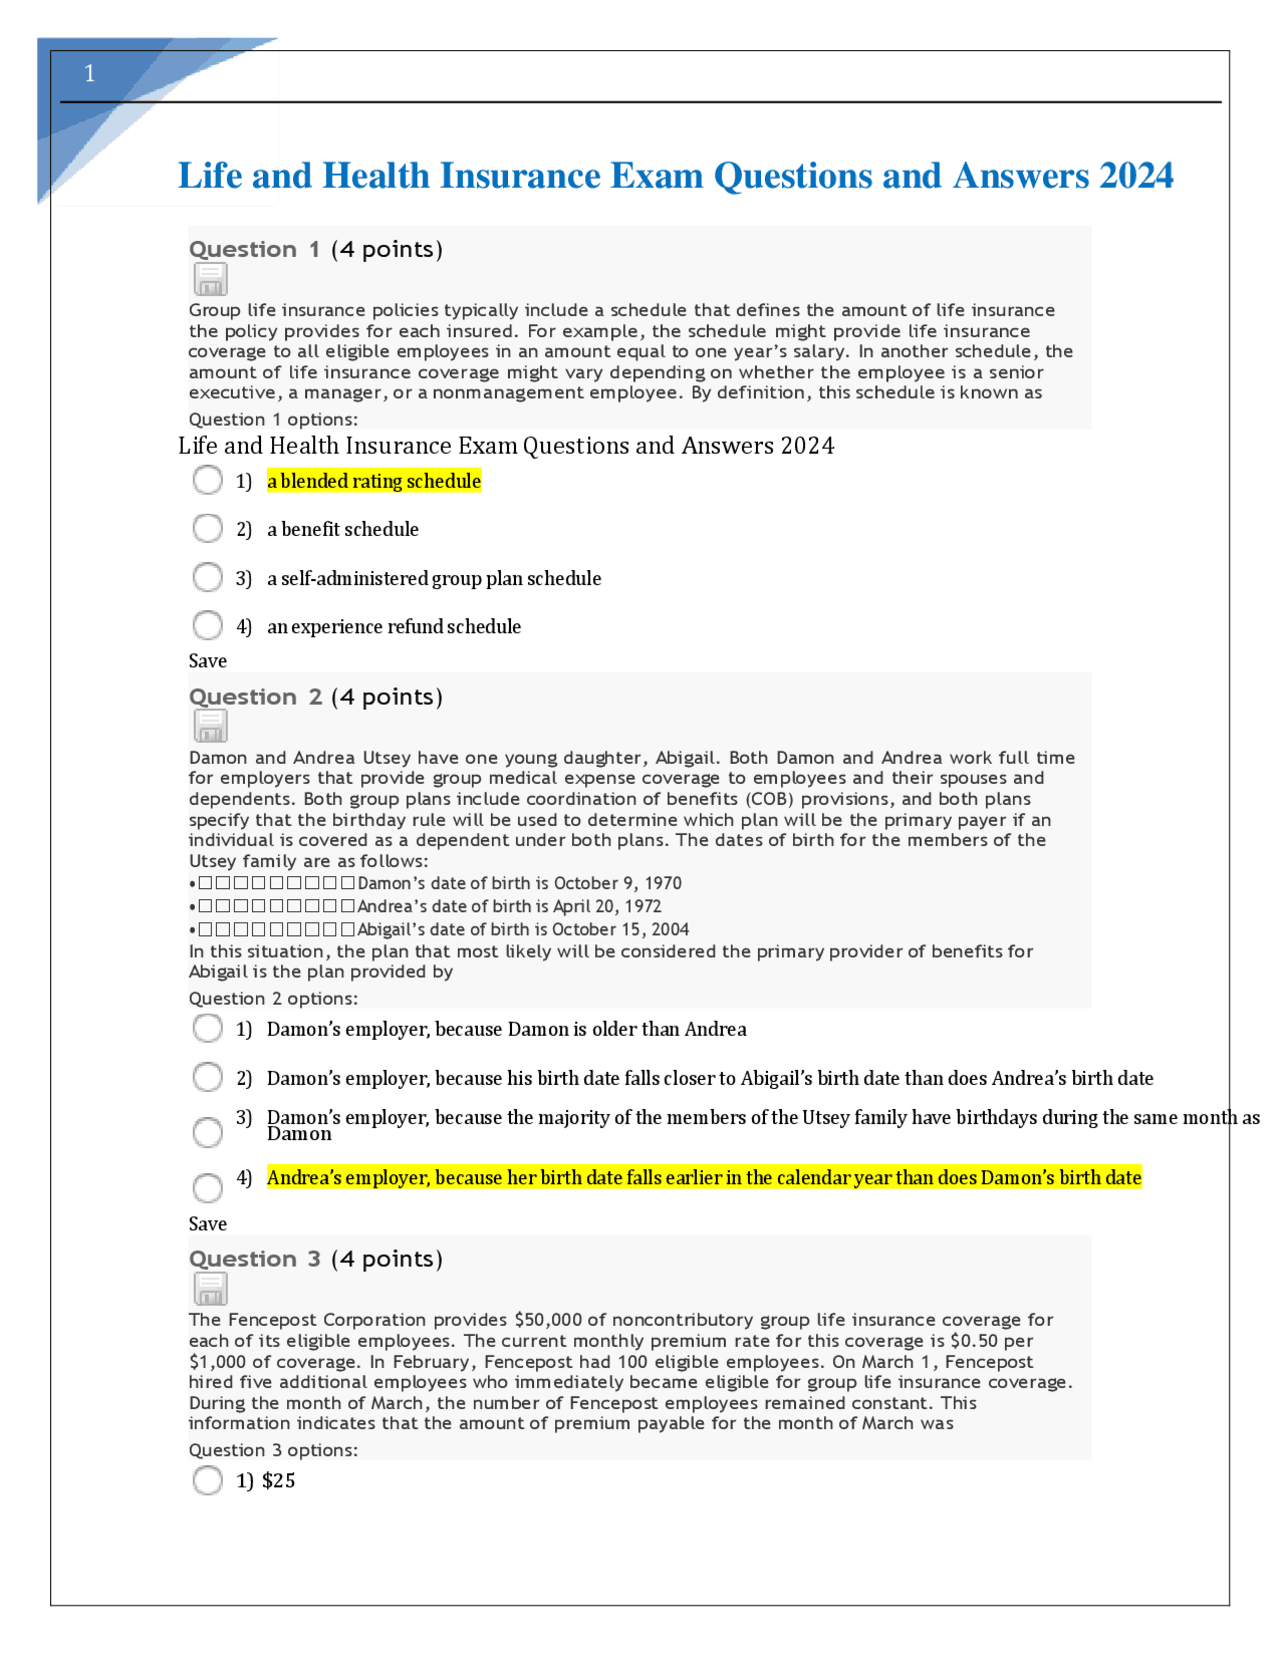
Image Gallery
Select an image to open it in a new tab.



Declan O'Connor
Higher Education and Campus Culture Reporter
