Navigating Collision Reimbursement Under Florida Auto Insurance Laws
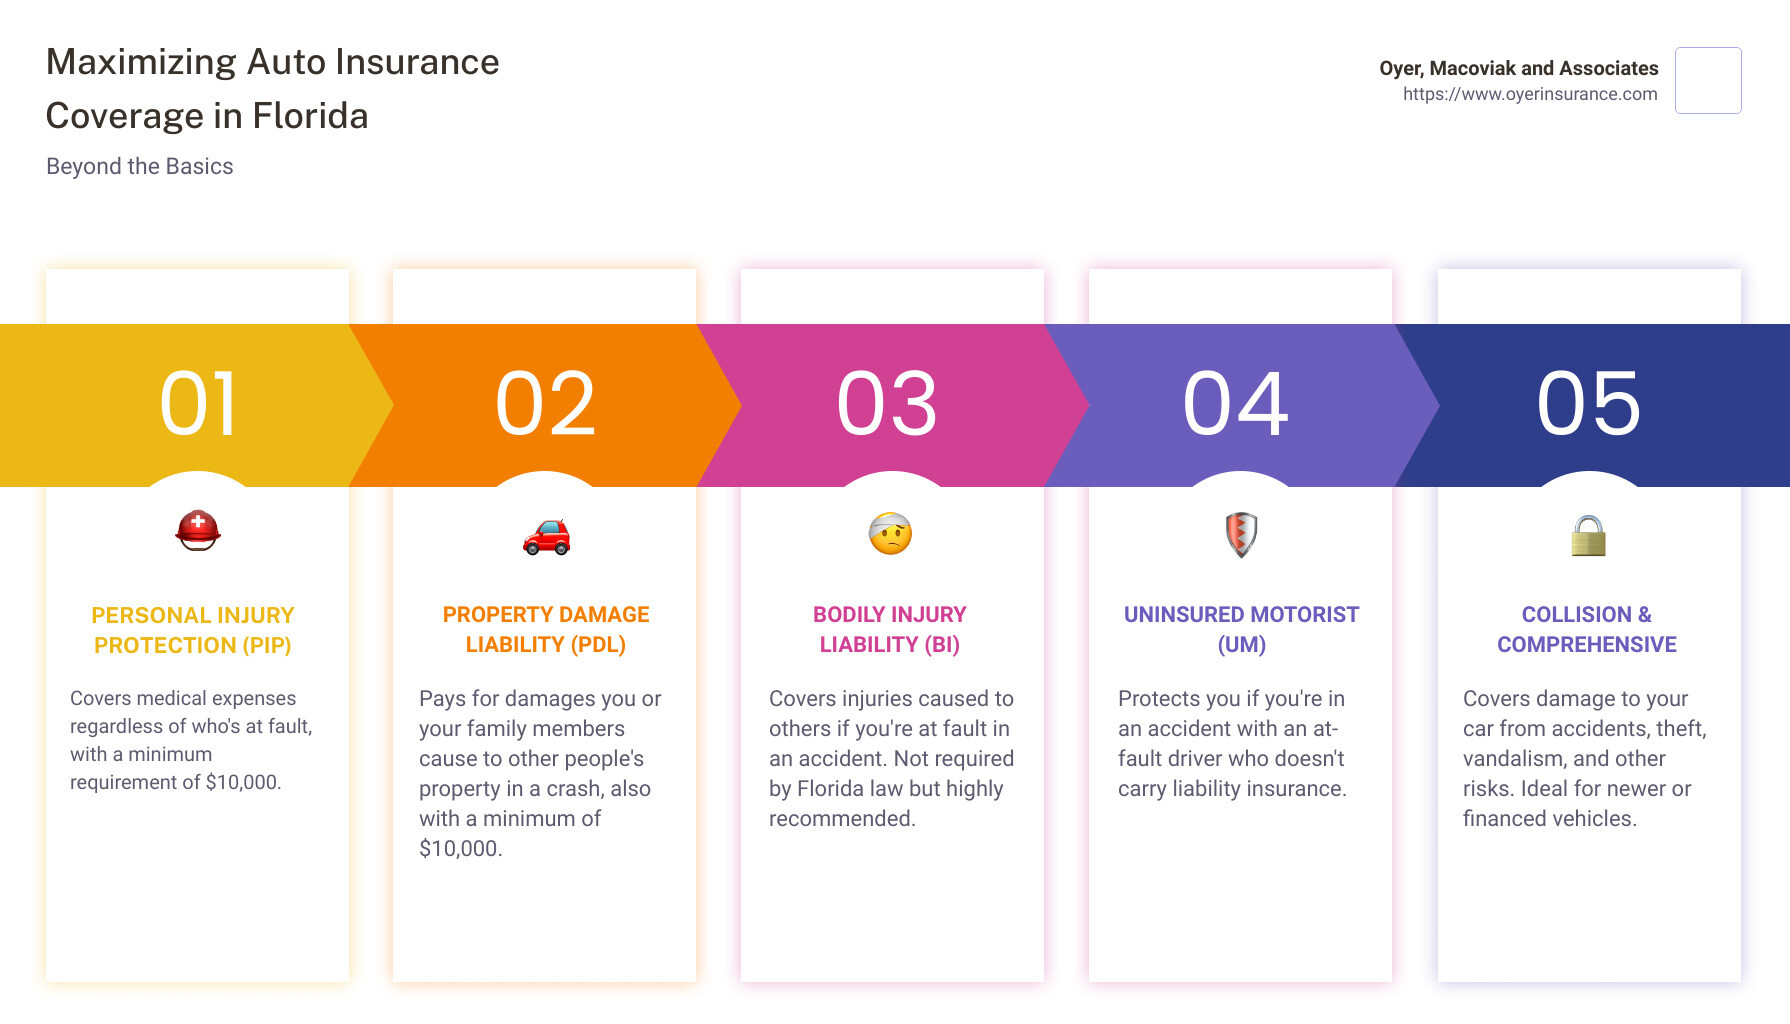
Understanding collision reimbursement under Florida auto insurance laws requires navigating the state's unique no-fault system and identifying how optional coverages interact with at-fault liability. In Florida, your own collision coverage is the primary mechanism for repairing your vehicle regardless of who caused the accident, as Personal Injury Protection (PIP) is strictly limited to medical expenses and lost wages, leaving property damage recovery to collision insurance or third-party liability claims.
The Florida Insurance Landscape: No-Fault vs. Property Damage
Florida is one of a handful of states that operate under a "no-fault" insurance system. This is a critical distinction that often confuses policyholders. Under Florida Statute § 627.736, the Personal Injury Protection (PIP) mandate ensures that regardless of who is at fault in a motor vehicle accident, your own insurance company pays for your medical bills and related expenses up to your policy limits.
However, the "no-fault" designation applies exclusively to bodily injury and medical costs. It does not extend to the repair or replacement of your vehicle. Collision reimbursement for your car is governed by traditional tort law principles, meaning you must either rely on your own collision coverage or pursue the at-fault driver’s Property Damage Liability (PDL) insurance. Because Florida requires all drivers to carry a minimum of $10,000 in Property Damage Liability, the state mandates that drivers have at least some financial responsibility for the property they damage, but this amount is often insufficient to cover the total cost of a modern vehicle's repair or replacement.
The Role of Collision Coverage
Collision coverage is an optional component of an auto insurance policy in Florida. Unlike PIP and PDL, which are mandatory, collision coverage is typically required only if you are financing or leasing your vehicle.
When you purchase collision coverage, you are entering into a contract where the insurer agrees to pay for the cost of repairing or replacing your vehicle after an accident, minus your chosen deductible. This is the most efficient way to ensure your vehicle is returned to its pre-accident condition because you are dealing directly with your own insurance provider, rather than waiting for an investigation into the other driver's liability or navigating the limits of their PDL coverage.
Comparing Reimbursement Mechanisms
When your vehicle is damaged in Florida, you generally have two primary pathways for reimbursement. Understanding the pros and cons of each is essential for making an informed financial decision.
| Feature | Collision Coverage (First-Party) | Property Damage Liability (Third-Party) |
|---|---|---|
| Eligibility | Your own policy | Policy of the at-fault driver |
| Deductible | Yes (You pay your deductible) | No (The at-fault party pays) |
| Speed of Process | Faster (Direct communication) | Slower (Liability investigation required) |
| Control | High (Policy terms apply) | Low (Subject to insurer disputes) |
| Coverage Limits | Market value of vehicle | Often limited to $10,000 minimum |
The "Deductible" Factor
A major consideration in collision reimbursement is the deductible. When you file a claim under your own collision policy, the insurer will subtract your deductible from the final payout. For example, if your repairs cost $5,000 and your deductible is $500, the insurance company will pay $4,500, and you are responsible for the remaining $500 paid to the repair shop.
While selecting a higher deductible can lower your monthly premium, it creates a larger financial burden at the time of an accident. Conversely, a low or zero-deductible policy ensures that you face minimal out-of-pocket expenses, but it increases your recurring monthly costs. In Florida’s aggressive litigation environment, having a manageable deductible is a common recommendation to ensure you can afford the repairs if an accident occurs.
Understanding "Total Loss" and Market Value
One of the most complex areas of collision reimbursement occurs when the cost of repairs approaches or exceeds the vehicle's actual cash value (ACV). In such scenarios, the insurance company will declare the vehicle a "total loss."
Florida law and insurance industry standards generally dictate that a car is considered a total loss if the cost of repair, combined with the salvage value of the wrecked vehicle, exceeds the car's pre-accident market value. When this happens, the insurer does not owe you the amount you paid for the car, nor the amount you owe on your loan; they owe you the fair market value of the vehicle at the time of the accident.
To determine this value, insurers look at:
- Vehicle Condition: The pre-accident mechanical and cosmetic state of your vehicle.
- Comparable Sales: Recent sales prices of similar vehicles in your local geographic area.
- Depreciation: The age, mileage, and wear-and-tear factors that reduce value.
If you are "underwater" on your loan (meaning you owe more than the car is worth), collision coverage alone will not cover the deficiency. This is why many Florida drivers opt for "gap insurance," which pays the difference between the ACV settlement and your remaining loan balance.
Steps to Initiate a Collision Claim
When an accident occurs in Florida, taking the correct steps immediately is vital to ensure a smooth reimbursement process.
- Document the Scene: Take photos of the damage to all involved vehicles, the positioning of the cars, and the surrounding environment, including traffic signs or signals.
- Obtain the Police Report: In Florida, if an officer responds to the scene, they will create a long-form or short-form crash report. This document is crucial for proving the sequence of events.
- Notify Your Insurer: Contact your insurance company immediately. Even if the other party is at fault, notifying your own insurer creates a record of the event.
- Obtain Repair Estimates: Most insurance companies have preferred repair shops. While you are generally free to choose your own mechanic, using a preferred shop can expedite the appraisal process, as the insurer and the shop often have pre-negotiated rates and direct billing arrangements.
- Review the Settlement Offer: The insurance company will provide an itemized estimate. Compare this against your policy declarations page to ensure the deductible and coverage limits are applied correctly.
Common Pitfalls and Troubleshooting
A frequent issue in Florida is the "diminished value" claim. Even after a vehicle is professionally repaired, its market value may be lower than it was before the accident because of the history of damage. In Florida, collecting for diminished value through your own collision policy is generally not permitted unless explicitly stated in your contract. While you can sometimes sue the at-fault driver for diminished value, these claims are notoriously difficult to prove and often require expert testimony, which can cost more than the value you are trying to recover.
Another common mistake is failing to verify the other driver’s insurance status. Florida has a high rate of uninsured motorists. If the person who hits you does not have adequate PDL coverage, or has no insurance at all, your only recourse is your own Collision coverage or your Uninsured Motorist Property Damage (UMPD) coverage, if you have purchased it.
Legal Limitations and Professional Guidance
Insurance law in Florida is subject to frequent legislative updates and shifting judicial precedents. While this guide provides a comprehensive overview of how collision reimbursement generally operates as of 2026, it does not constitute legal advice.
If you find yourself in a dispute with your insurance company regarding a total loss valuation, a denied repair estimate, or a failure to pay within the timelines established by the Florida Office of Insurance Regulation, you may need to file a formal complaint with the Florida Department of Financial Services. If your claim involves significant financial loss or if the insurance company is acting in "bad faith," consulting with a licensed attorney specializing in Florida insurance law is the recommended course of action.
Frequently Asked Questions
Does Florida's no-fault law prevent me from suing the at-fault driver for vehicle repairs? No. Florida’s no-fault law (PIP) only pertains to medical and bodily injury expenses. You maintain the right to pursue the at-fault driver for property damage (the cost of vehicle repairs) either through their liability insurance or through civil litigation.
Is collision coverage required in Florida? Collision coverage is not legally mandated by the state. However, if you are currently paying off an auto loan or have a lease agreement, your lender will almost certainly require you to maintain collision coverage until the debt is satisfied.
What happens if the other driver’s insurance is not enough to cover my repairs? If the other driver has the state minimum of $10,000 in Property Damage Liability and your repair costs exceed that, you must rely on your own collision coverage to bridge the gap. If you do not have collision coverage, you would be forced to pay the difference out-of-pocket or seek a judgment against the at-fault driver in court.
Can I pick any auto body shop for my repairs? Yes, under Florida regulations, you have the right to choose your repair facility. However, if you choose a shop that charges more than the prevailing competitive rate in the area, the insurance company may only be obligated to pay the reasonable market rate, leaving you responsible for the difference.
What is the difference between collision and comprehensive coverage? Collision coverage pays for damages resulting from a crash with another vehicle or an object, such as a pole or guardrail. Comprehensive coverage pays for non-collision-related damage, such as theft, fire, vandalism, or damage from fallen objects like tree branches.
Next Steps for Policyholders
To ensure you are protected, review your current insurance declarations page today. Verify that your collision deductible is at an amount you can afford to pay immediately if an accident occurs. If you own a newer vehicle, consider whether your current coverage limits are sufficient to cover the total replacement cost in the event of a catastrophic accident. Keeping a digital copy of your policy and the contact information for your claims department in a secure location can save you significant time and stress if you are involved in a collision.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
