
California’s Low-Cost Automobile (LB) insurance program, officially known as the California Low-Cost Automobile Insurance Program (CLCA), is a state-mandated initiative designed to provide an affordable liability insurance option for low-income, good drivers. It is fundamentally different from standard private insurance because it allows policyholders to carry coverage limits below the standard state minimums, acts as a legal alternative to satisfy financial responsibility laws, and utilizes income-based eligibility rather than purely risk-based pricing.
Managed by the California Department of Insurance (CDI) and established by the state legislature, this program addresses the specific socio-economic challenge of uninsured motorists. By the year 2026, the program continues to serve as a critical safety net, ensuring that high premiums do not prevent lower-income residents from driving legally to work, school, and essential services.
Understanding the Origin and Purpose of the LB Program
The "LB" or Low-Cost program was born out of a legislative effort to reduce the number of uninsured drivers on California roads. For many years, a significant portion of the population remained uninsured not out of defiance of the law, but due to the high cost of standard premiums relative to their household income.
The program was initially piloted in Los Angeles and San Francisco counties before being expanded statewide. Its primary mission is to ensure that "good drivers" who fall within specific income brackets have access to a policy that is both affordable and legally recognized. Unlike the private market, where profit margins and complex risk modeling drive prices, the CLCA program is focused on public safety and legal compliance. It is administered by the California Automobile Assigned Risk Plan (CAARP), which ensures that the risks are distributed among all insurers doing business in the state.
Key Differences: Coverage Limits vs. Standard California Insurance
The most significant way California’s LB insurance differs from a standard policy is the level of coverage it provides. In the private market, California law requires all drivers to carry a minimum of 15/30/5 coverage. However, the LB program provides a "legislated exception" to these limits.
Comparison of Liability Limits (2026 Standards)
| Feature | Standard CA Private Policy | California Low-Cost (LB) Policy |
|---|---|---|
| Bodily Injury (Per Person) | $15,000 | $10,000 |
| Bodily Injury (Per Accident) | $30,000 | $20,000 |
| Property Damage | $5,000 | $3,000 |
| Legal Compliance | Meets CA Financial Responsibility | Meets CA Financial Responsibility |
| Eligibility | Open to all licensed drivers | Income and Driving Record Restrictions |
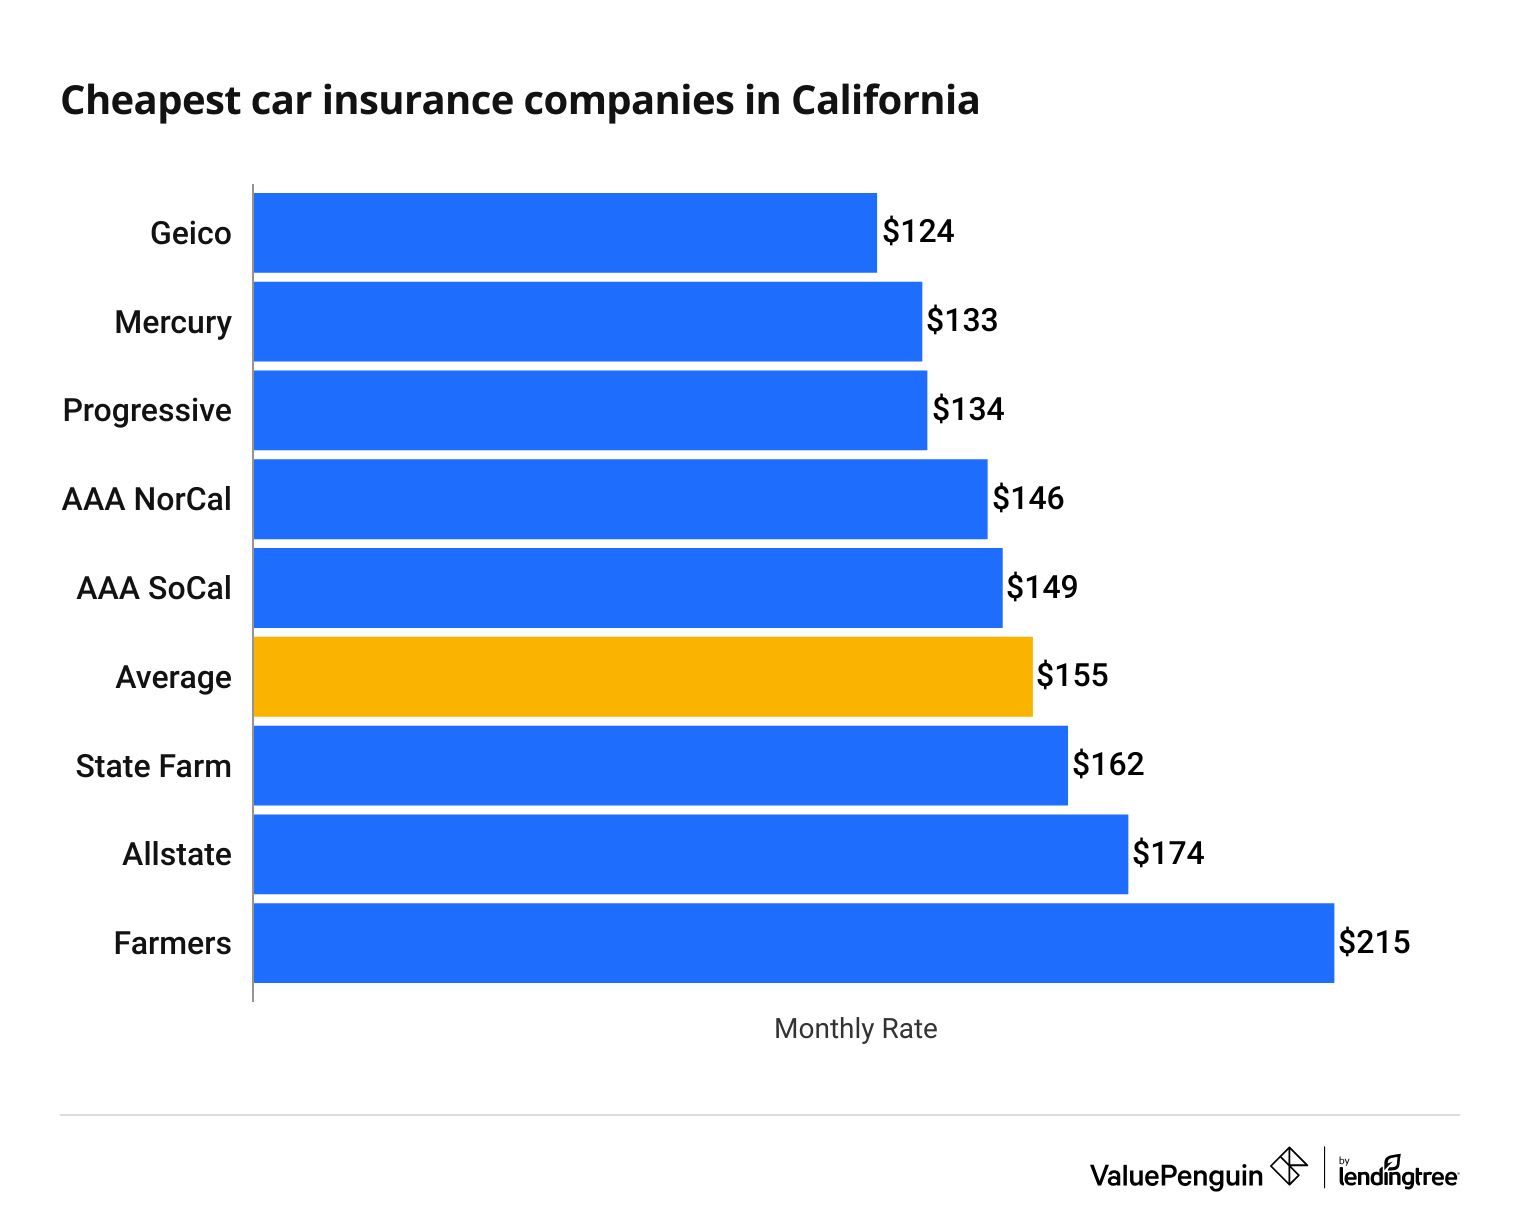
| Average Annual Cost | $800 - $2,500+ | $250 - $600 (varies by county) |
The reduction from $15,000 to $10,000 for individual bodily injury and the drop to $3,000 for property damage allows the premium to stay significantly lower. While these limits are lower, the State of California recognizes an LB policy as full compliance with the law. This means a driver with an LB policy cannot be cited for driving without insurance, and they can register their vehicle with the DMV just like any other insured driver.
Eligibility Requirements: Who Qualifies in 2026?
Because the LB program is subsidized in its structure and intent, it is not available to the general public. To maintain its status as a targeted social program, the California Department of Insurance enforces strict eligibility criteria.
Income Constraints
Eligibility is primarily tied to the Federal Poverty Level (FPL). As of 2026, an applicant's household income must be at or below 250% of the FPL. This ensures that the program is reserved for those who truly struggle to meet the costs of standard private insurance. For a single-person household, this threshold is adjusted annually, and documentation such as tax returns or W-2 forms is required during the application process.
Vehicle Value Limits
To prevent the program from being used to insure luxury vehicles at a discount, there is a maximum vehicle value limit. Generally, the vehicle must be valued at $25,000 or less. This value is determined based on the current market value at the time of application or renewal. If a driver owns a vehicle worth $50,000, they are deemed to have sufficient assets to potentially afford standard insurance or are considered a higher financial risk than the program intends to cover.
The "Good Driver" Requirement
The LB program is specifically for "good drivers." This is a crucial distinction. It is not a high-risk pool for drivers with multiple DUIs or reckless driving charges. To qualify, an applicant must:
- Have a valid California driver’s license.
- Be at least 16 years old.
- Have a "clean" driving record, which typically means no more than one "at-fault" property damage-only accident or one moving violation point in the past three years.
- Not have a felony or misdemeanor conviction for a violation of the Vehicle Code on their record within the last three years.
Why the Lower Limits Matter: Risks and Benefits
While the primary benefit of LB insurance is affordability and legality, the lower limits present a specific risk profile that drivers must understand. In a standard accident in 2026, $3,000 in property damage coverage is relatively low. Given the rising costs of vehicle repairs and the prevalence of expensive electric vehicles and SUVs on California roads, a $3,000 limit can be exhausted very quickly.
If an LB policyholder causes an accident that results in $10,000 of damage to another person's car, the insurance company will pay the $3,000 limit, but the driver remains personally liable for the remaining $7,000. This is the "trade-off" of the program. It provides a "get legal" shield and basic protection, but it does not offer the robust asset protection found in higher-limit private policies. For the target audience—those with limited liquid assets—this trade-off is often the only viable path to legal driving.
Add-on Coverages and Limitations
The LB program focuses almost exclusively on liability. Unlike private insurance where you can easily bundle comprehensive and collision (often called "full coverage"), the LB program is designed to be lean.
- Uninsured Motorist (UM) Bodily Injury: This is an optional add-on within the LB program. It covers the policyholder if they are hit by someone who has no insurance. The limits for this are typically $10,000 per person and $20,000 per accident.
- Medical Payments: Another optional coverage, usually providing $1,000 per person for medical expenses resulting from an accident, regardless of fault.
- Physical Damage (Collision/Comprehensive): The LB program itself does not offer collision or comprehensive coverage. If a driver has a car loan, the lender will almost certainly require these coverages. Therefore, the LB program is generally most suitable for drivers who own their cars outright (older models) and do not have a lienholder requiring full coverage.
The Application Process: How to Enroll
Enrolling in the California Low-Cost Automobile Insurance Program is different from getting a quote on a standard commercial website. Because it is a state-administered program, applicants must go through certified agents or the official CLCA website (mylowcostauto.com).
The process involves:
- The Eligibility Test: A series of questions regarding household size, income, and driving history.
- Document Submission: Providing proof of income (tax returns, social security papers, or pay stubs) and vehicle registration.
- Payment: Payments can be made in full or through an installment plan. In 2026, the program maintains a consistent installment structure to help households manage their cash flow.
- Assignment: Once the application is approved, the policy is assigned to a private insurance company that has been designated by the state to handle CLCA policies. The policyholder then interacts with that specific company for claims and customer service.
Regional Pricing and Premium Determinants
Even within the LB program, the price is not the same for everyone in California. Premiums are set by county, reflecting the local risk of accidents and the cost of living. For example, a driver in Los Angeles County will likely pay a higher premium than a driver in a more rural county like Humboldt.
However, unlike private insurance, the LB program does not use "zip code" granularity or credit scores to determine the price. It uses the county as the primary geographical unit. This simplifies the pricing structure and prevents the "redlining" or hyper-local price spikes often seen in the private market. As of 2026, annual premiums generally range between $250 and $600, depending on the county and whether the driver is under the age of 25 (who may face a slightly higher "young driver" surcharge).
Legal Protections and the Financial Responsibility Law
California Vehicle Code Section 16056 establishes the standard 15/30/5 limits, but Section 16056.1 provides the legal carve-out for the Low-Cost program. This is a vital distinction for law enforcement and the DMV.
When a driver is stopped by the California Highway Patrol or local police, presenting a CLCA insurance card is sufficient proof of financial responsibility. Furthermore, this program is recognized for SR-22 filings. If a driver needs an SR-22 to reinstate a license following a suspension (provided they still meet the "good driver" criteria for the program), an LB policy can satisfy that requirement.
Common Misconceptions About LB Insurance
There are several myths surrounding the LB program that often lead to confusion:
- "It’s free insurance." This is false. It is low-cost, not a government handout. Policyholders must pay their premiums.
- "Anyone can get it if they want to save money." False. If your income exceeds 250% of the FPL or your car is worth more than $25,000, you are ineligible.
- "The coverage is bad." The coverage is limited, but it is not "bad." It is a legally valid contract that pays out according to its terms. It simply has lower ceilings for payouts.
- "It covers my own car if I'm in an accident." Usually false. As a liability-first program, it pays for the other person's damages. It only covers the policyholder's medical bills if the optional Medical Payments coverage is purchased.
Summary of Next Actions for California Drivers
If you believe you qualify for California’s LB auto insurance, your first step is to verify your household income against the current 250% Federal Poverty Level guidelines for 2026. If you meet the criteria and own a vehicle valued under $25,000 with a clean driving record, visit the official California Low-Cost Automobile Insurance Program website or contact a local agent certified by CAARP.
For those who do not qualify, it is essential to maintain standard 15/30/5 coverage to avoid heavy fines, vehicle impoundment, or license suspension. The LB program remains a specialized tool for a specific demographic, ensuring that the road to economic mobility in California is not blocked by the inability to afford a basic insurance policy.
Frequently Asked Questions
Does LB insurance cover me if I drive for a ride-sharing service?
No. Like most personal auto policies, California’s Low-Cost Automobile insurance typically excludes coverage for commercial use, including ride-sharing (like Uber or Lyft) or delivery services. Using an LB policy for these activities can lead to a denial of claims and policy cancellation.
Can I have an LB policy if I have a loan on my car?
Technically, the state allows it, but your bank or lienholder likely won't. Most auto loans require "full coverage" (Collision and Comprehensive), which the LB program does not provide. If you have a car loan, check your finance agreement before switching to an LB policy.
What happens if I move to a different county?
If you move, you must notify the program or your assigned insurer. Since LB premiums are based on the county of residence, your premium may increase or decrease. Failure to report a move can jeopardize your coverage in the event of a claim.
Is there an age limit for the LB program?
There is no upper age limit, but you must be at least 16 years old and have a valid driver's license. Drivers under the age of 25 may see a slight surcharge on their premium, but the program remains significantly cheaper than private market options for young drivers.
How often do I need to re-qualify for the program?
Eligibility is usually reviewed annually during the renewal process. You will be required to provide updated income documentation to ensure you still fall within the 250% FPL threshold. If your income increases beyond the limit, you will need to transition to a standard private insurance policy.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
