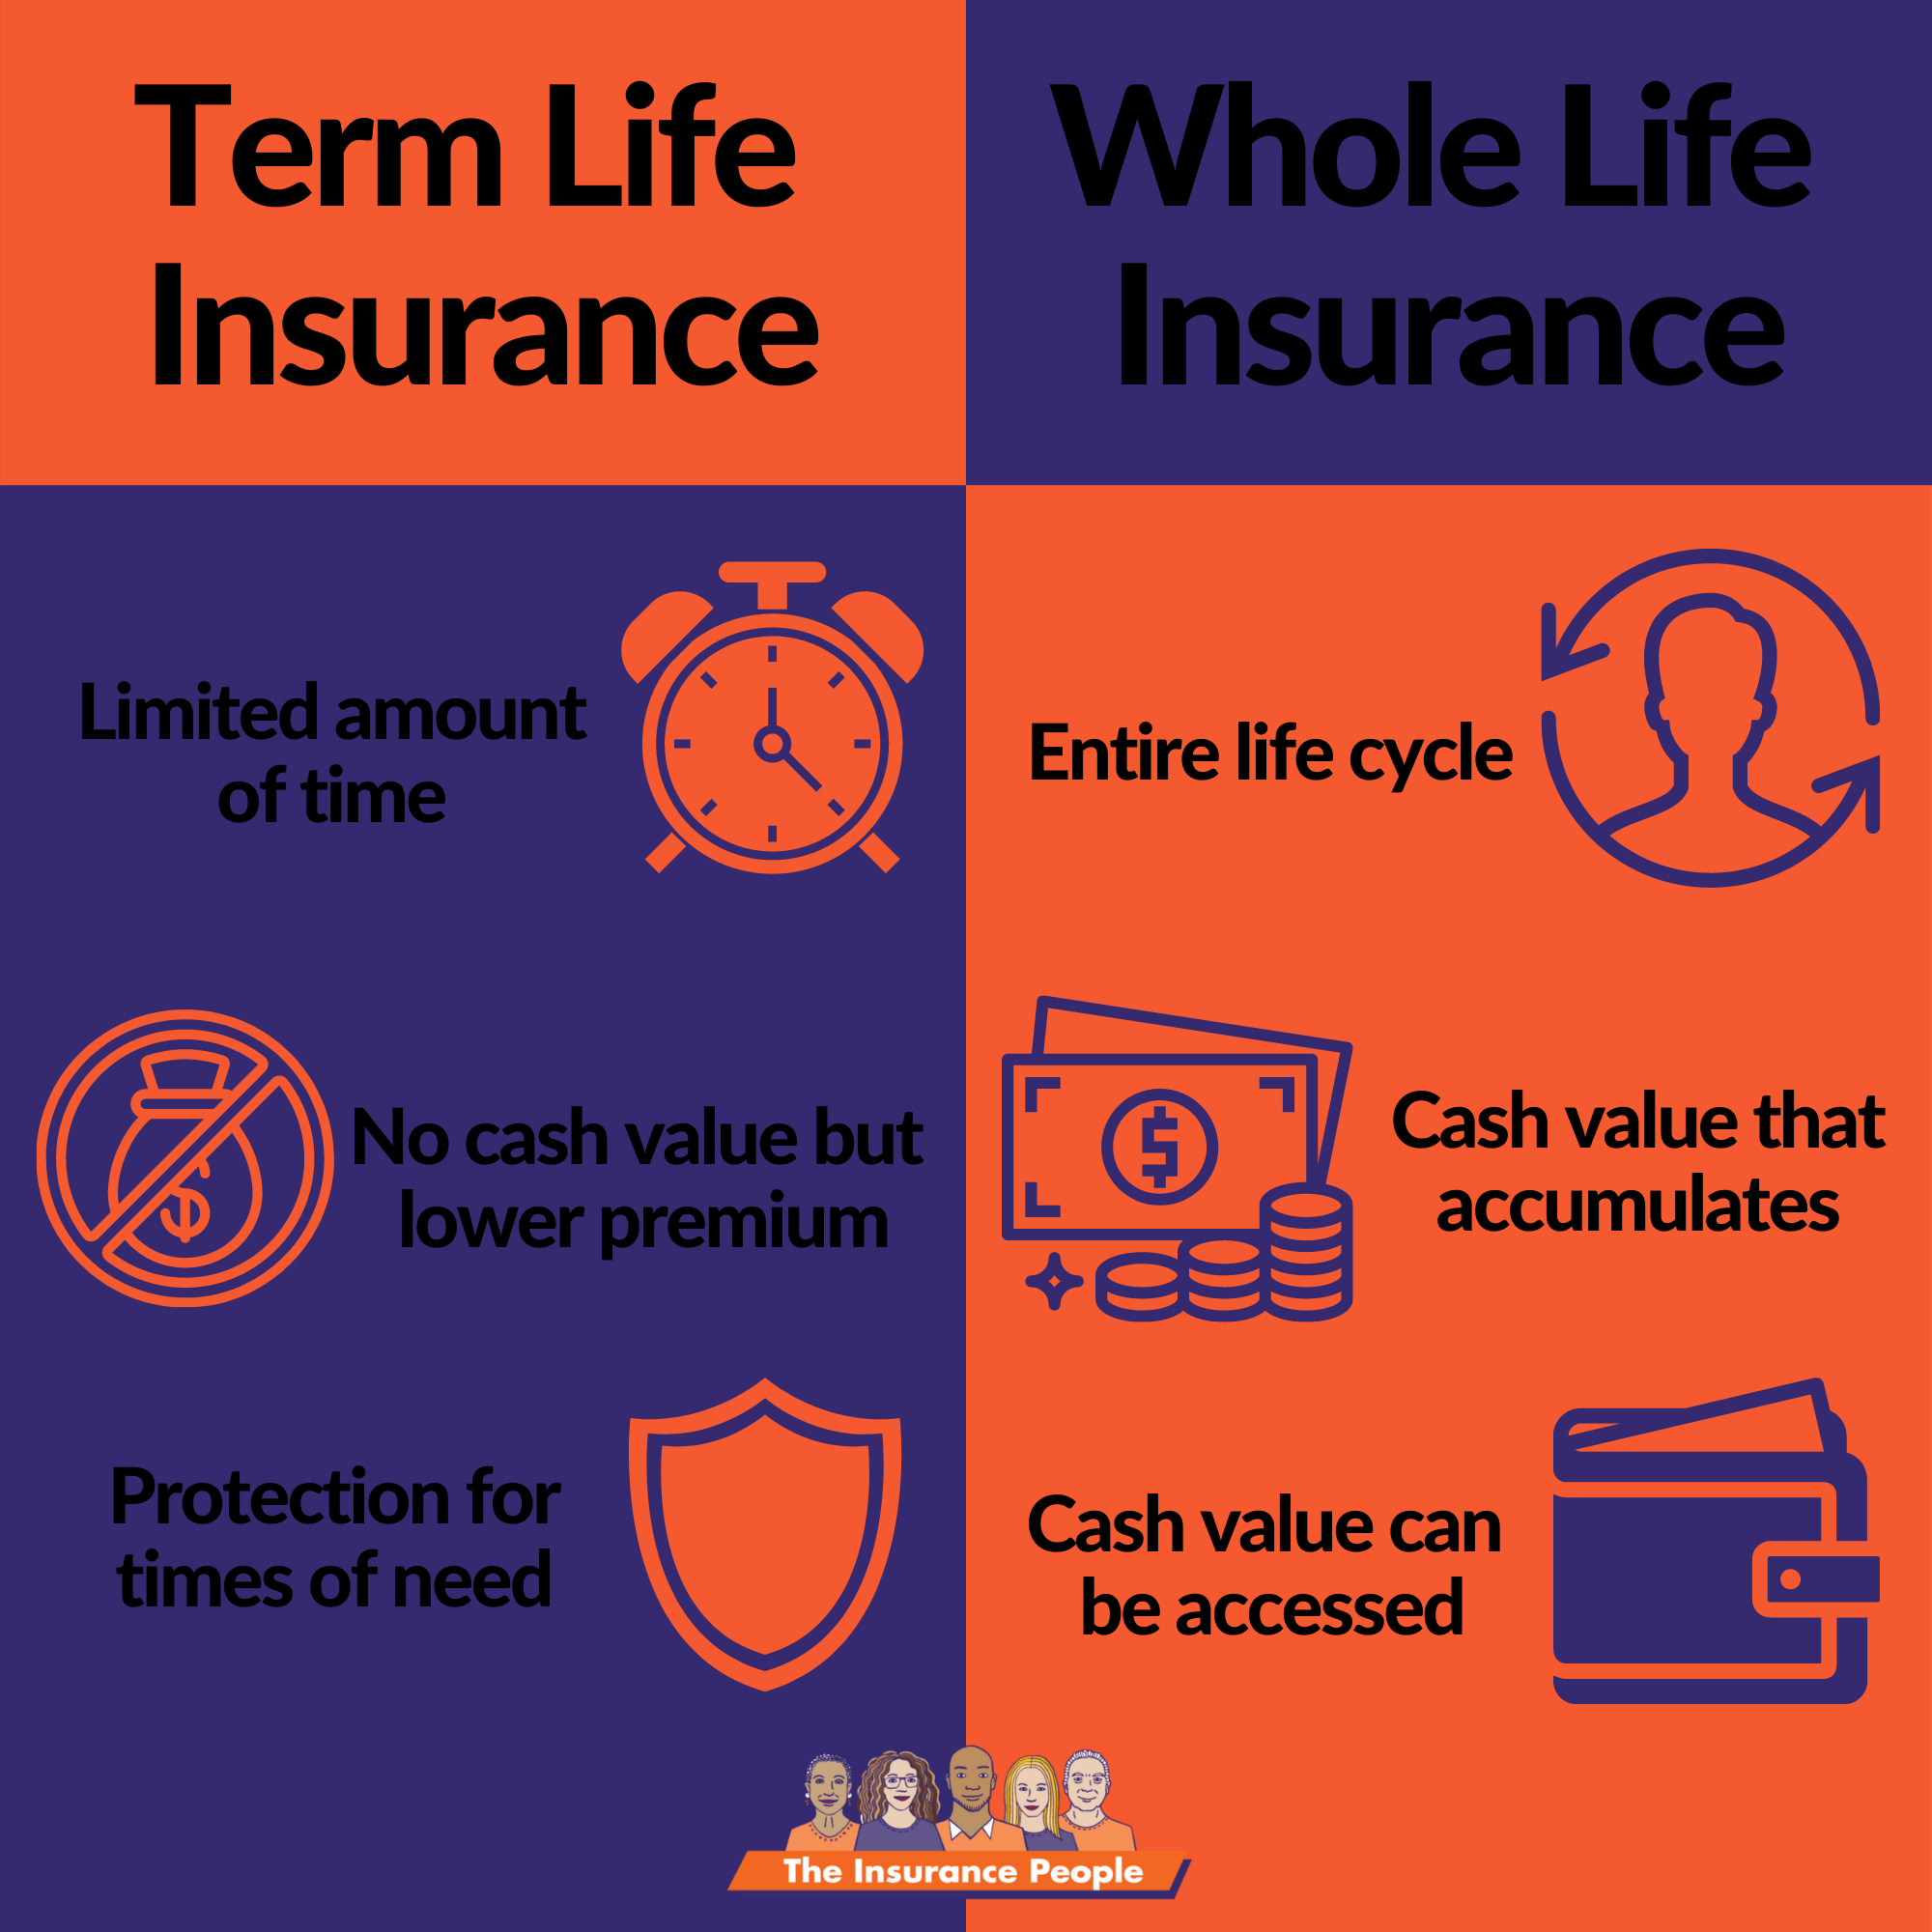
When planning financial security, choosing between whole life and term life insurance requires a clear understanding of your long-term goals, budget, and risk tolerance. While term life insurance offers affordable, temporary protection for specific milestones like raising children or paying off a mortgage, whole life insurance provides permanent coverage coupled with a cash value investment component. Weighing these two distinct financial tools involves analyzing how their premiums, duration, financial growth mechanisms, and estate planning implications align with your personal circumstances.
Understanding the Fundamentals of Life Insurance Categories
Before diving into a direct comparison, it is critical to separate the mechanics of temporary coverage from permanent financial vehicles. Life insurance is fundamentally designed to replace lost income, cover final expenses, and secure the financial stability of dependents in the event of an insured's death. However, the market offers a spectrum of products that achieve these goals through different mechanisms.
Term life insurance acts much like an auto or home insurance policy: you pay a monthly or annual premium for a predetermined period—typically 10, 20, or 30 years. If you pass away during that term, your beneficiaries receive a tax-free death benefit. If you outlive the term, the policy expires, and no payout is made unless you renew it (usually at a significantly higher rate) or convert it to a permanent policy.
Conversely, whole life insurance is a form of permanent life insurance. As long as you continue to pay the required premiums, the policy remains active for your entire life. It guarantees a death benefit while simultaneously building cash value on a tax-deferred basis. A portion of each premium payment goes toward the cost of insurance, while the remainder is invested by the insurer, accumulating a cash reserve that you can borrow against or withdraw during your lifetime.
Term Life Insurance: Benefits and Drawbacks
Term life insurance is frequently recommended by financial advisors for young families and individuals who need maximum coverage during their peak earning and debt-accumulation years. Understanding its advantages and limitations helps determine if it suits your financial strategy.
The Benefits of Term Life Insurance
- Affordability: Term life insurance is substantially cheaper than whole life insurance. Because the insurer only takes on the risk of payout for a specific timeframe, younger, healthy applicants can secure high death benefits—such as $500,000 or $1,000,000—for a modest monthly premium.
- Simplicity and Transparency: The structure of a term policy is straightforward. You select a coverage amount and a term length. There are no complex investment sub-accounts, cash value growth charts, or hidden surrender charges.
- Ideal for Temporary Liabilities: It matches the timeline of major financial obligations. If you have a 30-year mortgage and children who will be financially independent in two decades, a 20- or 30-year term policy covers that exact window of vulnerability.
The Drawbacks of Term Life Insurance
- Expiration Risk: If you outlive your term, your coverage ends. Renewing the policy annually after expiration often triggers prohibitive age-based rate increases, making it financially impractical to maintain.
- No Return on Investment: Unless you purchase a specialized "return of premium" rider—which increases your base rate—term insurance builds no equity or cash value. If you outlive the policy, all the premiums paid are gone.
- Vulnerability to Health Changes: If your health declines significantly during your term, you may find yourself uninsured or facing astronomical rates once the initial policy expires, as qualifying for a new policy requires passing medical underwriting.

Whole Life Insurance: Benefits and Drawbacks
Whole life insurance targets individuals seeking lifelong protection and an additional conservative asset class for wealth accumulation or estate planning.
The Benefits of Whole Life Insurance
- Lifetime Guaranteed Coverage: Whole life insurance provides a permanent safety net. As long as premiums are paid, the policy cannot be canceled by the insurer, and the death benefit is guaranteed to be paid out whenever you pass away.
- Cash Value Accumulation: A portion of your premium is directed into a cash value account that grows at a guaranteed minimum interest rate. Many mutual insurance companies also pay annual dividends, which can be used to purchase additional insurance, reduce premiums, or be taken as cash.
- Borrowing Power: You can take out policy loans against your accumulated cash value. These loans generally do not require credit checks or formal approval, though unpaid loans and accumulated interest will reduce the final death benefit payout.
The Drawbacks of Whole Life Insurance
- High Cost: Whole life premiums are typically 5 to 15 times more expensive than term life premiums for the same amount of coverage. This high cost can strain household budgets, potentially forcing policyholders to buy less coverage than their families actually need.
- Complex Structures and Fees: Administrative fees, surrender charges, and internal costs are embedded in permanent policies. Surrendering the policy within the first several years often incurs severe financial penalties.
- Lower Comparative Returns: While the cash value grows tax-deferred, the internal rate of return on whole life insurance is generally lower than what could be achieved through disciplined investing in diversified stock and bond portfolios, such as index funds or retirement accounts like a 401(k) or IRA.
Comparative Analysis: Term versus Whole Life Insurance
To clearly evaluate which policy structure aligns with your financial priorities, examine the direct operational and financial differences outlined below.
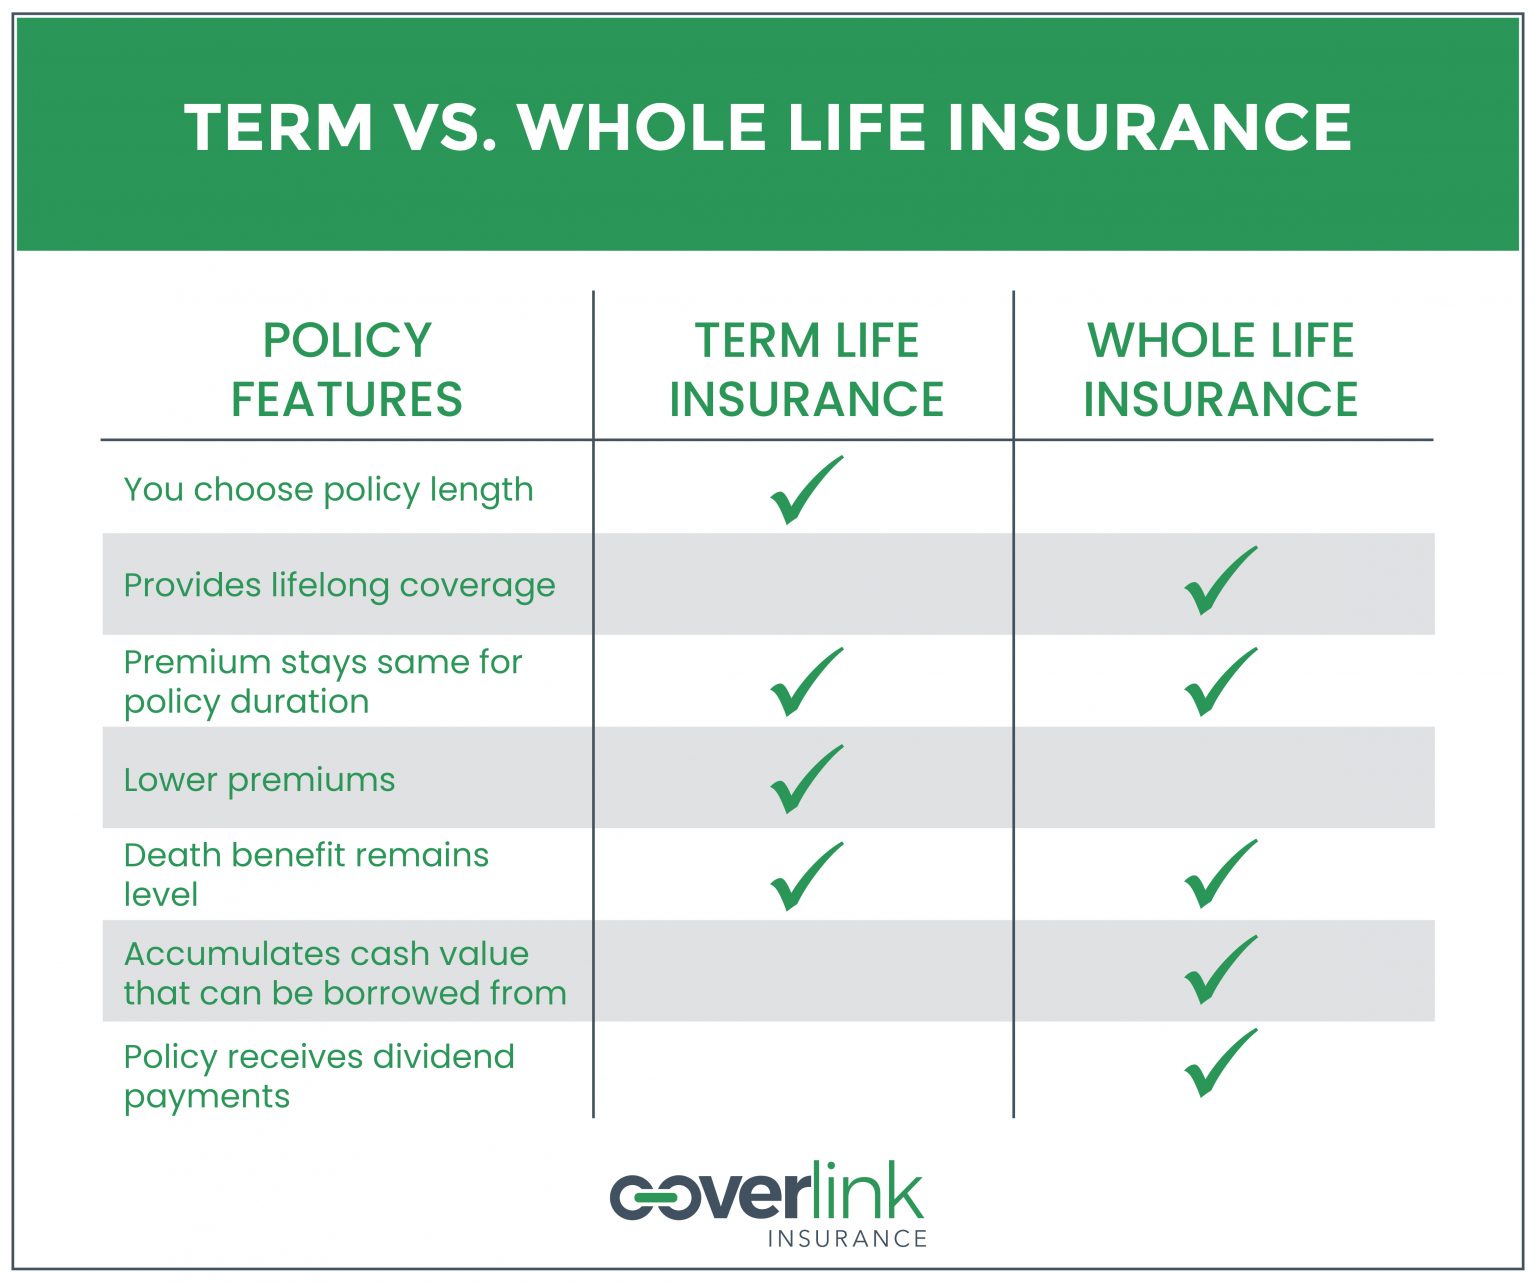
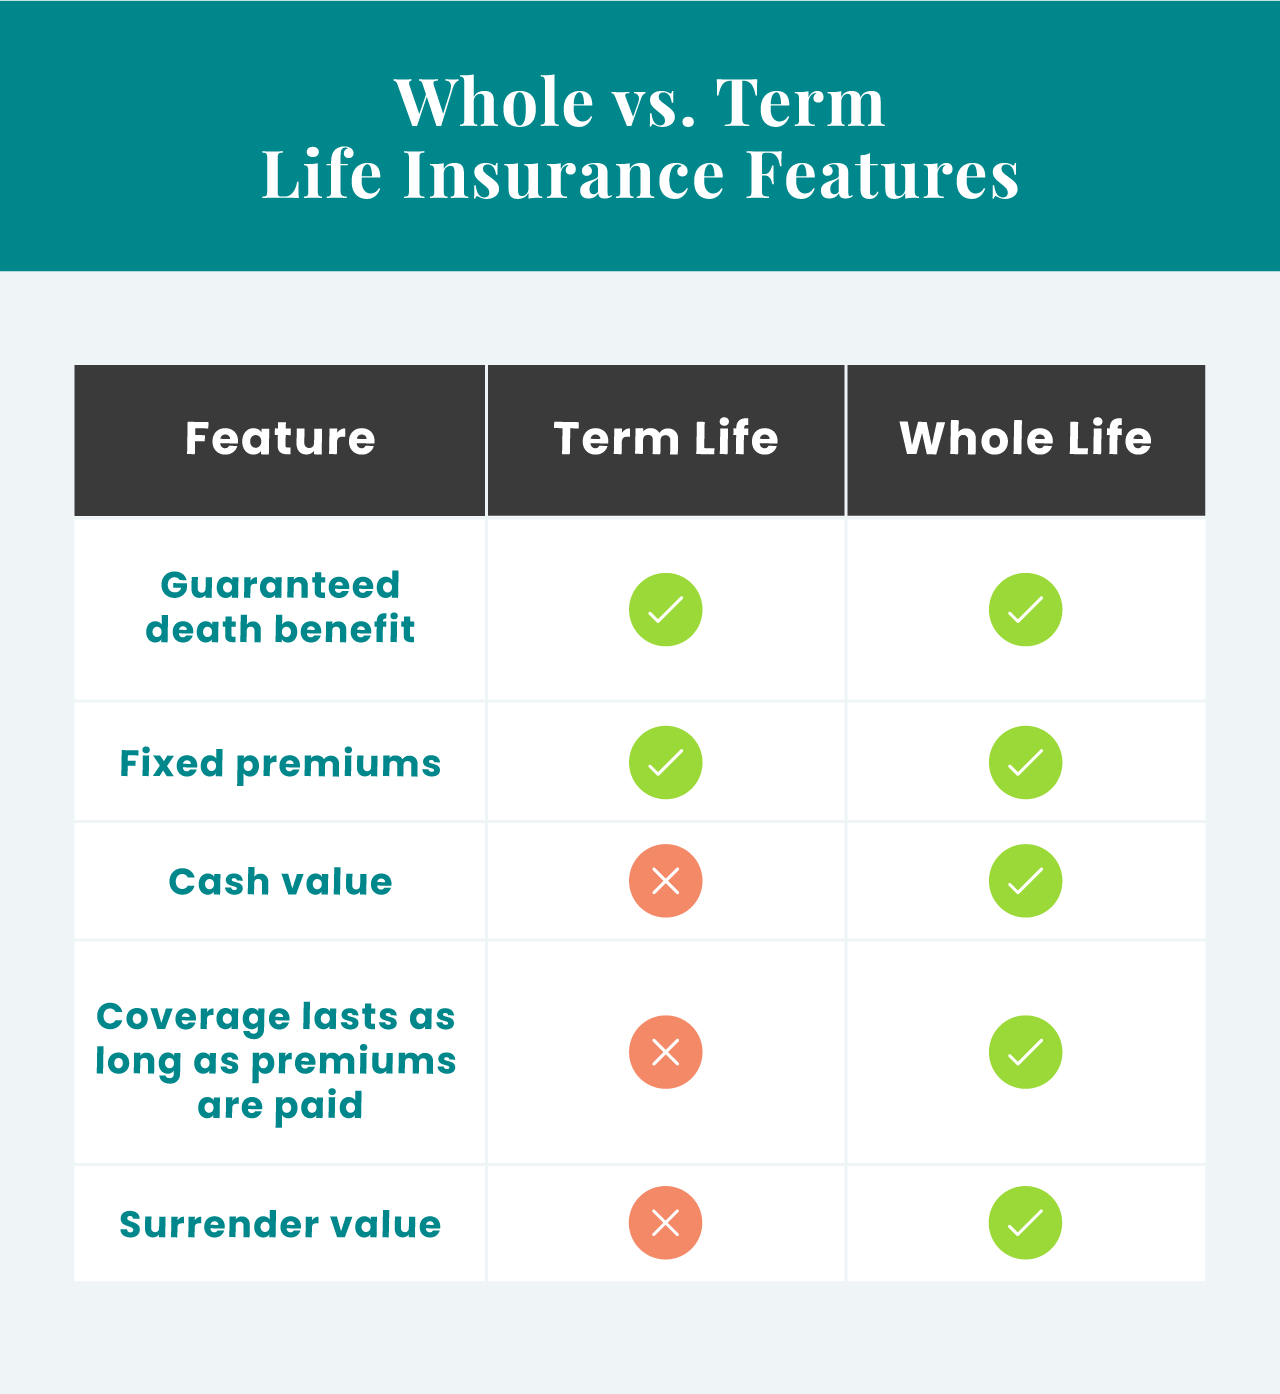
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
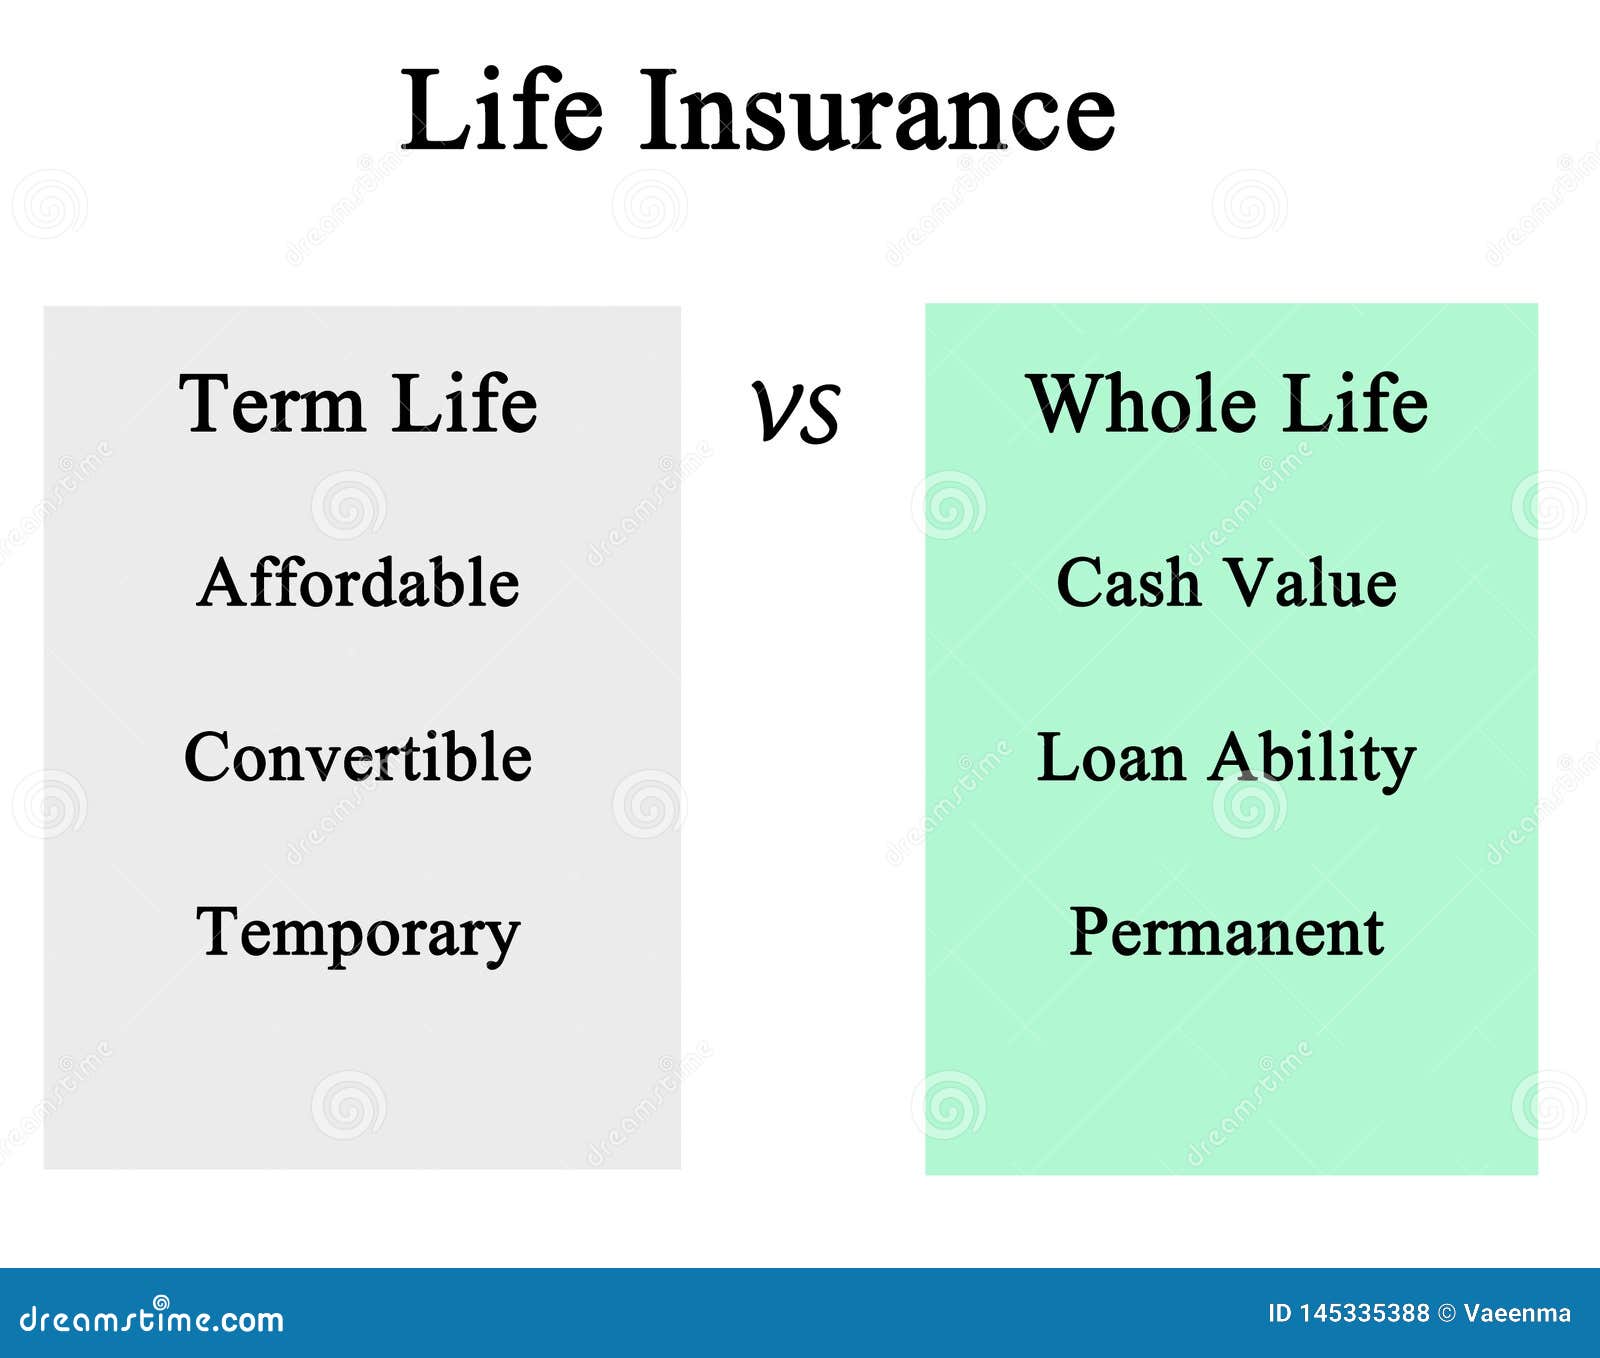
| Duration | Specific timeframe (10, 20, 30 years) | Entire lifetime of the insured |
| Cost | Low, highly affordable initial premiums | High, significantly more expensive |
| Cash Value | None (pure insurance protection) | Yes, builds tax-deferred cash value |
| Premium Stability | Level during the term; increases upon renewal | Fixed and level for your entire life |
| Purity of Purpose | Designed strictly for income replacement | Designed for lifelong coverage and savings |
| Borrowing Options | Not available | Policy loans accessible against cash value |
Key Considerations When Choosing a Policy
Selecting the right insurance product requires looking beyond marketing claims and analyzing your specific financial architecture. Consider the following criteria before making a final commitment:
1. Life Stage and Immediate Obligations
If you have young children, an active mortgage, and limited personal savings, maximizing your death benefit through term life insurance is usually the most prudent financial move. It ensures your family is protected if the unexpected happens, without absorbing capital that could be used for retirement savings or emergency funds.
2. Long-Term Estate and Tax Planning Needs
High-net-worth individuals or business owners often use whole life insurance for estate liquidity—providing heirs with cash to pay estate taxes without being forced to liquidate real estate or business assets. Additionally, individuals who have maximized traditional retirement accounts may view permanent insurance as an additional tax-advantaged asset class.
3. Budget Discipline
Proponents of the "buy term and invest the difference" strategy argue that individuals can purchase cheap term insurance and invest the price difference in higher-yielding market accounts. However, this strategy requires strict financial discipline. If you are unlikely to regularly invest the savings difference, a forced-savings mechanism like whole life insurance may offer a behavioral safeguard, ensuring some wealth is preserved over time.
Frequently Asked Questions
Can I convert a term life insurance policy into a whole life policy?
Many term life policies include a conversion rider that allows you to switch to a permanent policy without undergoing a new medical exam. This is a valuable feature if your health deteriorates during the term, though your new whole life premiums will be priced based on your attained age at the time of conversion.
Is the cash value of whole life insurance taxable?
The cash value grows on a tax-deferred basis, meaning you do not pay taxes on the internal gains as long as the policy remains active. Withdrawals up to the total amount of premiums you have paid are generally tax-free, and policy loans are also tax-free as long as the policy does not lapse.
What happens if I stop paying premiums on a whole life policy?
If you stop paying premiums, you have several non-forfeiture options. You can surrender the policy for its current cash surrender value, use the accumulated cash value to purchase a smaller paid-up permanent policy, or use extended term insurance options to maintain your current death benefit for a limited duration.
Does term life insurance pay out if you outlive the term?
No. Standard term life insurance is a pure protection product. If you survive past the expiration date of the policy, the contract terminates, and no death benefit is paid to your beneficiaries.
How much life insurance coverage do I actually need?
A standard benchmark is to secure coverage equal to 10 to 15 times your annual income, adjusted for outstanding debts, future education costs for children, and existing savings. A personalized insurance needs analysis provides a precise calculation based on your family's exact financial liabilities.
Next Actions and Recommendations
Choosing between whole life and term life insurance begins with an honest assessment of your financial liabilities, budget, and long-term wealth goals. For the vast majority of individuals, purchasing an affordable term life policy to cover peak liability years—while concurrently investing surplus funds in low-cost retirement vehicles—represents the most efficient path forward. However, if you require permanent estate planning solutions or guaranteed lifetime protection, consulting with an independent, fee-only financial planner can help you evaluate whole life products without high-pressure sales tactics. Review your current financial landscape today to determine which coverage structure best protects the people who depend on you.
Image Gallery
Select an image to open it in a new tab.




Zara El-Hashem
Sociocultural Dynamics and Academics Writer
