
A whole life insurance policy combines permanent death benefit protection with a tax-advantaged cash value accumulation component that grows on a guaranteed basis. While critics often label whole life insurance as inefficient compared to term insurance paired with stock market investments, realistic policy illustrations demonstrate that when properly structured with participating dividends and paid-up additions, whole life serves as a predictable, low-volatility financial asset.
Understanding Whole Life Insurance Mechanics: How the Policy Works
Whole life insurance is a form of permanent life insurance designed to remain in force for the insured’s entire natural life, provided premiums are paid according to the contract. Unlike term life insurance, which provides coverage for a fixed period (such as 10, 20, or 30 years) and pays out only if the insured dies during that window, whole life policy contracts guarantee a death benefit payout whenever death occurs.
To understand how whole life functions, it is essential to separate the contract into its core structural components:
Guaranteed Cash Value: A portion of each premium payment is directed into a conservative cash reserve pool managed by the insurer’s general account. The growth rate of this cash value is contractually guaranteed by the insurance carrier, insulating it from stock market volatility.
Level Premiums: Premium costs are fixed at policy inception and remain locked for life. In the early years of the policy, the premium exceeds the actual cost of insuring the individual. This excess funds the early cash value build-up and offsets the higher actuarial risk of insuring the policyholder in advanced age.
Participating Dividends: Policies issued by mutual life insurance companies (owned by policyholders rather than public shareholders) often pay non-guaranteed annual dividends. Dividend distributions represent a return of surplus profit generated by favorable mortality experience, operational efficiency, and fixed-income portfolio yield.
Paid-Up Additions (PUA) Rider: Policyholders can elect to apply dividends toward purchasing micro-policies of fully paid-up whole life insurance. Each Paid-Up Addition immediately increases both the total cash surrender value and the overall death benefit without requiring additional medical underwriting.
Annual Premium Payment
- Base Policy
- Base Death Benefit
- Guaranteed Cash Growth
- Paid-Up Additions (PUA)
- Instant Death Benefit Boost
- High Early Cash Value Growth
- Base Policy
When evaluating permanent life insurance, policyholders often compare whole life against flexible contracts such as universal life. While universal life allows flexible premium payments and adjustable coverage amounts based on prevailing market interest rates, whole life prioritizes contractual guarantees. The insurer bears all investment risk, guaranteeing that cash values will never decline as long as premiums are met.
Numerical Example: Breakdown of a Sample Whole Life Policy
To evaluate whole life insurance objectively, abstract financial theories must be replaced by concrete policy illustration data. The numerical example below illustrates a typical modern, high-early-cash-value participating whole life policy issued by a top-rated mutual insurance company.
Sample Policy Assumptions:
- Insured: 35-Year-Old Male, Preferred Non-Smoker
- Policy Structure: $500,000 Base Death Benefit with a Paid-Up Additions (PUA) Rider
- Annual Premium: $10,000 Total ($7,000 Base Premium + $3,000 PUA Rider)
- Dividend Strategy: 100% of dividends reinvested into Paid-Up Additions
- Assumed Dividend Scale Interest Rate: 5.25% (Non-guaranteed illustrative rate)
| Policy Year | Age of Insured | Cumulative Premiums Paid | Guaranteed Cash Value | Projected Cash Value (With Dividends) | Projected Total Death Benefit | Net Internal Rate of Return (IRR) on Cash Value |
|---|---|---|---|---|---|---|
| Year 1 | 36 | $10,000 | $2,800 | $3,150 | $512,000 | -68.50% |
| Year 5 | 40 | $50,000 | $35,200 | $41,800 | $548,000 | -5.88% |
| Year 10 | 45 | $100,000 | $88,500 | $108,400 | $615,000 | 1.54% |
| Year 15 | 50 | $150,000 | $146,000 | $189,200 | $702,000 | 2.98% |
| Year 20 | 55 | $200,000 | $211,000 | $298,500 | $818,000 | 3.75% |
| Year 30 | 65 | $300,000 | $362,000 | $612,000 | $1,120,000 | 4.12% |
Analysis of the Policy Illustration Data
This sample illustration highlights several critical characteristics of a properly structured whole life contract:
- The Early-Year Drag: In Years 1 through 5, the net Internal Rate of Return (IRR) on cash value is negative. This occurs because upfront policy commissions, medical underwriting costs, administrative setup fees, and premium taxes are front-loaded by the insurer.
- The Break-Even Point: Around Year 9 to Year 10, the total projected cash value exceeds the cumulative premiums paid ($108,400 accumulated versus $100,000 out-of-pocket). From this point forward, every dollar paid in premium creates more than one dollar of immediate equity.
- Compounding and Paid-Up Additions: Because dividends buy extra paid-up insurance, the death benefit expands over time—from the initial $500,000 to $1,120,000 by Age 65. Because larger death benefits require higher underlying cash reserves, cash value growth accelerates rapidly in the later decades of the contract.
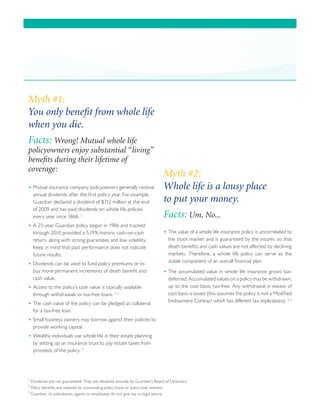
Myth 1: "The Insurance Company Keeps Your Cash Value When You Die"
One of the most widespread misconceptions in financial planning is that upon the insured’s death, the insurance company "confiscates" the accumulated cash value and pays only the original face amount of the policy.
Clarifying Cash Value vs. Death Benefit Mechanics
This myth stems from a fundamental misunderstanding of how life insurance reserves are calculated. In a standard base whole life policy, the death benefit consists of two components: the accumulated cash value reserve and the insurer's net amount at risk.
$$\text{Total Death Benefit Payout} = \text{Cash Surrender Value} + \text{Insurer Net Amount at Risk}$$
As the policy matures and the cash value grows, the insurer's net amount at risk decreases proportionally. At Age 121 (the standard maturity cap for modern actuarial tables), the cash value exactly equals the original face amount, meaning the insurer carries zero net amount at risk.
- Policy Inception (Age 35) - Total Benefit: $500,000
- Net Amount at Risk: $497,200
- Cash: $2,800
- Mature Policy (Age 65 - With Paid-Up Additions) - Total Benefit: $1,120,000
- Net Amount at Risk: $508,000
- Cash Value: $612,000
How Dividend Structures Fix the "Lost Cash" Issue
When a whole life policy uses participating dividends to purchase Paid-Up Additions (PUA), the policyholder receives both cash value growth and an expanding death benefit:
- If the insured dies in Year 20 of the policy detailed above, the beneficiary receives $818,000, not the initial $500,000 death benefit.
- The $298,500 of accumulated cash value is not retained by the insurer; it directly backed and funded the higher total death benefit payout.
Under Internal Revenue Code (IRC) Section 101(a), the full death benefit payout—including all accumulated paid-up additions—is received by beneficiaries completely income tax-free.
Myth 2: "Whole Life Insurance Is Always a Terrible Financial Product"
Critics often rely on direct performance comparisons between whole life cash value and broad equity market indexes like the S&P 500, applying a "Buy Term and Invest the Difference" (BTID) framework. While BTID is an efficient strategy for many consumers, declaring whole life universally inferior misinterprets asset allocation and risk management principles.
Evaluating Performance Across Asset Classes
Comparing whole life insurance directly to the stock market compares two entirely different asset classes with contrasting risk profiles:
- Equities (e.g., S&P 500): High historical returns (8–10% long-term average), but subject to severe short-term market volatility, sequence-of-returns risk, and annual capital gains taxes if held in taxable accounts.
- Whole Life Cash Value: Moderate historical net yields (3–5% long-term IRR), contractually guaranteed principal protection, zero downside market exposure, and tax-deferred growth.
Financial planners use whole life cash value not as a replacement for high-growth equities, but as a component of the fixed-income and liquid cash reserve tier of a portfolio.
- Growth Tier: Equities & Real Estate (High Risk / High Return potential)
- Stability Tier: Whole Life Cash Value (Guaranteed Floor / Liquid / Tax-Advantaged)
- Safety Tier: Emergency Savings & Treasuries (Nominal Yield / High Liquidity)
Strategic Use Cases for Whole Life Insurance
- Sequence-of-Returns Protection in Retirement: Retirees can draw upon their policy cash values for income during major stock market downturns, allowing equity portfolios time to recover without selling shares at depressed prices.
- Estate Planning and Wealth Transfer: High-net-worth individuals utilize permanent life insurance inside Irrevocable Life Insurance Trusts (ILITs) to pay estate taxes, settle business obligations, or balance asset inheritance among heirs.
- Asset Protection: In many legal jurisdictions, life insurance cash surrender values are protected from creditor claims, bankruptcy proceedings, and civil lawsuits under state exemption statutes.
- Non-Correlated Liquidity: Because policy cash values are backed by major life insurance carrier general accounts—which primarily hold senior long-term corporate bonds, private placements, and commercial mortgages—they maintain zero correlation with equity market panics.
Myth 3: "You Pay Taxes on Cash Value Growth and Policy Borrowing"
Taxation on life insurance policies is often misunderstood. Whole life insurance benefits from preferential tax treatment under U.S. federal tax laws, governed primarily by IRS Code Section 7702.
Tax Treatment of Growth and Withdrawals
Cash value inside a whole life policy grows on a tax-deferred basis. As long as the earnings remain inside the policy contract, no annual income tax, capital gains tax, or Form 1099 reporting is triggered.
When withdrawing cash value outright, the IRS applies a favorable First-In, First-Out (FIFO) tax framework under IRC Section 72:
- Withdrawals up to the cumulative amount of premiums paid (known as the policy's cost basis) are treated as a tax-free return of capital.
- Only withdrawals in excess of the cost basis are taxable as ordinary income.
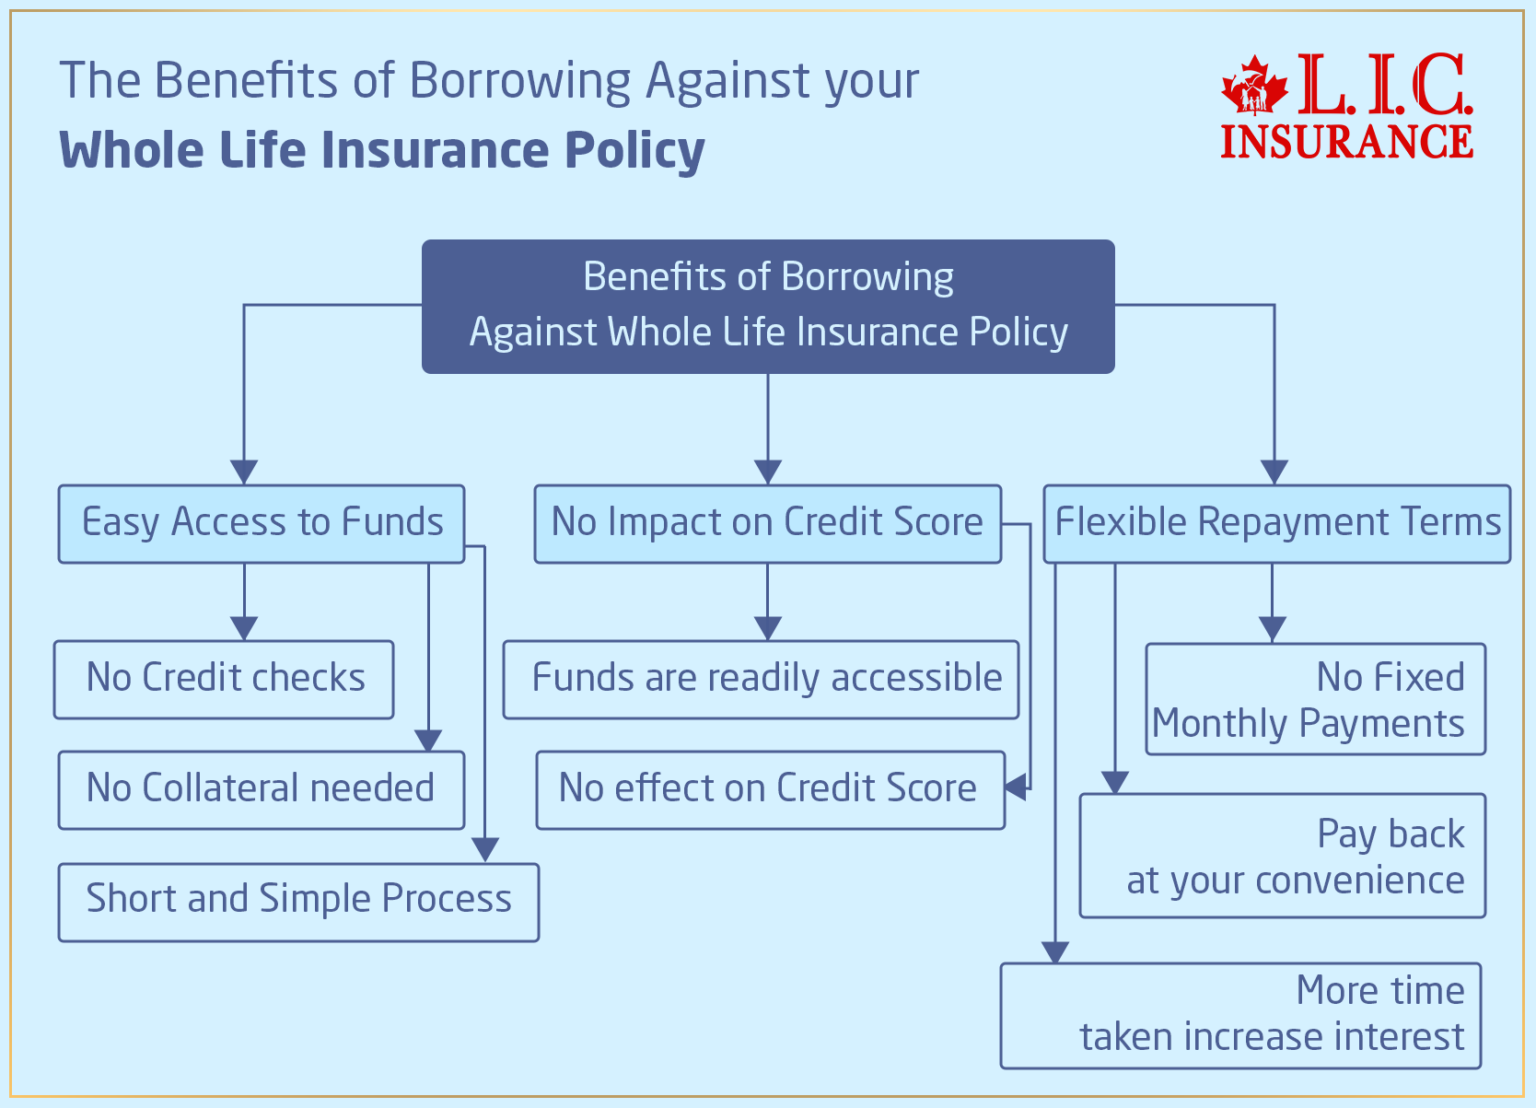
Mechanics of Policy Loans
Rather than surrendering cash value directly, policyholders can access liquidity by taking a policy loan.
- Insurance Company General Account issues a Cash Loan.
- Policyholder Account accesses liquidity.
- Cash Value Equity collateralizes the loan.
Under current tax law, policy loans are not considered taxable distributions, even if the loan amount exceeds the policyholder's paid premiums. The structural details of life insurance borrowing include:
- Collateralized Credit Line: Borrowing does not remove cash directly from the underlying policy. The insurer uses your policy cash value as collateral while issuing funds from their corporate general account.
- Continued Growth: In a direct-recognition or non-direct-recognition mutual policy, the entire cash value balance (or a substantial portion of it) can continue earning interest and dividends while the loan remains outstanding.
- Repayment Flexibility: Policy loans have no fixed repayment schedule, monthly mandatory payments, or underwriting checks. However, interest accrues annually on unpaid loan balances.
Avoid the Modified Endowment Contract (MEC) Trap
If a policyholder pays too much cash into a whole life policy too quickly, the contract breaks the IRS "7-Pay Test" defined under Section 7702A. When this happens, the contract is reclassified by the IRS as a Modified Endowment Contract (MEC).
If a policy becomes a MEC:
- Withdrawals and policy loans switch from FIFO tax rules to LIFO (Last-In, First-Out) rules, making earnings taxable immediately.
- Distributions taken prior to age $59\frac{1}{2}$ incur an additional 10% IRS tax penalty.
- Note: A MEC reclassification does not make the underlying death benefit taxable; death benefit proceeds remain tax-free under Section 101(a).
Myth 4: "Dividends Are Just a Refund of Premium Overcharges"
Opponents of whole life policies often cite legal definitions stating that life insurance dividends are technically classified by the IRS as an "unearned refund of overpaid premiums." While this tax classification is accurate, treating dividends as merely an artificial mark-up misses the financial mechanism driving mutual insurance company returns.
How Life Insurance Dividends Are Generated
Mutual life insurance carriers operate for the benefit of their participating policyholders. At the end of each fiscal year, the insurer’s board of directors reviews company performance across three core areas:
Mortality Savings: If fewer policyholders die during the year than predicted by conservative actuarial underwriting tables, the funds reserved for claim payouts remain as operational profit.
Investment Gains: Mutual insurers invest general account capital in conservative corporate debt, real estate, and fixed-income assets. When net investment returns exceed the contractually guaranteed interest rate built into the base policies, the excess yield is distributed to policyholders.
Expense Savings: Operational efficiencies and reduced administrative costs generate surplus capital that is credited back to policy accounts.
Insurer Surplus Sources
- Investment Yield
- Mortality Savings
- Expense Controls
Dividend Distribution Pool
Paid-Up Additions (PUA)
Because dividend rates reflect actual underlying carrier financial performance, top-tier mutual insurers have paid annual dividends consistently for over 150 consecutive years, spanning the Great Depression, major world wars, and modern financial crises.
Myth 5: "Whole Life Policies Offer No Flexibility"
Traditional baseline whole life contracts feature fixed premiums and fixed payment terms (such as Pay-to-Age-100). However, modern policy design offers significant customization options through policy design structures and contract riders.
Essential Whole Life Customization Options
- Blended Base/PUA Contracts: Financial advisers specializing in cash-value strategies can structure policies with a low base premium combined with a high Paid-Up Additions rider balance (such as a 40/60 or 30/70 split). This structure reduces overall agent commissions, significantly increasing early cash value accumulation and reducing the break-even period to 4–6 years.
- Limited-Pay Structures: Policyholders can select shortened premium schedules, such as 10-Pay (fully paid up in 10 years) or Pay-to-Age-65. Once the payment term ends, no further premiums are due, but the cash value and death benefit continue to compound for life.
- Accelerated Death Benefit Riders: Modern contracts often include living benefits for chronic, critical, or terminal illness. If the insured is diagnosed with a qualified condition or cannot perform two of the six Activities of Daily Living (ADLs), they can access a portion of the tax-free death benefit while still living to pay for care costs.
- Waiver of Premium Rider: If the policyholder becomes totally and permanently disabled, this rider requires the insurance company to pay all base policy premiums and PUA contributions on the policyholder's behalf for the duration of the disability.
Side-by-Side Comparison: Whole Life vs. Term Insurance vs. Universal Life
Selecting the correct life insurance policy requires evaluating features, costs, guarantees, and intended uses. The table below outlines how whole life insurance compares directly to term life and variable/indexed universal life contracts.
| Feature / Metric | Term Life Insurance | Participating Whole Life | Universal Life (IUL / VUL) |
|---|---|---|---|
| Coverage Duration | Temporary (10–30 Years) | Permanent (Lifetime) | Permanent (Lifetime if funded properly) |
| Guaranteed Cash Value | None | Contractually Guaranteed | Non-guaranteed; subject to market caps/caps & costs |
| Premium Flexibility | Fixed for policy duration | Fixed contractual obligation | Flexible (User can increase/decrease payments) |
| Downside Risk Source | Policy expiration | Carrier Insolvency (mitigated by state guarantee funds) | Insufficient market gains or rising cost of insurance (COI) |
| Underlying Assets | None | Carrier General Account (Bonds, Private Debt) | Index Options (IUL) or Sub-accounts/Equities (VUL) |
| Primary Intent | Income replacement during working years | Asset preservation, liquidity, estate planning | Flexible tax-advantaged growth potential with variable risk |
Key Takeaways and Recommended Actions Before Purchasing
Whole life insurance is a specialized financial instrument. It is not an equity investment substitute, nor is it suitable for short-term savings needs. However, for individuals seeking conservative growth, tax-advantaged access to capital, long-term asset protection, and permanent death benefit protection, a properly designed whole life contract can serve as a dependable financial buffer.
Steps to Follow Before Purchasing a Policy:
- Work with a Mutual Company: Ensure the policy is issued by a established, policyholder-owned mutual life insurance company with high financial strength ratings (A++ from A.M. Best, Aa1/AAA from Moody's and Standard & Poor's).
- Request Full Policy Illustrations: Examine both the Guaranteed and Non-Guaranteed ledger columns. Evaluate the internal rate of return (IRR) on cash value at Years 10, 20, and 30, rather than looking only at total nominal dollar amounts.
- Review the Base-to-PUA Ratio: If early cash value liquidity is your priority, ask your agent or planner to optimize the illustration with Paid-Up Additions riders rather than a 100% base policy structure.
- Confirm the MEC Limit: Verify that the planned annual premium payments stay comfortably below the IRC Section 7702A MEC line to preserve tax-free access to policy loans.
- Assess Your Long-Term Budget: Because whole life premiums are a long-term binding commitment, ensure the annual baseline premium cost is sustainable through different personal economic cycles.
Frequently Asked Questions
Is whole life insurance cash value guaranteed?
Yes. Modern whole life insurance policies include a contractually guaranteed cash value growth schedule established at policy issue. As long as policy premiums are paid, this cash value cannot decline due to market downturns or economic volatility. Non-guaranteed dividends can further increase this cash balance above the baseline guarantees.
What happens if I stop paying whole life insurance premiums?
If you stop paying premiums, the policy will not necessarily lapse immediately if sufficient cash value has accumulated. Most contracts contain non-forfeiture options: you can use your accumulated cash value to purchase a reduced paid-up policy (no further premiums required, but lower death benefit), switch to extended term coverage, or take a policy loan to automatically pay the premium. If cash value is insufficient, the policy will lapse.
How long does it take for a whole life cash value policy to break even?
In a standard whole life contract, the break-even point—where cumulative cash surrender value equals or exceeds total premiums paid—typically occurs between Years 9 and 12. However, if the policy is intentionally engineered with a high Paid-Up Additions (PUA) rider split (e.g., 30% base premium / 70% PUA), the policy can reach a break-even point as early as Year 4 to Year 6.
Can I lose money in a whole life insurance cash value account?
You cannot lose cash value due to stock market drops because whole life cash value is not directly invested in public equities. However, if you surrender or cancel the policy in the first few years (typically Years 1 through 5), the surrender value will be lower than the total premiums paid due to front-loaded policy fees and administrative costs.
How does taking out a policy loan affect the death benefit?
When you take a loan against your whole life policy, the borrowed amount plus any accrued loan interest is secured by your cash value balance. If the insured passes away while a loan is outstanding, the total outstanding loan balance (principal plus unpaid interest) is deducted directly from the gross death benefit before the balance is disbursed tax-free to beneficiaries.
Image Gallery
Select an image to open it in a new tab.



Lars Thomsen
Global Labor Markets and Economic Strategy Editor
