
The Ethos underwriting process utilizes proprietary technology and third-party data to evaluate life insurance risk instantly, often eliminating the need for medical exams. By analyzing health databases, prescription histories, and motor vehicle records via an algorithmic engine, Ethos provides immediate coverage decisions for term and whole life insurance policies.
The traditional landscape of life insurance has long been defined by "fluids and vitals"—the requirement for applicants to undergo blood draws, urinalysis, and physical measurements. However, as we move through 2026, the shift toward accelerated underwriting has matured. Ethos Life, acting as a Managing General Agent (MGA), has been at the forefront of this transformation. Understanding the ethos of their underwriting process requires a look at how data science replaces the medical examiner’s needle, and what this means for the modern consumer seeking financial security.
What is Ethos Life Insurance Underwriting?
Underwriting is the process by which an insurance company determines the level of risk an applicant poses and sets the premium accordingly. The "ethos" of the Ethos process is rooted in speed, accessibility, and data-driven accuracy. Unlike traditional carriers that may take four to eight weeks to process an application, the Ethos platform is designed to provide a "yes" or "no" answer in minutes.
The core of this system is accelerated underwriting (AU). This is not "no-underwriting"; rather, it is "invisible underwriting." The platform uses an application programming interface (API) to pull real-time data from various consumer reporting agencies. This allows the system to build a comprehensive risk profile of the applicant without requiring a manual review by a human underwriter in the majority of cases.
The Role of the Managing General Agent (MGA)
It is important to note that Ethos is not the insurance carrier that pays out the final claim; they are an MGA. They design the technology, handle the underwriting via their proprietary engine, and manage the customer experience. The actual financial risk is held by established insurance giants such as Legal & General America (Banner Life/William Penn), Ameritas Life Insurance Corp., and TruStage. This partnership allows Ethos to offer the stability of a century-old insurer with the technical agility of a 2026 fintech leader.
How the Ethos Proprietary Underwriting Engine Works
The "magic" behind the instant decision lies in the predictive modeling engine. When an applicant submits their digital form, the engine cross-references the provided answers against a massive repository of external data.
1. Medical Information Bureau (MIB) Checks
The MIB is a non-profit membership corporation that operates an information exchange on behalf of life insurance companies. When you apply for a policy through Ethos, the system queries the MIB to see if you have applied for insurance elsewhere and if any medical impairments were noted in those previous applications. This prevents "insurance shopping" where an applicant might try to hide a condition that was previously disclosed to another carrier.
2. Prescription History (Rx) Reports
One of the most powerful predictors of health is medication history. Ethos accesses databases like Milliman IntelliScript or ExamOne to view prescriptions filled over the last five to ten years. For example, if an applicant claims they do not have high blood pressure but the Rx report shows a consistent refill of Lisinopril, the underwriting engine will flag this discrepancy. Conversely, the absence of chronic disease medications allows the engine to fast-track the "Preferred" or "Preferred Plus" rating.
3. Motor Vehicle Records (MVR)
Life insurance isn't just about health; it’s about lifestyle risk. Ethos pulls MVR data to look for patterns of reckless behavior. Multiple speeding tickets, DUIs, or license suspensions indicate a higher statistical probability of accidental death. Applicants with clean driving records benefit from lower premiums, while those with significant infractions may be offered higher rates or "Simplified Issue" products instead of "Accelerated" ones.
4. Fair Credit Reporting Act (FCRA) Data
While life insurance companies do not typically look at your "credit score" in the same way a mortgage lender does, they do use insurance-specific scores. These scores look at financial stability, as there is a statistical correlation between financial responsibility and longevity. It also helps verify the applicant's identity to prevent fraud.
Traditional vs. Ethos Underwriting: A 2026 Comparison
The following table illustrates the primary differences between the traditional underwriting path and the digital-first approach employed by Ethos.
| Feature | Traditional Underwriting | Ethos Underwriting Process |
|---|---|---|
| Average Timeline | 4 to 8 weeks | Minutes to 24 hours |
| Medical Exam | Required (Blood, Urine, EKG) | Often waived for healthy individuals |
| Primary Data Source | Attending Physician Statement (APS) | Real-time API (MIB, Rx, MVR) |
| Human Involvement | High (Manual review of files) | Low (Algorithmic first-pass) |
| Coverage Limits | Virtually unlimited | Generally up to $2M - $3M (subject to age) |
| Application Method | Paper or complex digital portal | Mobile-optimized smart form |
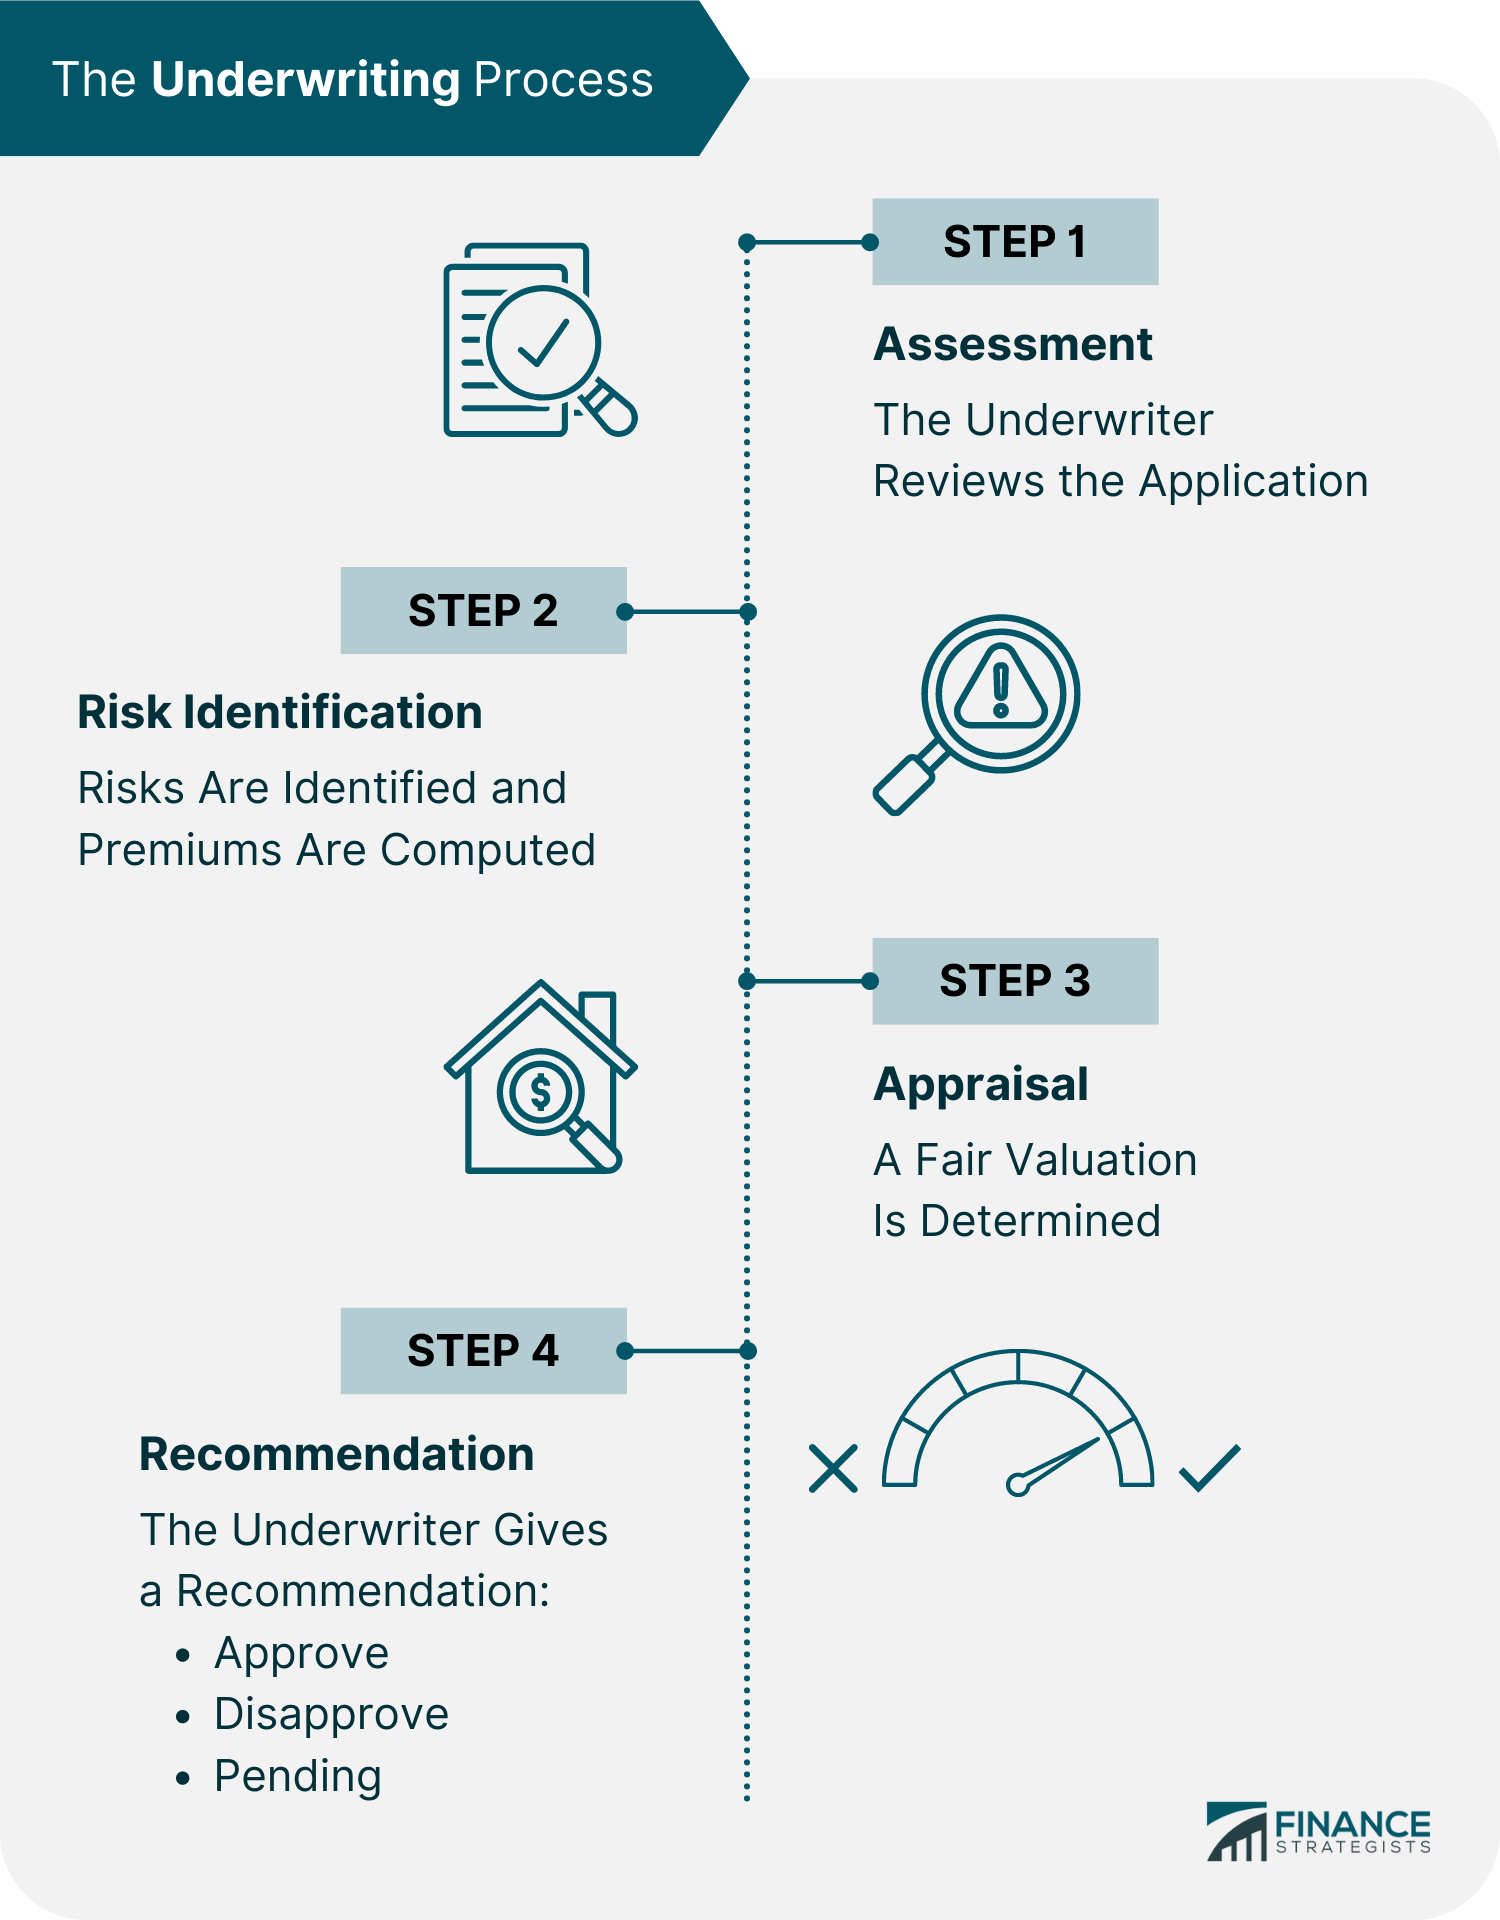
The Step-by-Step Underwriting Journey
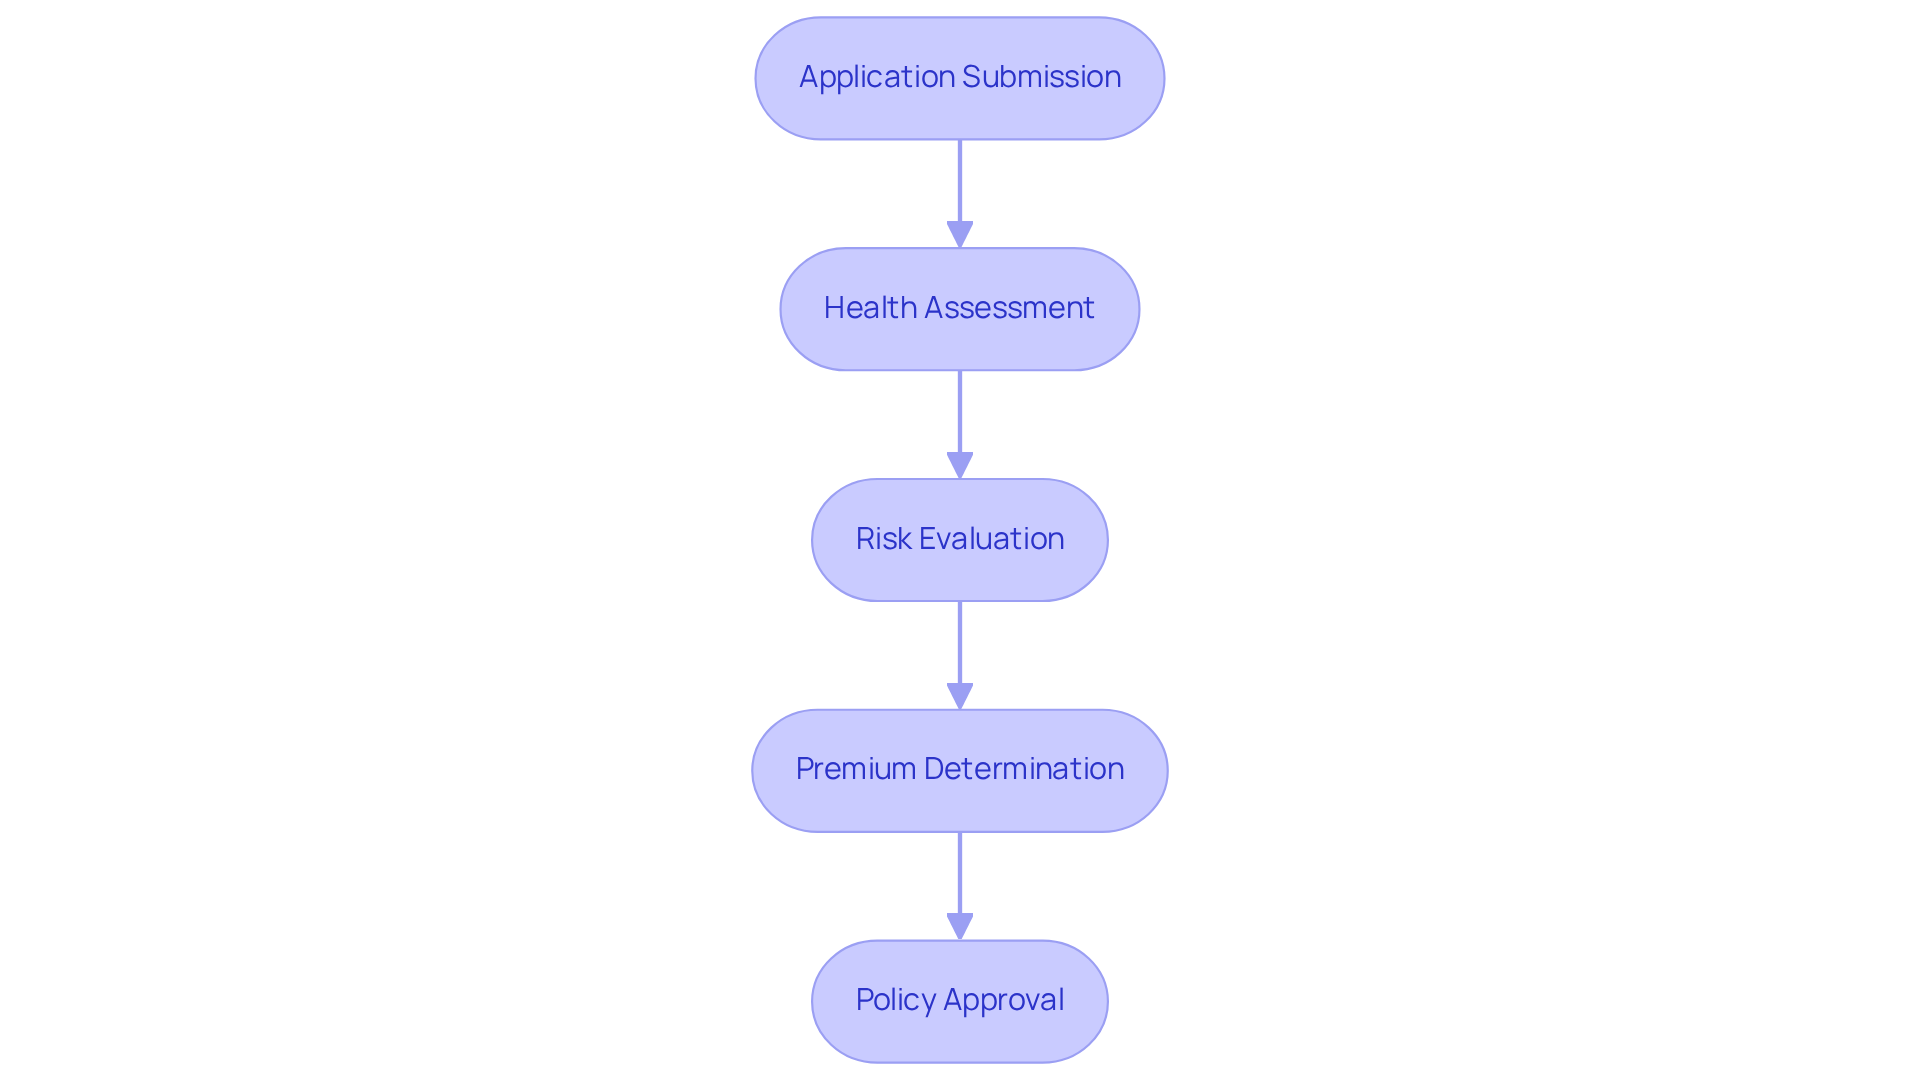
Understanding the workflow of an Ethos application helps set expectations for the applicant. In 2026, the process is streamlined into five distinct phases.
Phase 1: The Smart Application
The applicant answers a series of "reflexive" questions. This means if you answer "Yes" to a question about asthma, the system will immediately populate follow-up questions about your last attack, medications used, and hospitalizations. This ensures that the engine gathers only the relevant medical data needed for your specific situation.
Phase 2: Data Retrieval
Once the "Submit" button is clicked, the engine begins its queries. Within seconds, it has analyzed the MIB, Rx, and MVR reports. This is the stage where the majority of traditional delays are eliminated. There is no waiting for a doctor’s office to mail paper records (the infamous Attending Physician Statement).
Phase 3: The Algorithmic Decision
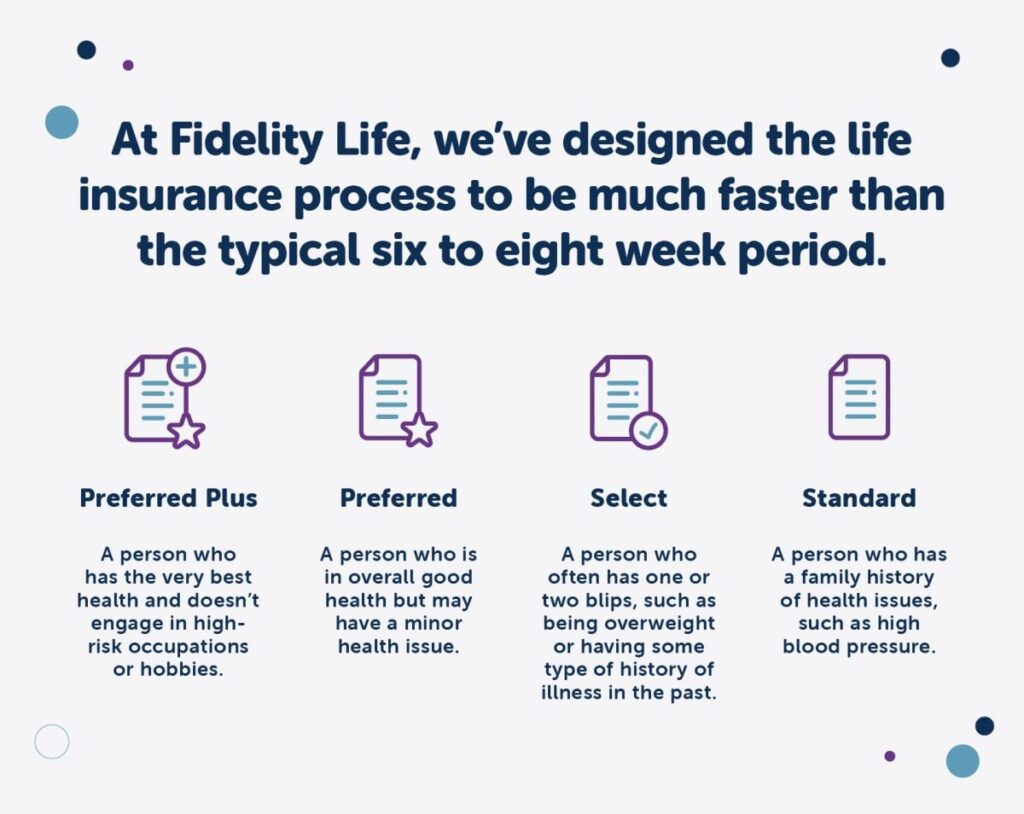
The system compares the gathered data against the underwriting guidelines of the carrier (e.g., Ameritas or Legal & General). It assigns a risk class:
- Preferred Plus: Excellent health, no tobacco, clean MVR.
- Preferred: Great health, minor issues (e.g., well-controlled cholesterol).
- Standard Plus: Good health, perhaps slightly elevated BMI.
- Standard: Average health and life expectancy.
Phase 4: Offer and Acceptance
If the applicant meets the criteria, an offer is displayed instantly. The applicant can then adjust their coverage amount and term length to see how it affects the monthly premium. Once the first payment is made, the policy is "in force."
Phase 5: Post-Issue Audit (Occasional)
To maintain the integrity of the "no-exam" model, Ethos and its carriers may perform random post-issue audits. This involves requesting medical records after the policy is active to ensure the applicant was truthful. If material misrepresentation is found, the policy could be rescinded.
Factors That Impact Your Underwriting Eligibility
While the Ethos process is designed for speed, it is not a "guaranteed approval" for everyone. Several factors can shift an applicant from the accelerated path to a manual review or a declination.
- Age and Coverage Amount: As of 2026, applicants over age 65 or those seeking more than $2 million in coverage are more likely to require traditional underwriting steps. The "limit" for instant approval varies based on the underlying carrier's current appetite for risk.
- Chronic Health Conditions: Conditions like Type 1 Diabetes, recent cancer diagnoses, or severe heart disease often cannot be underwritten purely by algorithm. These cases might be routed to a human underwriter or suggested for a "Guaranteed Issue" whole life product.
- Dangerous Hobbies: If you are a professional skydiver or engage in technical cave diving, the underwriting engine will likely flag your application. These activities represent "flat extra" risks that require manual calculation.
- Citizenship and Residency: Ethos primarily serves U.S. citizens and permanent residents (Green Card holders). Applicants on specific temporary visas may require additional documentation that slows the process.
The Pros and Cons of the Ethos Model
Advantages
- Convenience: The ability to secure a policy during a lunch break without a nurse visit is the primary draw.
- Price Transparency: Because the engine works in real-time, you see the actual price you will pay, not just an "estimate" that might change after a medical exam.
- Less Invasive: No needles and no requirement to provide a urine sample in your home or office.
Disadvantages
- Strict "Auto-Decline" Thresholds: Because there is no human to "argue" your case in the initial phase, some borderline cases that a human might approve are automatically declined by the algorithm.
- Limited Face Amounts: While $2 million is plenty for most families, high-net-worth individuals requiring $10 million+ for estate planning will still need the traditional medical exam route.
- Data Accuracy Dependencies: If there is an error in your MIB or prescription report, the engine will act on that incorrect data. Correcting these errors can be a bureaucratic challenge.
Pricing and Premium Considerations in 2026
By 2026, the cost gap between "no-exam" and "traditional" life insurance has nearly closed. In the past, you paid a significant premium for the convenience of skipping the exam. Today, because the data models used by Ethos are so predictive, the "risk premium" for accelerated underwriting is minimal.
Premiums are locked in for the duration of the term (usually 10, 15, 20, or 30 years). If you are 30 years old and in good health, the algorithmic underwriting may actually offer a lower rate than a human underwriter, as the system eliminates the administrative overhead costs associated with manual processing and medical exams.
Common Mistakes During the Underwriting Process
To ensure the "ethos" of speed is maintained, applicants should avoid these common pitfalls:
- Inconsistency: Providing an weight on the application that differs significantly from what is on file with your doctor can trigger a "manual review" flag.
- Forgetting "One-Off" Prescriptions: Even if you only took a medication for a month three years ago, it will show up in the Rx report. It is better to disclose it and explain it (e.g., "short-term anxiety medication during a divorce") than to let the engine find it.
- Undisclosed Tobacco Use: Nicotine stays in the system longer than most realize, and data from previous insurance applications or medical records can reveal tobacco use. Ethos’s engine is particularly sensitive to "non-smoker" claims that are contradicted by data.
Frequently Asked Questions
Does Ethos always skip the medical exam?
Not always. While the majority of applicants qualify for a "no-medical-exam" process, the underwriting engine may request an exam if the digital data is insufficient or if there are conflicting health indicators. This is more common for older applicants or those with complex medical histories.
How does Ethos protect my data during underwriting?
Ethos uses industry-standard encryption and complies with the Fair Credit Reporting Act (FCRA) and HIPAA regulations. They only access data relevant to the insurance risk assessment and do not sell your personal health information to third-party marketers.
Can I be denied by Ethos but approved elsewhere?
Yes. Every insurance company has its own "risk appetite." Ethos uses specific algorithms tailored to their partner carriers. If you are declined, it might be because your specific risk profile doesn't fit their automated model. A traditional carrier with manual underwriters might be able to take a more nuanced look at your situation.
Does the underwriting process check my social media?
As of 2026, most major life insurance platforms, including Ethos, do not officially use social media "scraping" as a primary underwriting tool. They rely on verified databases like the MIB, MVR, and Rx reports. However, it is always wise to ensure your public profile doesn't depict extreme, undisclosed high-risk activities.
What is the difference between "Simplified Issue" and "Accelerated" underwriting?
"Accelerated" underwriting (used for Ethos Term Life) uses data to give you the same rates as a medical-exam policy. "Simplified" underwriting (often used for Ethos Whole Life) has fewer questions and no exam but usually comes with higher premiums and lower coverage amounts because the insurer is taking on more unknown risk.
Final Recommendation
For the vast majority of healthy or "moderately healthy" individuals in 2026, the Ethos underwriting process represents the most efficient path to life insurance. To maximize your chances of instant approval, have your medical history and family health history ready before starting the application. If you have a complex medical condition that requires a "human touch" to explain, you may still find success with Ethos, but be prepared for the possibility that the system may refer you to a manual review or a different product tier. The primary goal is to be as transparent as possible; the algorithm is designed to find the truth, and honesty is the fastest way to an active policy.
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
