Understanding life insurance quotes in Tralee involves deciphering the specific financial variables that dictate your premium, such as your age, occupation, medical history, and the desired coverage amount. By comparing the cost and terms offered by Irish-regulated insurers, you can ensure that the policy you select provides adequate financial protection for your dependents or estate while remaining affordable within your long-term budget.
The Landscape of Life Insurance in Ireland
When seeking life insurance in a town like Tralee, it is important to recognize that while your physical location does not inherently change the technical cost of a policy—as insurers operate on a national basis within Ireland—local factors often influence how you access and manage these services. Life insurance is a contract between you and an insurance company where, in exchange for regular premium payments, the company provides a lump sum or income payment upon your death or, in some cases, diagnosis of a specified illness.
In the Irish market, premiums are heavily influenced by the Central Bank of Ireland’s regulatory framework, which ensures that insurers remain solvent and that policyholders receive clear information. Because life insurance is a long-term commitment, often spanning decades, understanding the quote you receive today is the first step toward avoiding under-insurance or paying for unnecessary coverage.
Decoding the Components of a Quote
When you request a quote, whether through a financial broker in Tralee or directly from a national provider, you will notice several technical terms that directly impact the bottom line. It is essential to break these down to compare "apples to apples."
1. Term vs. Whole of Life
A "Term" policy covers you for a specific duration, such as 10, 20, or 30 years. It is typically the most cost-effective option for families protecting a mortgage or children’s education. A "Whole of Life" policy covers you until death, regardless of when it occurs, provided premiums are paid; these are significantly more expensive and often function as investment vehicles as well as protection.
2. Guaranteed vs. Reviewable Premiums
A guaranteed premium remains the same for the life of the policy. A reviewable premium, while potentially cheaper at the start, allows the insurance company to reassess your risk after a set number of years, which may result in price hikes based on market conditions or changes in the insurer's claims experience.
3. Sum Assured
This is the amount paid out upon a successful claim. When analyzing a quote, ensure the sum assured is sufficient to cover your outstanding liabilities—such as a mortgage—and the lifestyle needs of your survivors. In Tralee, where housing costs can vary, matching the sum assured to your specific mortgage balance is a common starting point.
Factors That Influence Your Quoted Premium
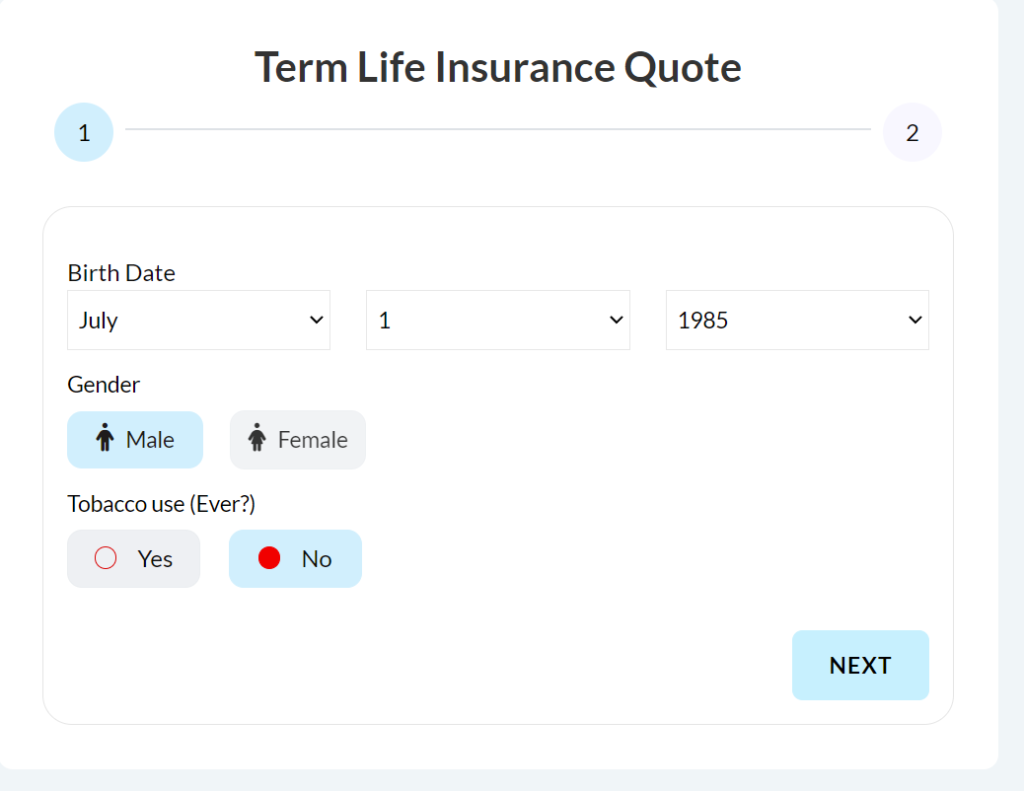
Insurance companies use actuarial science to calculate risk. When you submit your personal details, the insurer assesses several variables to determine your "risk profile."
- Age: The younger you are, the lower your premium. Because mortality risk increases with age, delaying the purchase of a policy will inevitably result in higher costs.
- Medical History: You will be required to disclose pre-existing conditions. For some, this may result in a "loading," where the premium is increased to account for higher health risks.
- Smoking Status: This is perhaps the most significant lifestyle factor. Smokers are consistently quoted higher premiums because of the statistically higher risk of health complications. Most insurers define a smoker as anyone who has used tobacco or nicotine-replacement products within the last 12 months.
- Occupation: Certain professions are considered high-risk due to safety hazards, which can lead to a higher quote or specific exclusions.
Comparing Quotes Effectively
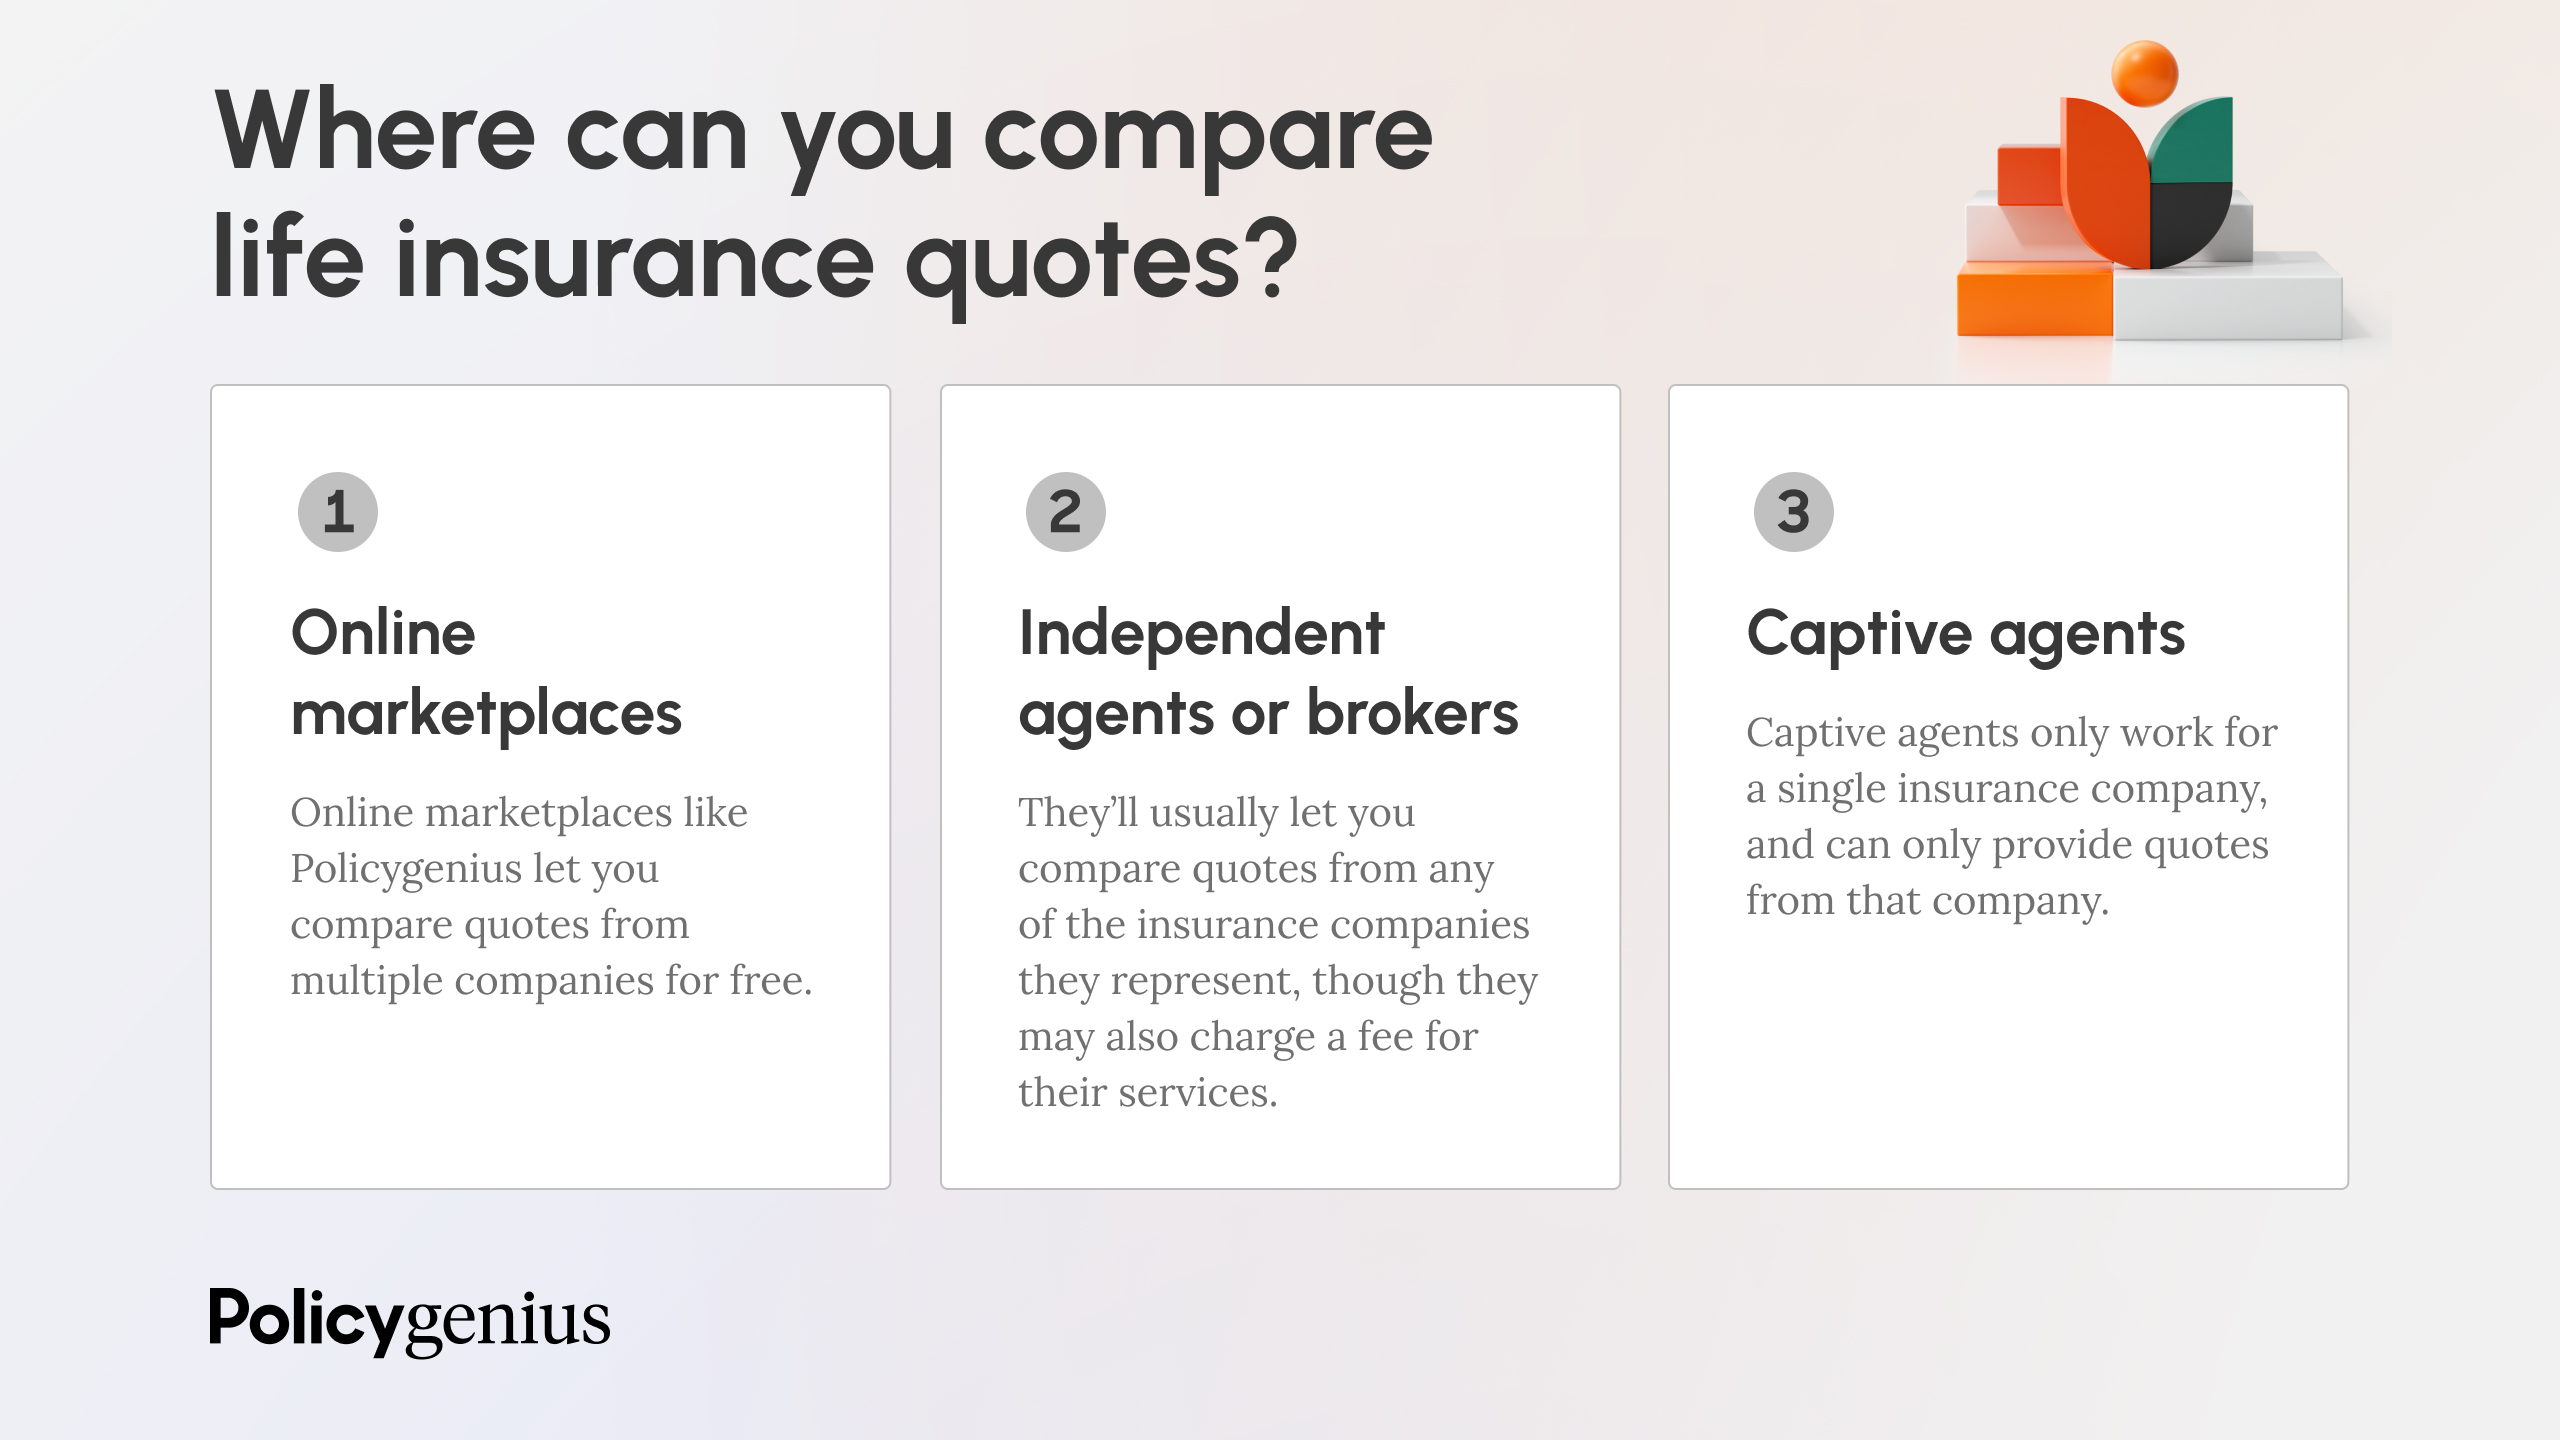
To get the best value, you should never accept the first quote you receive. Comparison is the key to transparency. In Ireland, you have the option of dealing with a broker or going direct to an insurance provider.
Table: Evaluating Life Insurance Features
| Feature | Importance | What to Look For |
|---|---|---|
| Premium Type | High | Fixed/Guaranteed vs. Reviewable |
| Conversion Option | Medium | The ability to extend your policy without medical re-underwriting |
| Indexation | Medium | Protection against inflation increasing your benefit and premium |
| Serious Illness Cover | High | Whether it is a separate policy or an "add-on" (accelerated benefit) |
| Waiver of Premium | Low | Ensures the insurer pays your premiums if you are unable to work due to disability |
The Role of Financial Brokers in Tralee
For many residents of Tralee, working with a local financial broker is a preferred route. Brokers are regulated by the Central Bank and are required to act in your best interest. They can access quotes from the entire Irish market rather than just one company, which allows them to present a broader range of pricing and coverage options.
When meeting a broker, provide them with a full picture of your financial situation. They can explain the "fine print"—the nuances of exclusions, such as suicide clauses (often limited to the first year or two) or hazardous activity exclusions (such as extreme sports).
Common Mistakes to Avoid
- Under-estimating Coverage: Many people choose the lowest monthly premium but fail to realize that the "Sum Assured" does not cover their actual debt levels. Ensure your policy covers the full duration of your mortgage.
- Omitting Medical Facts: Dishonesty on an application is a critical error. If an insurer discovers that you withheld information about a pre-existing condition, they can declare the policy void, meaning your survivors will receive nothing when the time comes.
- Ignoring Inflation: Over 20 or 30 years, inflation will erode the purchasing power of your sum assured. Look for indexation options that allow your coverage to grow in line with the Consumer Price Index.
- Failure to Review: Life changes—marriage, divorce, the birth of a child, or a mortgage top-up. A policy set up five years ago may no longer be adequate for your 2026 financial reality.
Navigating the Application Process
Once you have selected a quote that meets your needs, you will proceed to a formal application. This involves a comprehensive questionnaire about your health, lifestyle, and family medical history.
In some cases, the insurer may request a GP report. This is standard procedure for older applicants or those with specific medical histories. Be prepared for a slight delay if this is required, as the insurer will need to contact your GP surgery. If you have been living in Tralee for a long time, ensure your medical records are up to date with your current local GP, as this can expedite the underwriting process.
Understanding Exclusions
Every life insurance contract contains specific exclusions. These are circumstances under which the insurer will not pay the death benefit. Common exclusions include:
- Death caused by an undisclosed pre-existing medical condition.
- Death resulting from participation in specific hazardous activities or professions not declared at the time of application.
- Death during the first year or two of the policy (depending on the insurer’s policy regarding suicide or self-inflicted injury).
Always read the "Statement of Facts" document provided by your insurer before signing. This document summarizes all the information you provided during the application process. If any detail is incorrect, notify the insurer immediately.
Frequently Asked Questions
1. Does living in Tralee affect my life insurance premiums? No, life insurance premiums in Ireland are calculated based on personal risk factors such as age, health, and occupation rather than your town of residence.
2. Can I change my life insurance policy after I have signed it? Yes, most policies allow for modifications. You may be able to increase your cover, add riders like specified illness cover, or change the term of the policy, although this may require new underwriting and medical questions.
3. What is the difference between life insurance and mortgage protection? Mortgage protection is a specific type of life insurance designed to pay off your mortgage balance if you die. Standard life insurance (often called "term assurance") pays a lump sum to your beneficiaries, which they can use for any purpose, not just the mortgage.
4. Why is my quote higher than my friend's quote? Premiums are highly personalized. Differences in age, smoking status, occupation, and health history mean that two people will rarely receive the exact same quote, even if they choose the same insurance provider.
5. What is the "cooling-off" period? Under Irish law, you have a 30-day cooling-off period after purchasing a life insurance policy. During this time, you can cancel the policy and receive a full refund of any premiums paid, provided no claim has been made.
Next Steps for Your Coverage
If you are currently evaluating your life insurance options, begin by documenting your total debt and the financial requirements of your family. Once you have a clear figure in mind, contact at least two different providers or a local financial advisor in Tralee to request quotes based on the same coverage amount and term.
Use these quotes as a basis for comparison, paying close attention to the "Guaranteed" vs "Reviewable" premium status. Once you have chosen a policy, complete the application with full transparency. Your documentation should be stored in a secure location where your beneficiaries can easily access it should the need arise. Protecting your financial future is not a one-time event; it is a vital part of your long-term security.
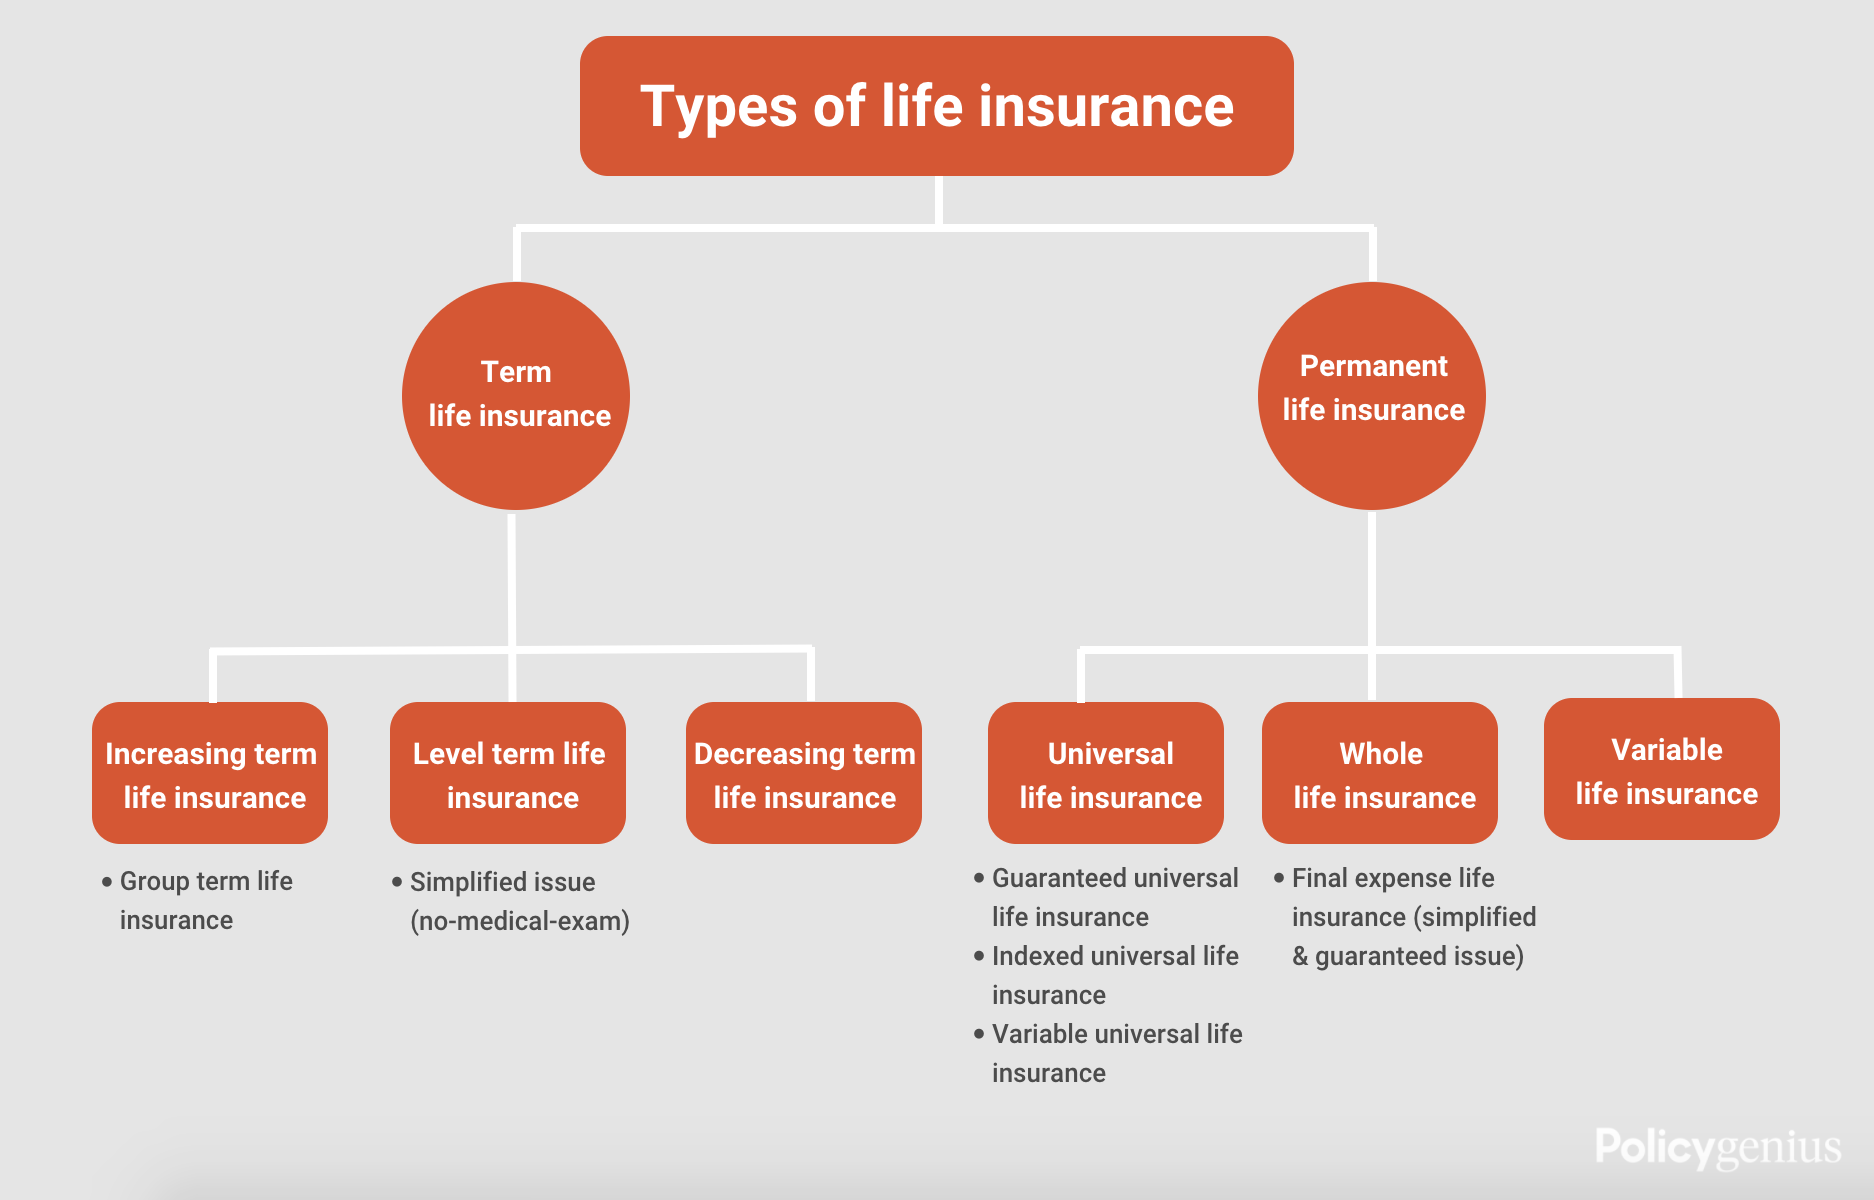
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
