As of 2026, the US robotics industry has transitioned from a specialized technological niche into the foundational pillar of domestic manufacturing and logistics. This rise is driven by a combination of aggressive reshoring policies, breakthroughs in artificial intelligence, and a critical need to address persistent labor shortages. American companies are no longer just designing software; they are building the physical systems that define the modern global economy.
The acceleration of the US robotics sector is the result of a decade-long shift in how the nation views industrial autonomy. By 2026, the integration of robotics into everyday business operations has moved beyond the automotive assembly line into small-scale fabrication, healthcare, and last-mile delivery. This growth is characterized by a move toward flexible, AI-driven systems that can operate alongside humans, marking a departure from the rigid, caged industrial robots of the past.
The Macro-Economic Catalysts for Domestic Growth
The primary engine behind the rise of the US robotics industry is the strategic "reshoring" of manufacturing. Following the supply chain vulnerabilities exposed in the early 2020s, the US government and private sector prioritized bringing production back to American soil. However, the high cost of domestic labor compared to overseas markets necessitated a massive investment in automation to maintain price competitiveness.
Federal initiatives, such as the legacy effects of the CHIPS and Science Act and subsequent 2025 manufacturing grants, provided the capital required for small and medium-sized enterprises (SMEs) to adopt robotic solutions. These policies did not just focus on hardware; they incentivized the development of "sovereign automation," ensuring that the software and control systems powering American factories are developed and secured within the United States.
Furthermore, the demographic shift of a shrinking workforce in traditional trades has left thousands of positions unfilled. In 2026, robotics is no longer viewed as a threat to employment but as a necessary supplement to a labor market that cannot meet the demands of a rebounding industrial sector.
Technological Pillars: AI, Connectivity, and Sensor Fusion
The "rise" of the industry in 2026 is technically distinct from previous iterations due to three core advancements:
1. The Integration of Large Action Models (LAMs)
While 2023 was the year of the language model, 2026 is the year of the Action Model. US-based robotics firms have successfully integrated generative AI with physical actuators. This allows robots to understand natural language commands and translate them into complex physical tasks without manual programming. For example, a warehouse robot can now be told to "clear the spill in aisle four and reorganize the damaged pallets," and it can navigate the environment and execute the task autonomously.
2. 6G and Edge Computing
The rollout of 6G infrastructure in major industrial hubs has virtually eliminated latency. This allows for "Cloud Robotics," where the heavy computational lifting is done off-board, enabling robots to be lighter, more energy-efficient, and cheaper to produce. This connectivity ensures that entire fleets of robots can share "learned" data in real-time, meaning if one robot finds a more efficient way to navigate a floor, every robot in the network instantly adopts that behavior.
3. Advanced Sensor Fusion
Modern US robotics rely on a combination of Solid-State LiDAR, high-definition computer vision, and haptic feedback. This "sensor fusion" allows robots to operate in "unstructured environments"—places like construction sites or hospital hallways—where the surroundings are constantly changing.
Key Segments of the US Robotics Market in 2026
The industry is no longer a monolith. It has branched into several high-growth sectors, each serving a specific need in the American economy.
| Segment | Primary Application | Tech Driver | Growth Status (2026) |
|---|---|---|---|
| Collaborative Robots (Cobots) | SME Manufacturing & Assembly | Force-Sensing Haptics | High Integration |
| Autonomous Mobile Robots (AMRs) | Warehouse & Logistics | SLAM Navigation | Market Maturity |
| Humanoid Robotics | General Purpose Labor | Large Action Models (LAMs) | Early Commercialization |
| Medical/Surgical Robotics | Remote & Precision Surgery | 6G Connectivity | Steady Expansion |
| Agricultural Robotics | Precision Farming & Harvesting | Multispectral Imaging | Rapid Adoption |
Collaborative Robots (Cobots)
Cobots have become the standard for American SMEs. Unlike traditional industrial robots, cobots do not require safety cages. They are designed with sensors that stop movement the moment they detect human contact. In 2026, companies like Teradyne’s Universal Robots (with heavy US-based R&D) and various Silicon Valley startups have made cobots so intuitive that a floor manager can "teach" a robot a new task by simply moving its arm through the desired motion.
The Humanoid Breakthrough
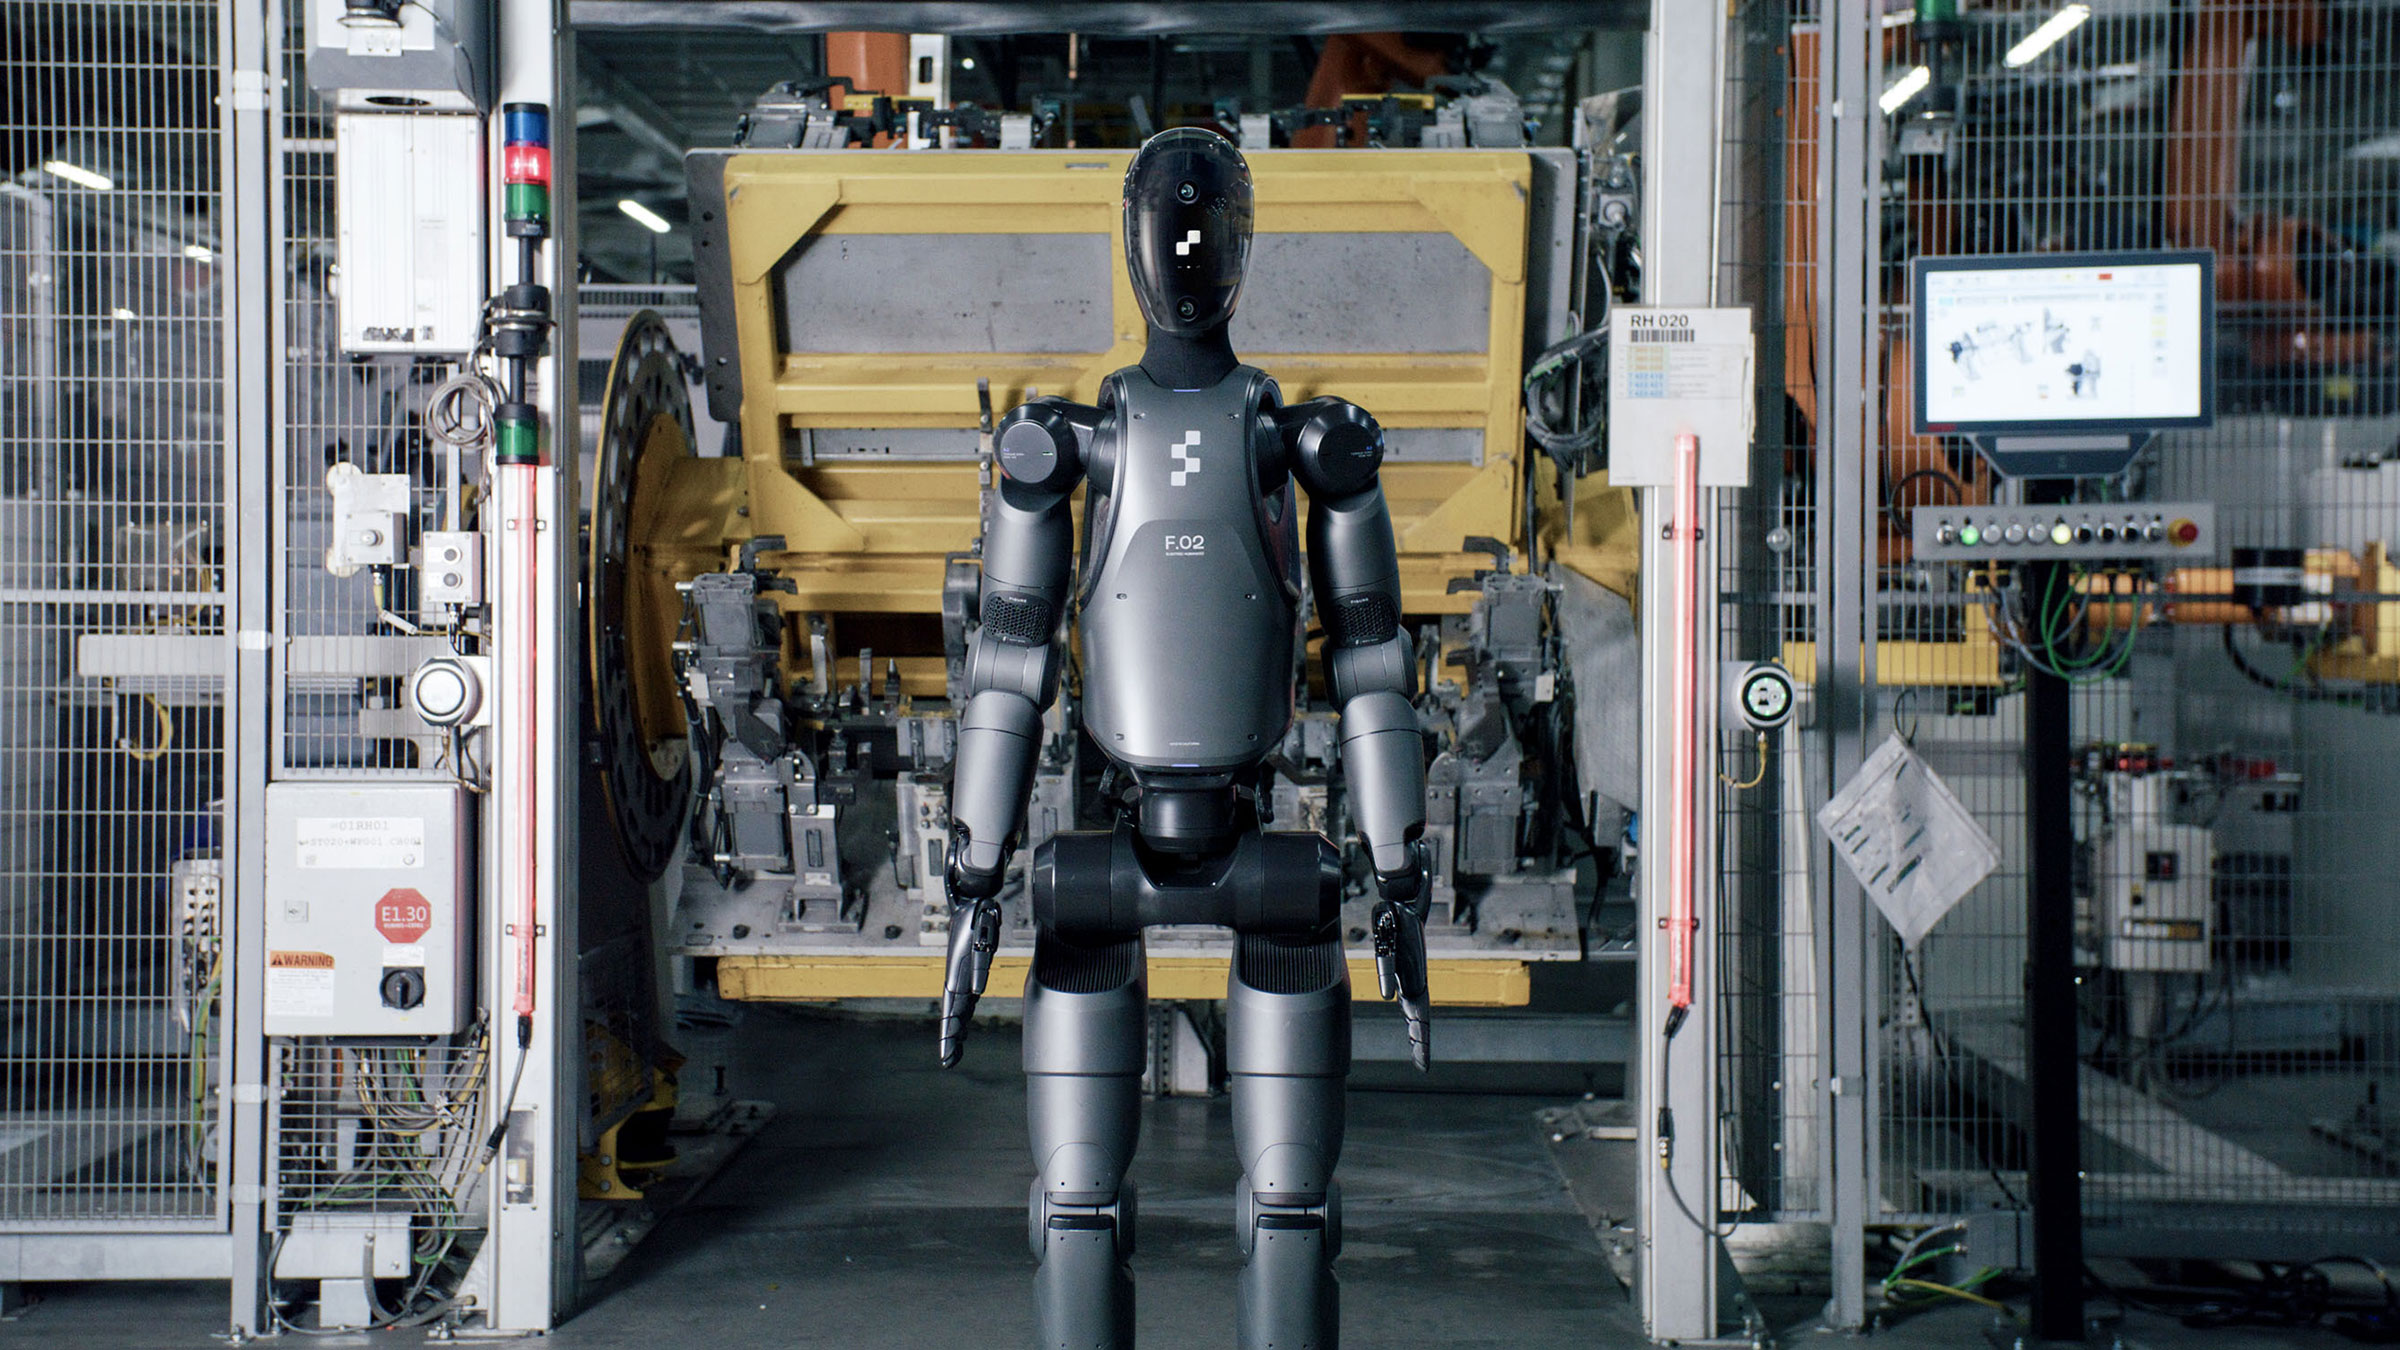
2026 marks the first year that general-purpose humanoid robots have moved from pilot programs to actual commercial deployment in the US. Companies such as Tesla (Optimus), Figure, and Boston Dynamics have begun deploying bipedal robots into "brownfield" facilities—factories designed for humans, not for robots. These machines can climb stairs, open doors, and use the same tools that human workers use, solving the problem of having to redesign entire factories to accommodate automation.
Regional Innovation Hubs: The "Robotics Belt"
The rise of the US robotics industry is geographically concentrated in several key "hubs" that facilitate a feedback loop between academia, venture capital, and industrial application.
- Pittsburgh, PA (Robotics Row): Anchored by Carnegie Mellon University, Pittsburgh has become the global center for autonomous systems and heavy-industrial automation. The city’s former steel mills now house test tracks for autonomous mining equipment and warehouse drones.
- Boston-Cambridge, MA: This region remains the leader in humanoid development and "bio-robotics." The proximity to MIT and Harvard has fostered a cluster of companies focusing on the intersection of AI and physical movement.
- Silicon Valley, CA: While Boston and Pittsburgh focus on the "body" of the robot, California remains the center for the "brain." The development of the software stacks, AI models, and computer vision systems happens here.
- The Texas Triangle: Austin and Dallas have emerged as manufacturing centers for robotics hardware, benefiting from favorable tax environments and a growing influx of engineering talent moving away from the coasts.
Challenges to Sustained Growth
Despite the rapid ascent, the US robotics industry faces significant hurdles in 2026 that require ongoing attention from both the public and private sectors.
Interoperability and Standards
As different companies deploy different robotic systems, the lack of a universal "operating system" for robotics has created silos. A robot from Company A often cannot communicate with a fleet management system from Company B. The National Institute of Standards and Technology (NIST) is currently working with industry leaders to finalize the Federal Robotics Interoperability Protocol (FRIP) to ensure that the American automated infrastructure can function as a cohesive unit.
Cybersecurity in Physical Systems
As robots become more connected, they become potential entry points for cyberattacks. A "ransomware" attack on a robotic fleet could physically halt a production line or, worse, cause the machines to operate unsafely. In response, the US has seen a surge in "Robo-Security" firms that specialize in securing the firmware and communication protocols of industrial autonomous systems.
The Skills Gap
The rise of robotics has changed the nature of work rather than eliminating it. There is a critical shortage of "Robotics Technicians"—professionals who can maintain, repair, and optimize these systems. Vocational programs and community colleges are currently undergoing a massive overhaul to include robotics literacy as a core competency.
Logistics and Robotics as a Service (RaaS)
One of the most significant business model innovations in 2026 is Robotics as a Service (RaaS). Previously, the high upfront cost (CAPEX) of a robotic system prevented small businesses from automating. With RaaS, companies can "rent" robotic labor on a subscription basis.
This model includes the hardware, software updates, and maintenance. If a robot breaks, the provider replaces it. This has lowered the barrier to entry so significantly that even local bakeries or small machine shops in rural America are now using robotic arms for packaging and sorting, contributing to the overall "rise" of the industry across all economic strata.
Frequently Asked Questions
What is the difference between a traditional industrial robot and a cobot?
Traditional industrial robots are high-speed, high-power machines that usually operate in isolation from humans for safety reasons. Cobots (collaborative robots) are equipped with advanced sensors and power-limiting technology that allow them to work safely alongside human employees in a shared workspace. In the current 2026 market, cobots are favored for their flexibility and ease of programming.
Is the US robotics industry independent of foreign supply chains?
While the US has significantly increased domestic production of semiconductors and structural components, it is not yet entirely independent. Rare earth minerals for magnets and certain specialized precision gearboxes are still largely sourced globally. However, the 2026 industrial strategy has shifted toward "friend-shoring," sourcing these critical components from vetted trade allies.
How has AI changed robotics in 2026?
AI has moved robotics from "deterministic" to "probabilistic" operation. Instead of following a rigid, pre-programmed path, robots now use AI to perceive their environment and make decisions in real-time. This allows them to handle variations in part placement, lighting, and obstacles without the system crashing or requiring a human restart.
What are the main safety regulations for robots in the US?
Safety is primarily governed by OSHA standards in conjunction with ANSI/RIA R15.06 (the American National Standard for Industrial Robots and Robot Systems). These regulations were updated in late 2025 to include specific requirements for autonomous mobile robots (AMRs) and humanoid systems operating in public or high-traffic spaces.
Does the rise of robotics mean fewer jobs for Americans?
The data in 2026 suggests a "labor shift" rather than a "labor loss." While repetitive manual tasks are being automated, there is a 30% increase in demand for roles in robotic maintenance, system integration, and supervisory management. The industry has effectively moved the American worker higher up the value chain.
Strategic Recommendation for Businesses
For organizations looking to capitalize on the rise of the US robotics industry, the most effective next step is to conduct an Automation Audit. Instead of attempting to automate an entire facility at once, identify "dull, dirty, or dangerous" tasks that currently suffer from high turnover or low efficiency.
Utilizing the Robotics as a Service (RaaS) model is recommended for an initial pilot program. This allows for the validation of ROI without a massive capital outlay. Furthermore, businesses should prioritize systems that adhere to the latest Interoperability Standards to ensure that today's investment remains compatible with the broader automated ecosystem of the late 2020s.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
