Life insurance in Myrtle Beach operates under South Carolina state regulations and federal guidelines, providing a financial safety net through term, whole, or universal policies that pay a tax-free death benefit to beneficiaries in exchange for regular premium payments.
Navigating the insurance landscape in a distinct coastal market like Myrtle Beach, South Carolina, involves understanding how regional factors, state laws, and individual financial profiles intersect. Whether you are a permanent resident living year-round along the Grand Strand or a property owner managing assets across multiple locations, securing the right policy requires looking past generic national advertisements to understand how carriers evaluate risk, underwrite applications, and pay out claims in Horry County.
Insurance functions fundamentally as a contract between an individual and an insurance company. You agree to pay a specified premium—monthly or annually—and the insurer promises to pay a designated lump sum, known as the death benefit, to your beneficiaries upon your passing. However, the practical application of this contract involves specific legal frameworks, local underwriting considerations, medical evaluations, and financial planning strategies that shift depending on whether you are looking for temporary protection or permanent cash-value accumulation.
The Core Foundations of Life Insurance Policies
To understand how life insurance works in Myrtle Beach, you must first distinguish between the two primary categories of coverage: term life insurance and permanent life insurance. Each serves a distinct purpose and functions under entirely different financial mechanics.
Term Life Insurance Mechanics
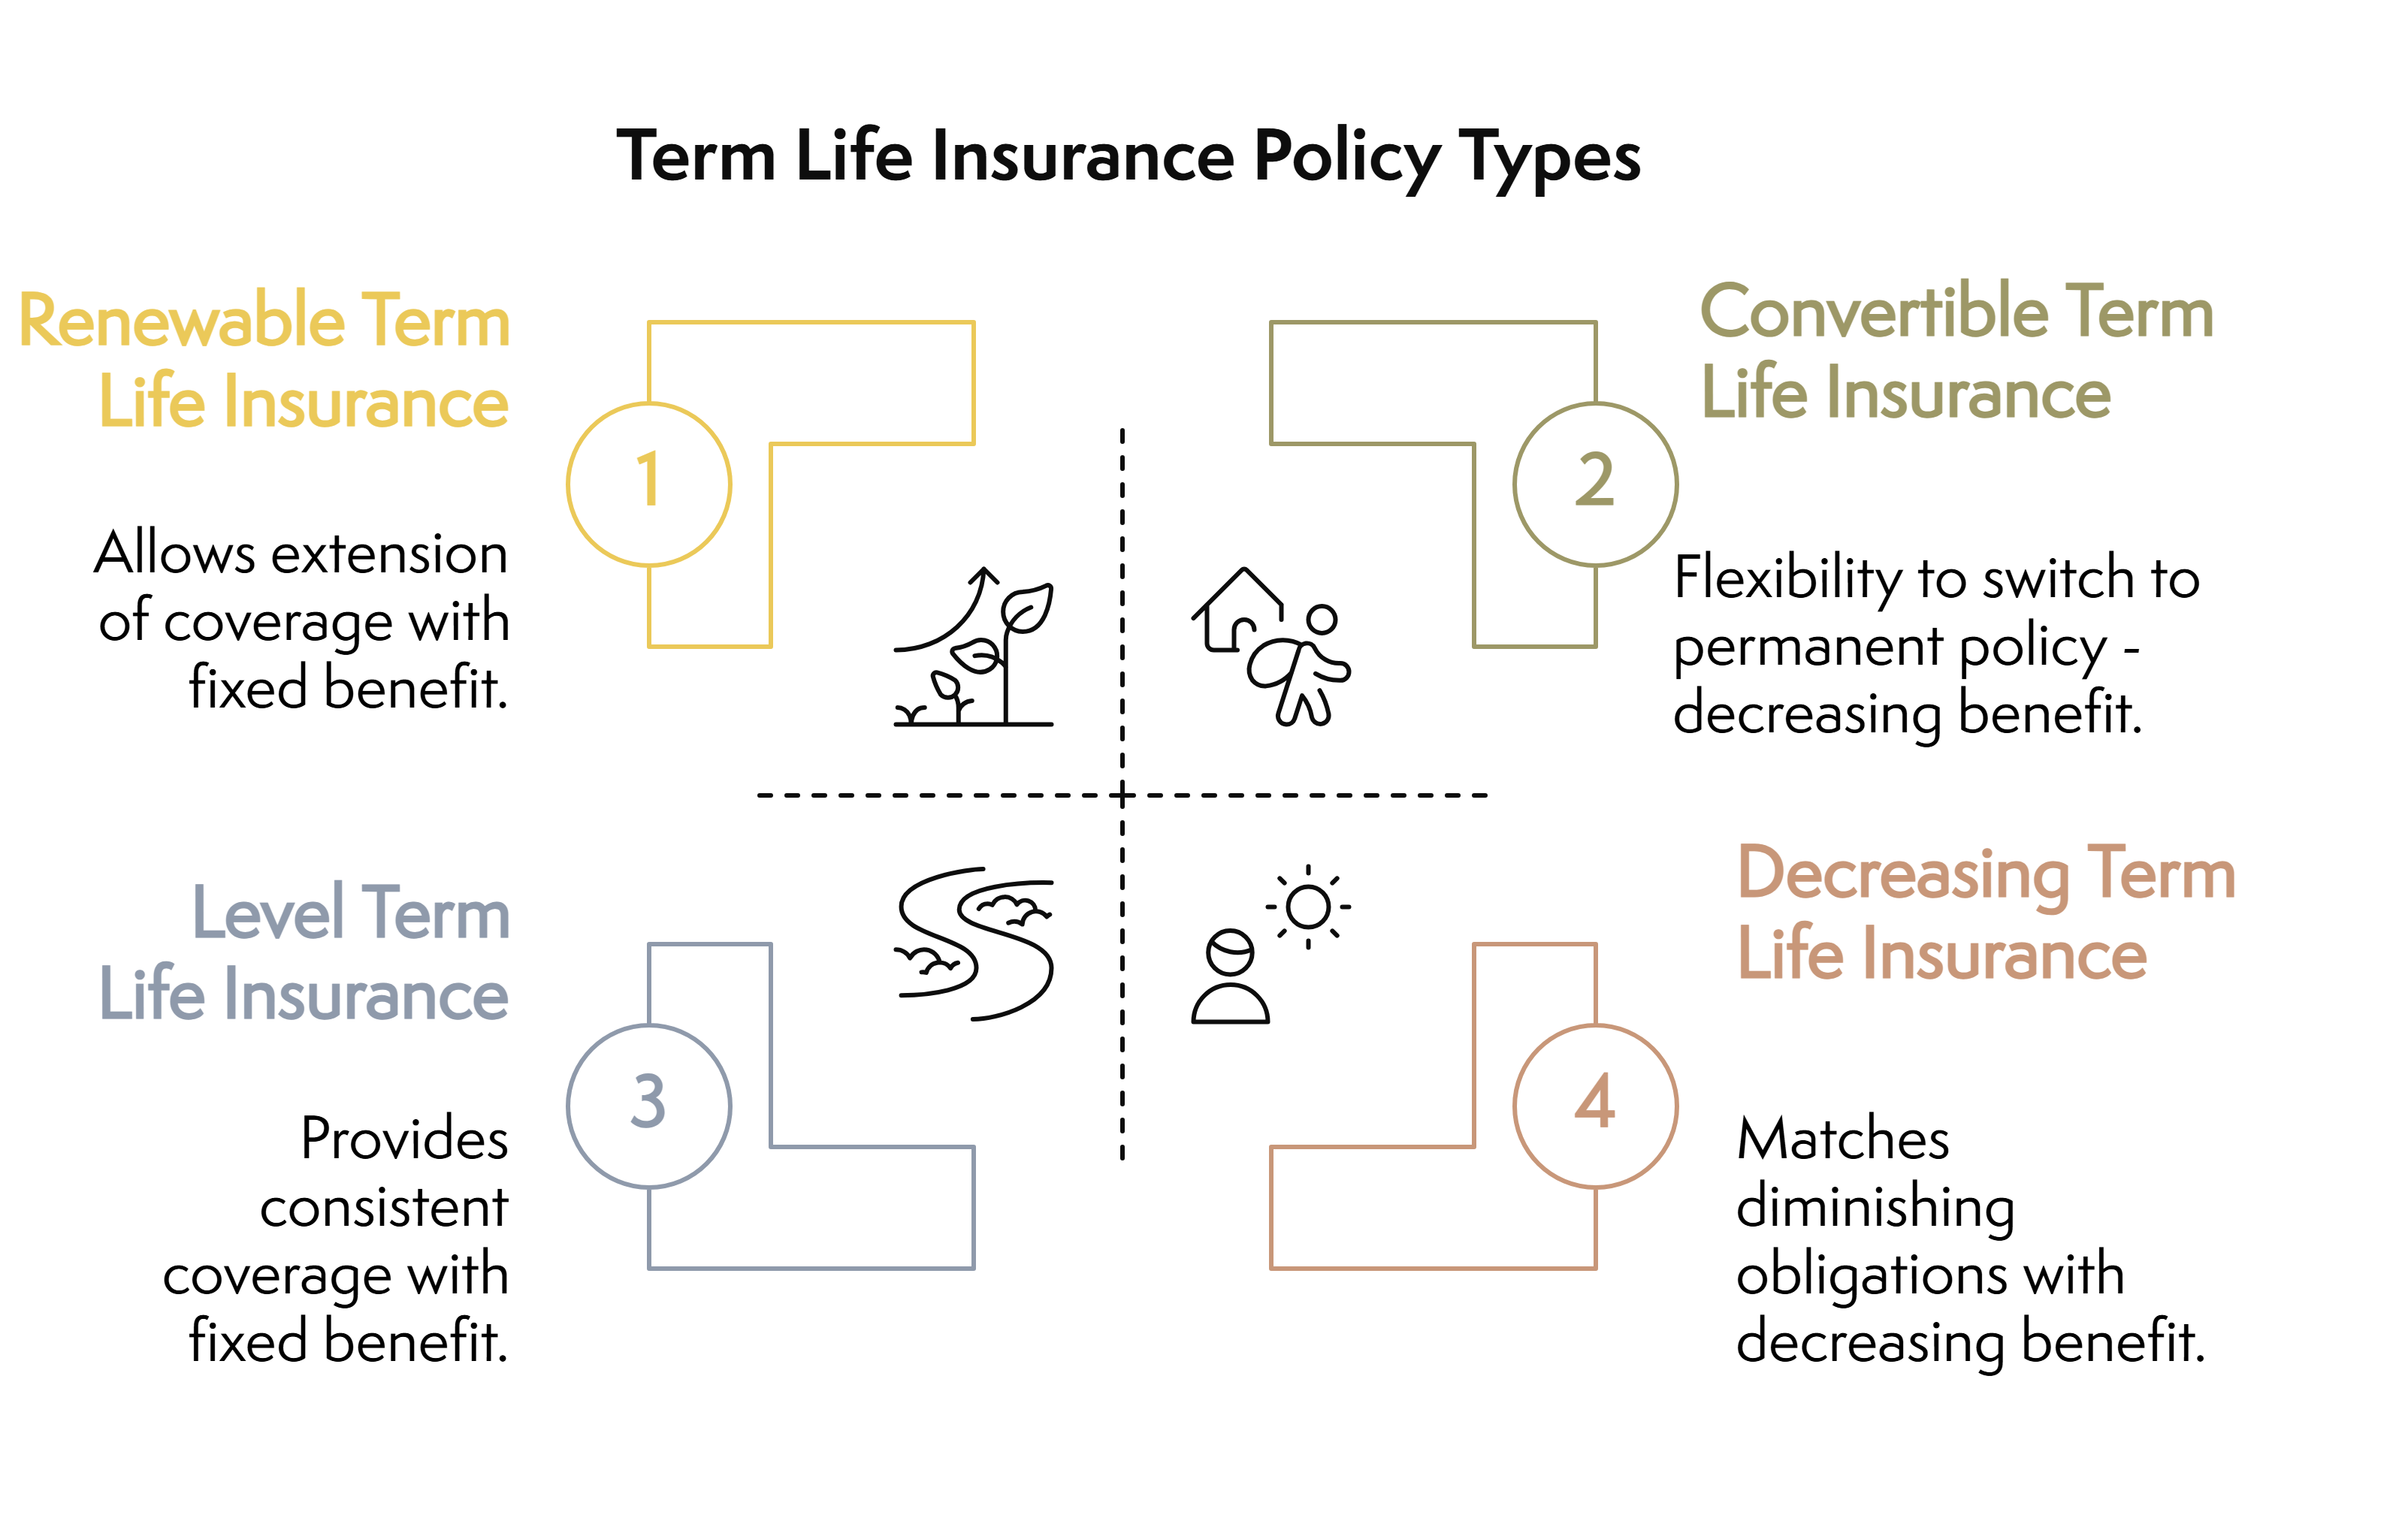
Term life insurance is designed to provide straightforward, maximum protection for a specific period, or "term," typically ranging from 10 to 30 years. It functions much like renting a home: you pay a fixed premium for the duration of the term, and if you pass away while the policy is active, your beneficiaries receive the death benefit.
- Affordability: Because term policies do not build cash value and expire at the end of the term, they offer the highest amount of coverage for the lowest initial cost.
- Convertibility: Many term policies include a rider that allows you to convert the policy into a permanent plan later in life without undergoing a new medical exam.
- Expiration Risk: If you outlive the term, the coverage ends, and no money is returned unless you purchased a specialized Return of Premium (ROP) rider.
Permanent Life Insurance Mechanics
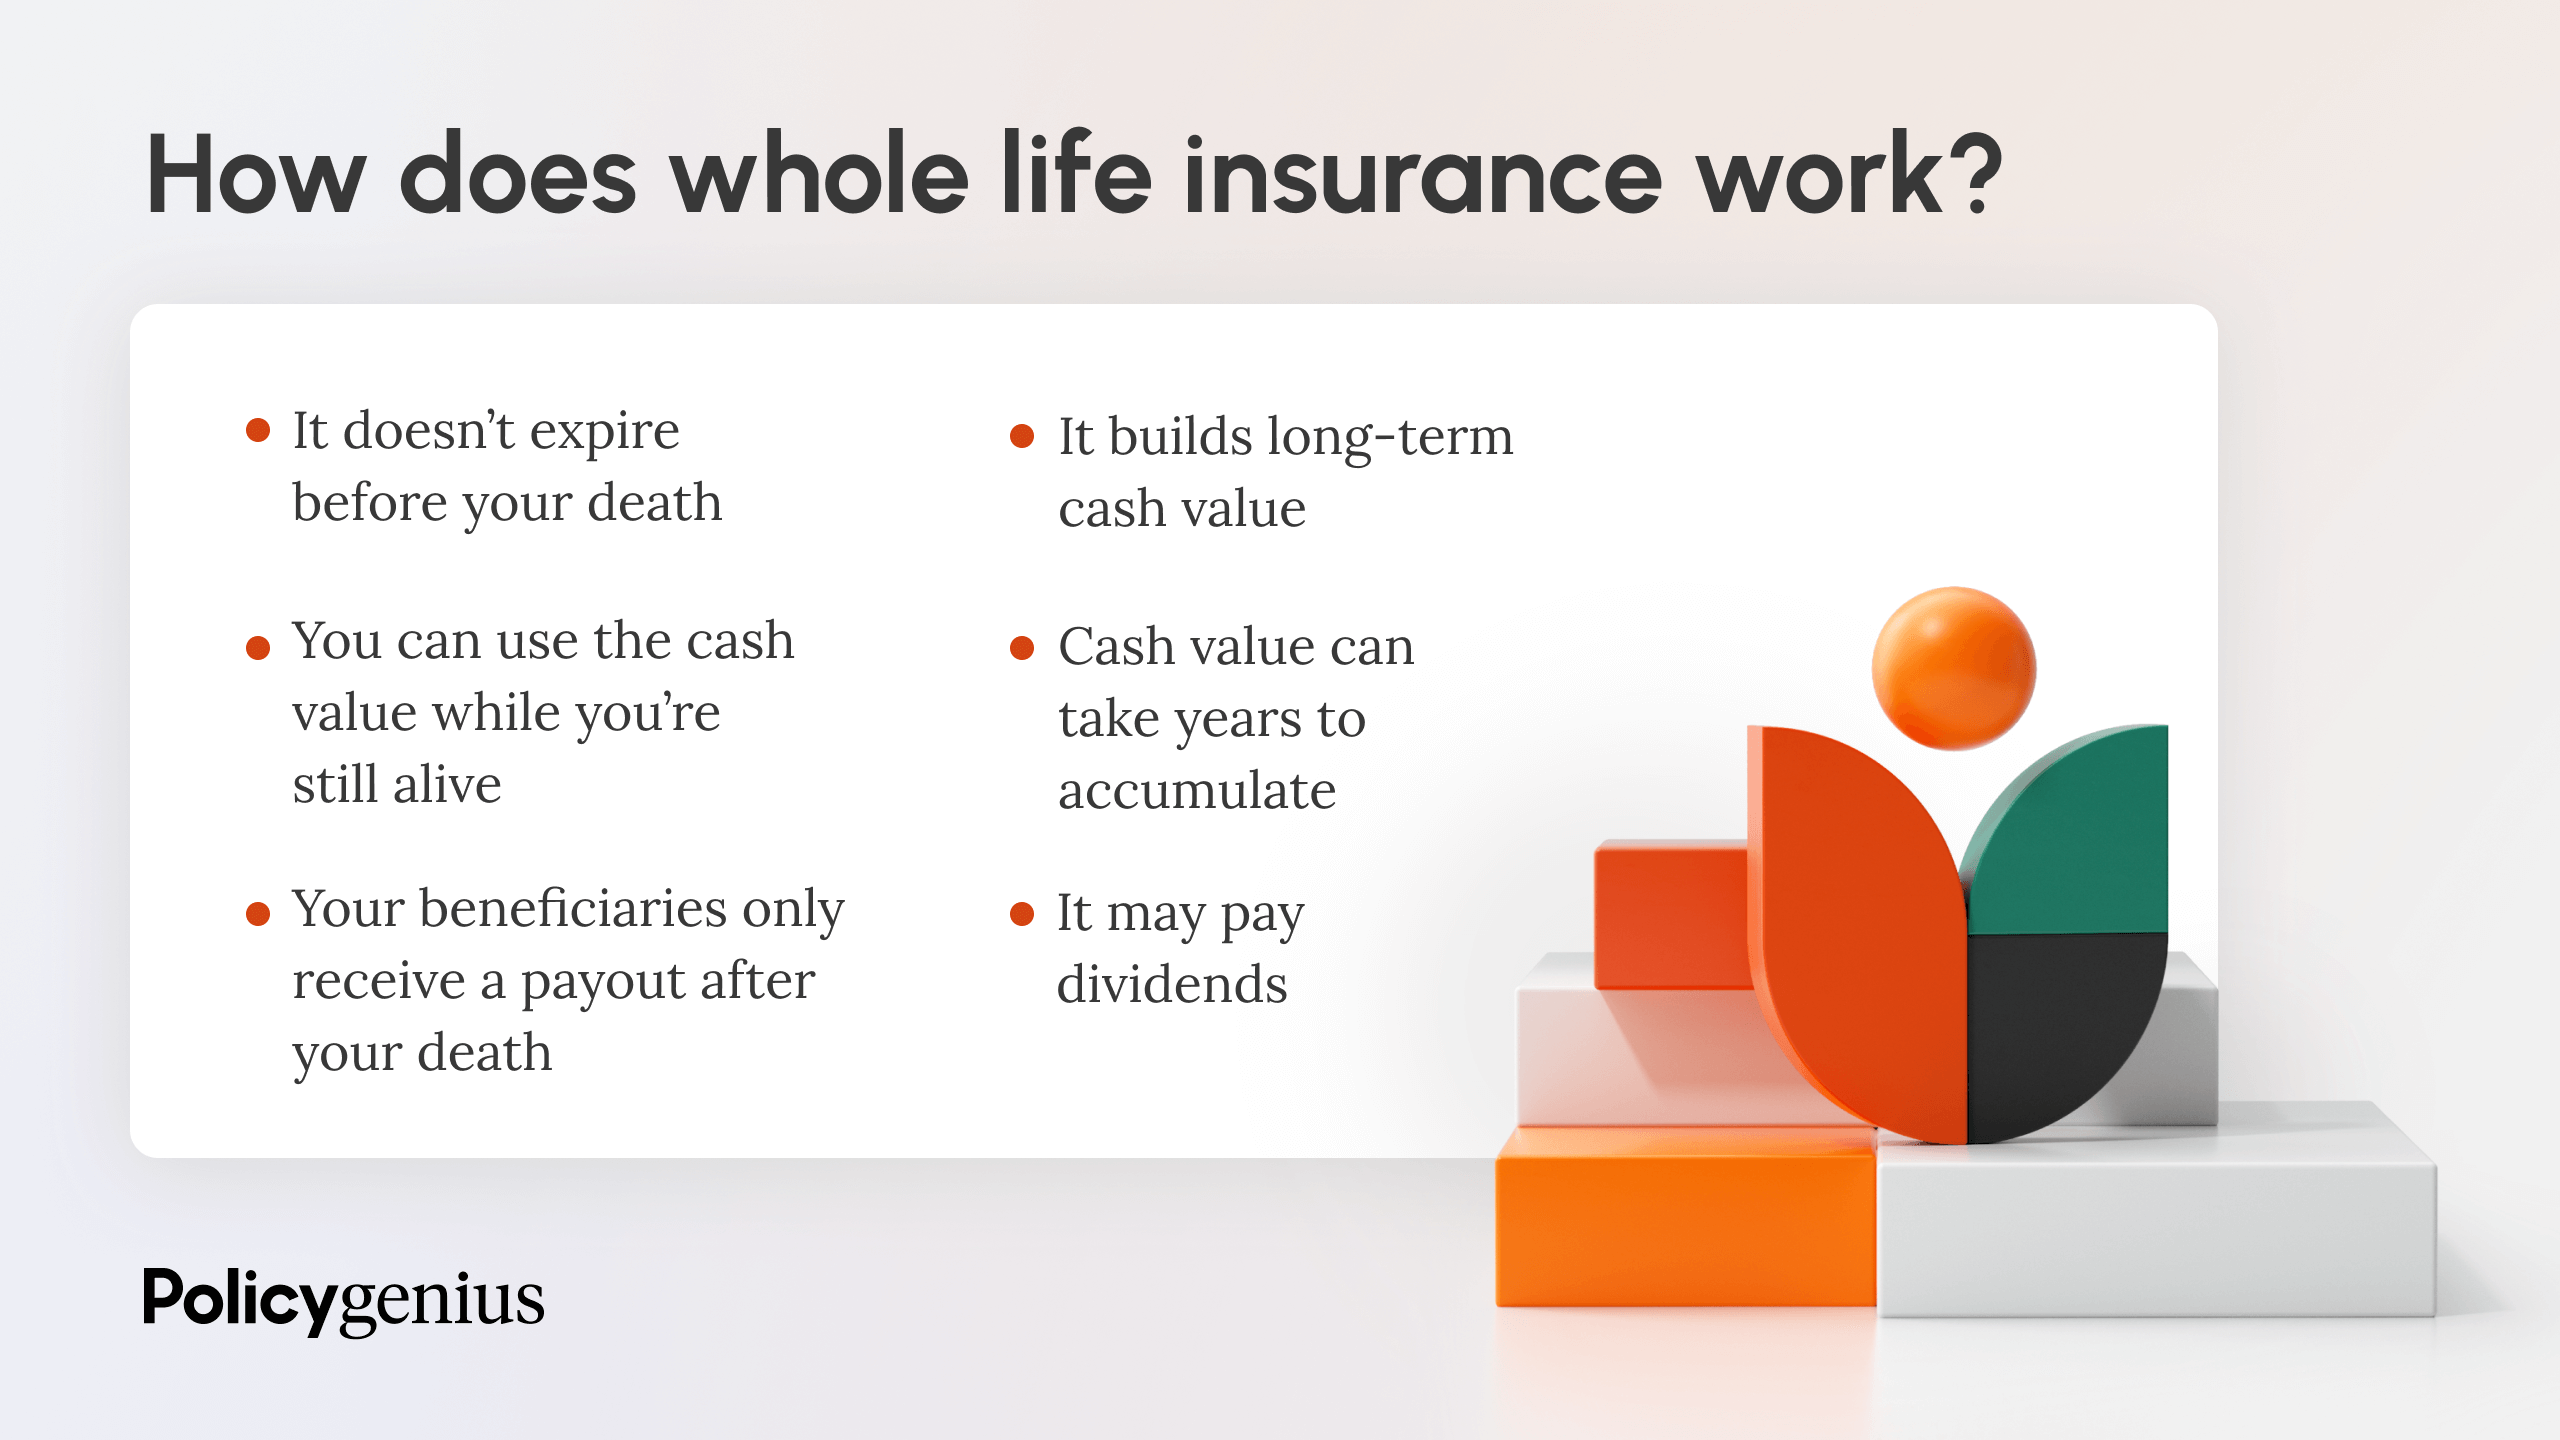
Permanent life insurance is designed to last your entire life, provided premiums are paid, and it includes an investment or savings component known as cash value. This category includes whole life and universal life insurance.
- Cash Value Accumulation: A portion of your premium payments goes into a tax-deferred cash account that grows over time. You can borrow against this cash value or withdraw from it while you are alive.
- Lifetime Protection: As long as you maintain the premium payments, the policy cannot be canceled by the insurer, and the death benefit is guaranteed.
- Higher Costs: Because of the lifetime guarantee and the cash-value accumulation, permanent policies are significantly more expensive than term policies—often 5 to 15 times the cost for the same face value.
| Policy Type | Primary Purpose | Cost Structure | Cash Value Feature | Typical Duration |
|---|---|---|---|---|
| Term Life | Temporary income replacement, debt protection | Lowest initial cost, flat rates during term | None | 10, 20, or 30 years |
| Whole Life | Lifetime security, final expenses, estate planning | Highest, fixed premiums | Guaranteed growth rate | Lifelong |
| Universal Life | Flexible permanent coverage and wealth accumulation | Adjustable premiums and death benefits | Variable growth based on market indices or interest rates | Lifelong |
South Carolina Regulations and Consumer Protections
Insurance companies operating in Myrtle Beach must be licensed by the South Carolina Department of Insurance (SCDOI). This regulatory body enforces state laws governing consumer rights, policy provisions, and insurer solvency. Understanding these regulations helps you protect your investment and ensures your policy complies with state standards.
The Free-Look Period
Under South Carolina insurance law, policyholders are granted a "free-look" period—typically 10 to 30 days depending on the specific product and carrier—starting from the date the policy is delivered. During this window, you can examine the contract, review the terms, and cancel the policy for a full refund of any premiums paid if you decide it does not meet your needs.
The Grace Period and Policy Lapses
Life insurance contracts in South Carolina include a mandated grace period, usually 31 days, following the premium due date. If a payment is missed, the policy remains in effect during this window. If the insured passes away during the grace period, the insurer will pay the death benefit minus the overdue premium. If the grace period lapses without payment, term policies terminate, while permanent policies may utilize their cash value to automatically keep the insurance active through non-forfeiture options.
The Guaranty Association
The South Carolina Life and Health Insurance Guaranty Association provides a safety net for policyholders if an insurance company becomes insolvent. While insurance companies are heavily reserved and regulated, this association steps in to protect resident policyholders up to statutory limits for life insurance death benefits and cash values, ensuring that your contract remains honored even if your specific provider encounters financial failure.

The Underwriting and Application Process
When you apply for life insurance in Myrtle Beach, the insurance carrier goes through an underwriting process to evaluate your risk profile and determine your premium rate. This process involves several distinct phases:
- Needs Analysis and Quote Generation: You work with an agent or broker to calculate how much coverage you need based on your income, mortgage, debts, and family size.
- Formal Application: You complete a detailed health and lifestyle questionnaire covering your medical history, occupation, hobbies, and travel habits.
- Paramedical Exam: For most policies, a nurse will visit your home or office in Myrtle Beach to collect vital statistics, including height, weight, blood pressure, and samples of blood and urine.
- Medical Information Bureau (MIB) and Prescription Check: Underwriters review your historical medical data through secure databases to verify your disclosed health history.
- Offer and Issuance: The carrier assigns a risk classification—such as Preferred Plus, Standard, or Substandard—and issues a final policy offer.
Regional Underwriting Factors in Myrtle Beach
While national underwriting guidelines apply, regional lifestyle elements can occasionally influence your application. Insurance carriers evaluate risks associated with coastal living, such as occupational hazards related to tourism, marine industries, or construction trades common along the Grand Strand. Furthermore, personal habits such as tobacco use, driving records, and participation in high-risk recreational activities like boating, aviation, or scuba diving are closely scrutinized during risk assessment.
Determining How Much Coverage You Need
A common mistake when buying life insurance is guessing a random coverage amount, such as a flat million dollars, without aligning it with actual financial obligations. To calculate your precise needs in Myrtle Beach, financial professionals often recommend using established frameworks like the DIME method or a comprehensive capital retention approach.
The DIME Formula
- Debt: Total all unsecured debts, including credit cards, personal loans, and auto loans.
- Income: Multiply your annual salary by the number of years your family would need financial support in your absence.
- Mortgage: Include the full remaining balance of your home loan. For Myrtle Beach homeowners dealing with local real estate values, this is often the single largest line item.
- Education: Estimate future college tuition costs for children or dependents.
By summing these four categories and subtracting existing liquid assets and current life insurance policies, you arrive at a realistic baseline figure for your death benefit.
Common Mistakes to Avoid
Navigating the life insurance market successfully requires avoiding several persistent pitfalls that can lead to inadequate coverage, wasted money, or denied claims.
- Underestimating Coverage Duration: Choosing a 10-year term when you have toddlers and a 30-year mortgage leaves your family vulnerable when the policy expires. Match your term length to your longest financial obligation.
- Waiting Too Long to Buy: Insurance rates increase with every passing year of age and as health conditions develop. Locking in a policy earlier in life secures significantly lower rates.
- Failing to Disclose Medical History: Omitting pre-existing conditions or tobacco use on your application can give the insurer grounds to contest or deny the death benefit during the contestability period—typically the first two years of the policy.
- Ignoring Inflation: Failing to account for inflation means a fixed death benefit purchased today may have significantly less purchasing power decades from now.
Frequently Asked Questions
Do I need a medical exam to get life insurance in Myrtle Beach?
Not always. While traditional fully underwritten policies require a physical exam and lab work, many carriers now offer accelerated underwriting or simplified issue policies. These options rely on digital databases, prescription histories, and medical records to approve coverage without a physical exam, though they may carry higher premiums or lower maximum coverage limits.
How does the contestability period work in South Carolina?
Under South Carolina insurance law, life insurance policies typically include a two-year contestability period. During the first two years after a policy is issued, the insurance company has the legal right to investigate the statements made on your application. If they discover material misrepresentations or fraud, they can rescind the policy or deny a claim. After two years, the policy becomes incontestable except for non-payment of premiums.
Are life insurance death benefits taxable in South Carolina?
Generally, life insurance death benefits paid to a designated beneficiary are exempt from federal income tax and South Carolina state income tax. However, if the policy is owned by the insured and their estate is the named beneficiary—or if the estate becomes the default beneficiary due to failing to name a living person—the proceeds may be subject to probate and potential estate taxes.
Can I own multiple life insurance policies?
Yes. You can purchase as many life insurance policies as you financially qualify for, provided you disclose existing coverage during the application process. Many individuals use a combination of a permanent policy for lifelong final expenses and a term policy to cover temporary mortgage and income-replacement needs.
What happens if I miss a life insurance premium payment?
If you miss a payment, insurers provide a grace period—usually 31 days—during which the policy remains active. If you fail to pay before the grace period ends, term policies will lapse and terminate. Permanent policies will often use accumulated cash value to pay the premium automatically through an automatic premium loan provision, preventing an immediate lapse as long as sufficient cash value exists.
Next Steps for Securing Coverage
Evaluating your life insurance needs starts with auditing your current financial obligations, assets, and long-term goals. If you live or work in Myrtle Beach, consult with an independent insurance broker or financial planner who is licensed in South Carolina and represents multiple insurance carriers. An independent professional can shop the market on your behalf, compare rates across top-rated companies, and help you structure a policy that provides robust protection tailored to your specific financial situation.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
