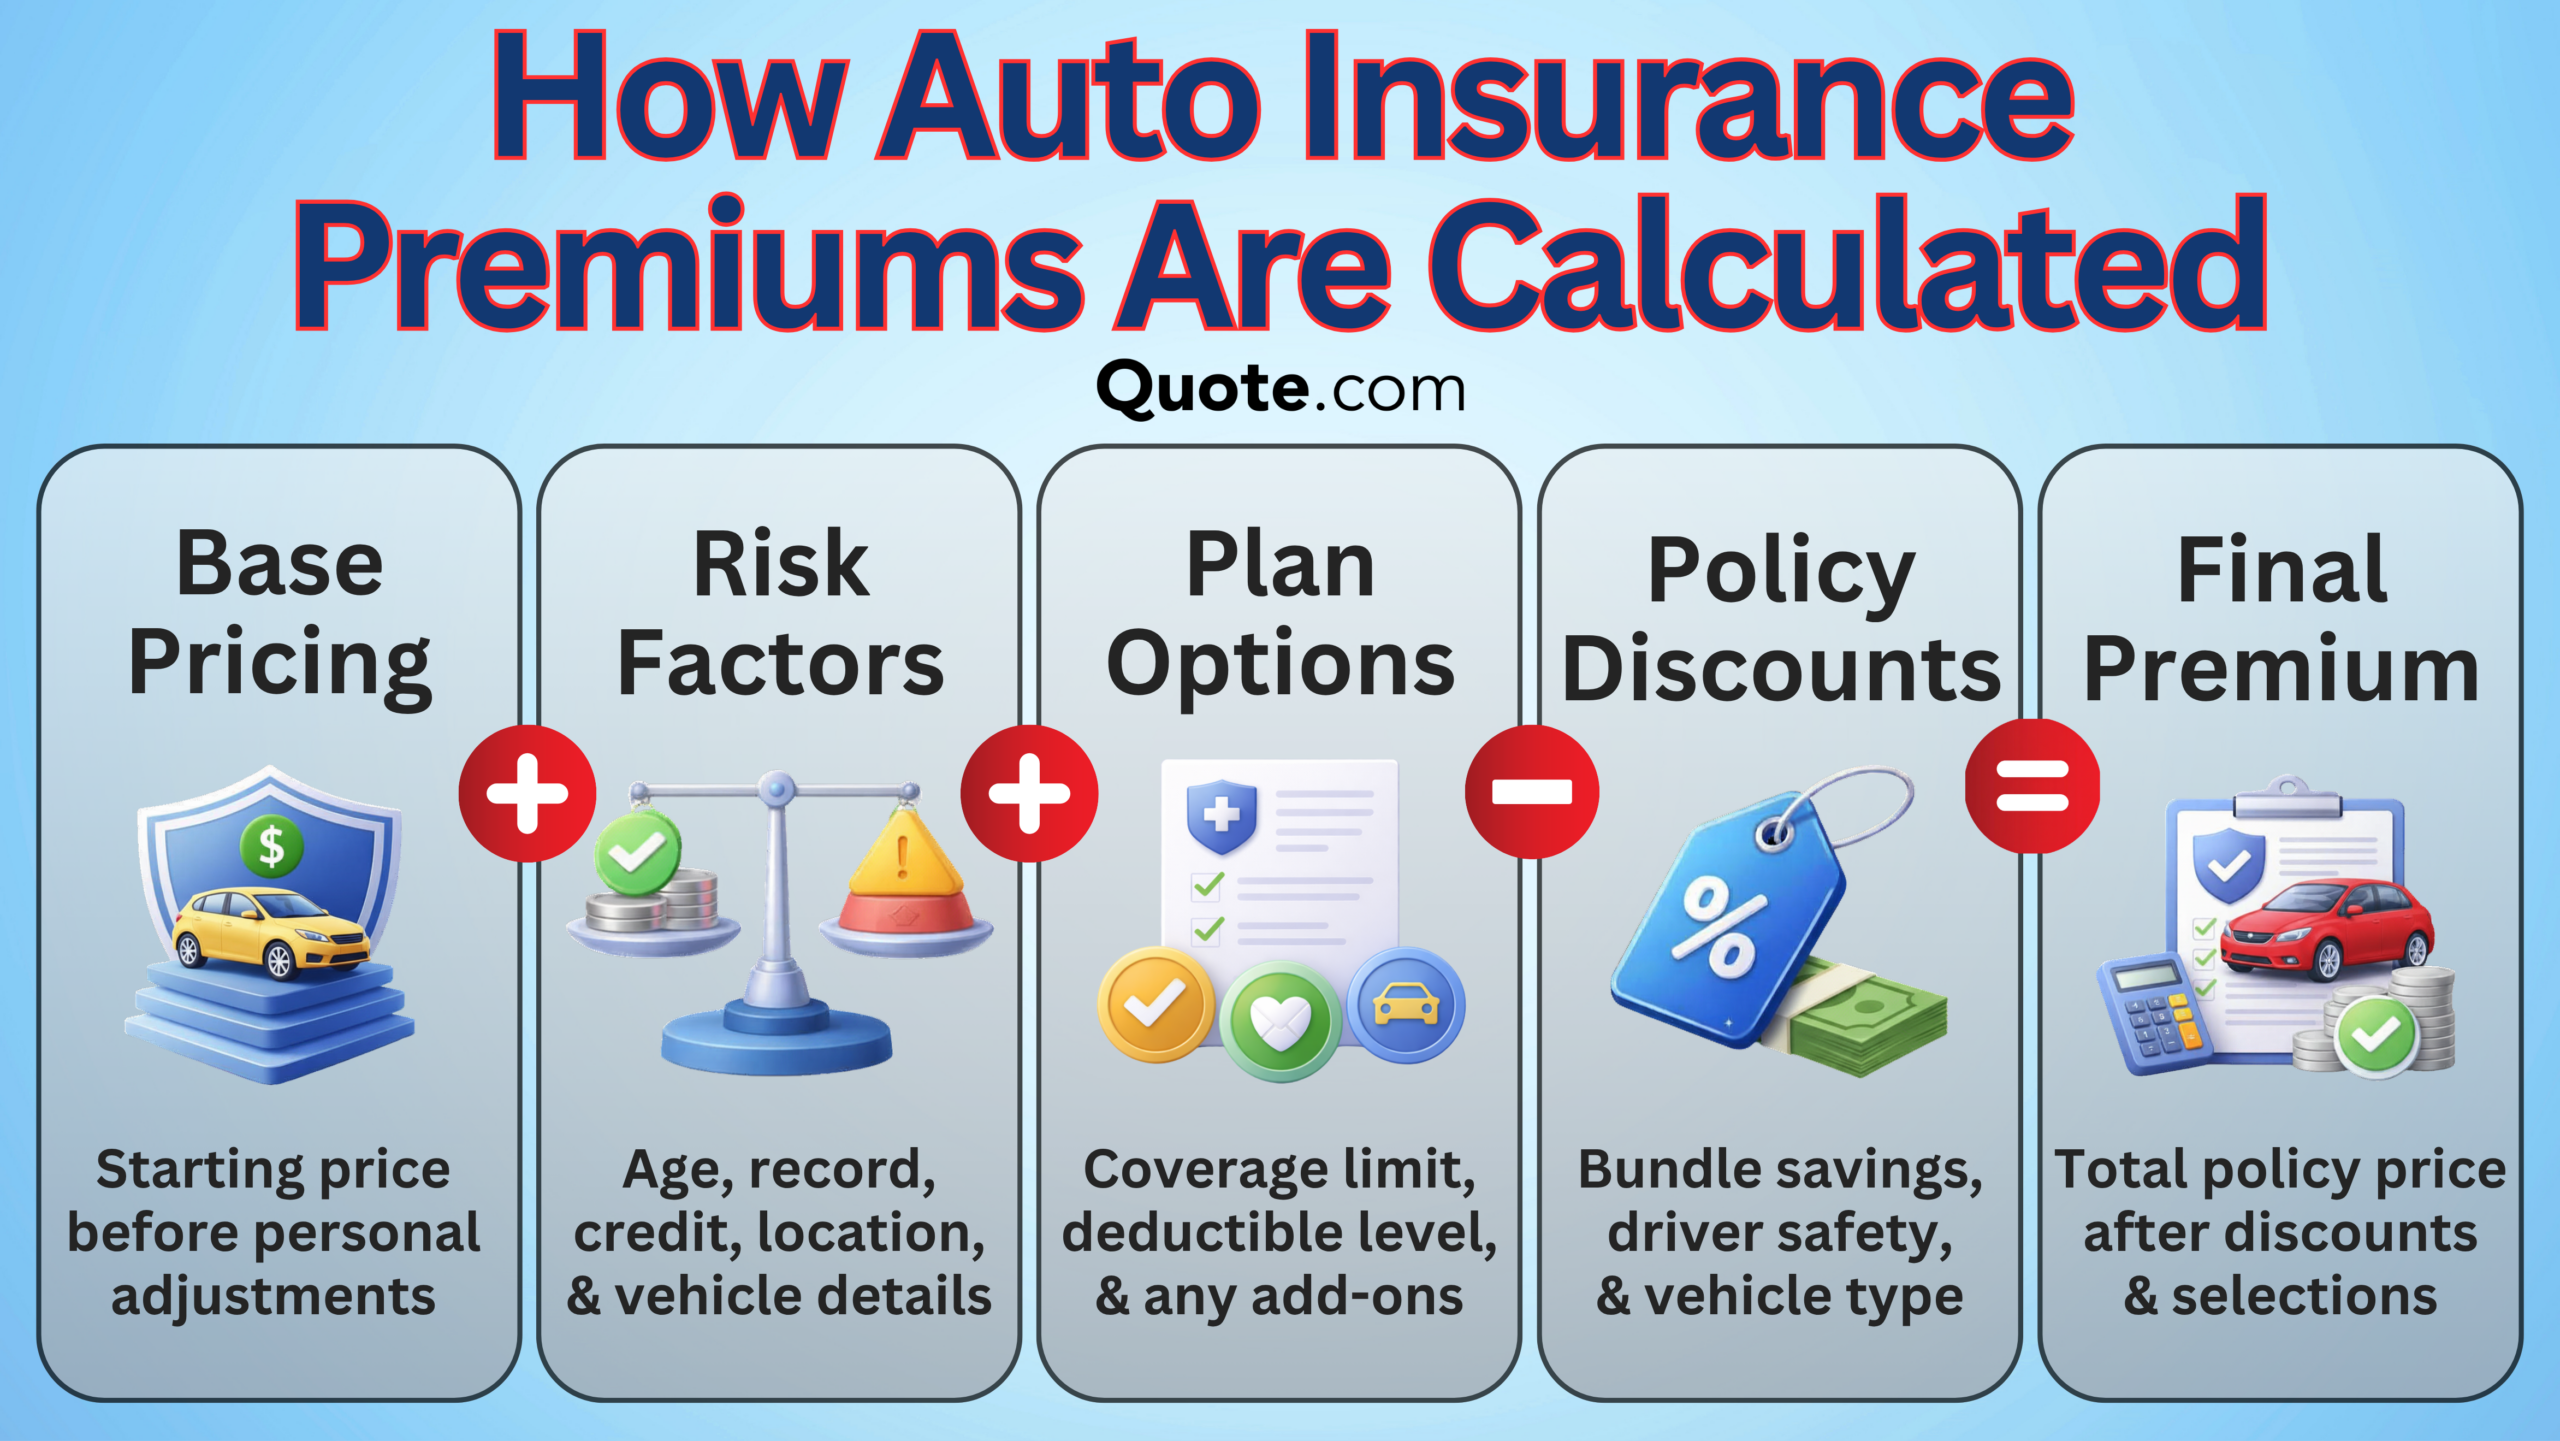
Yes, auto insurance policies require the payment of premiums. An insurance premium is the fixed or recurring amount of money a policyholder pays to an insurance company in exchange for the coverage outlined in their policy contract. Without timely payment of these premiums, the insurer is not legally obligated to provide coverage, which can lead to policy cancellation and potential legal consequences.
What is an Auto Insurance Premium?
At its core, an auto insurance premium is the price tag for risk transfer. When you purchase a policy, you are essentially entering into a legal contract where the insurance company agrees to bear the financial burden of specific incidents—such as accidents, theft, or liability claims—in exchange for a fee. This fee is known as the premium.
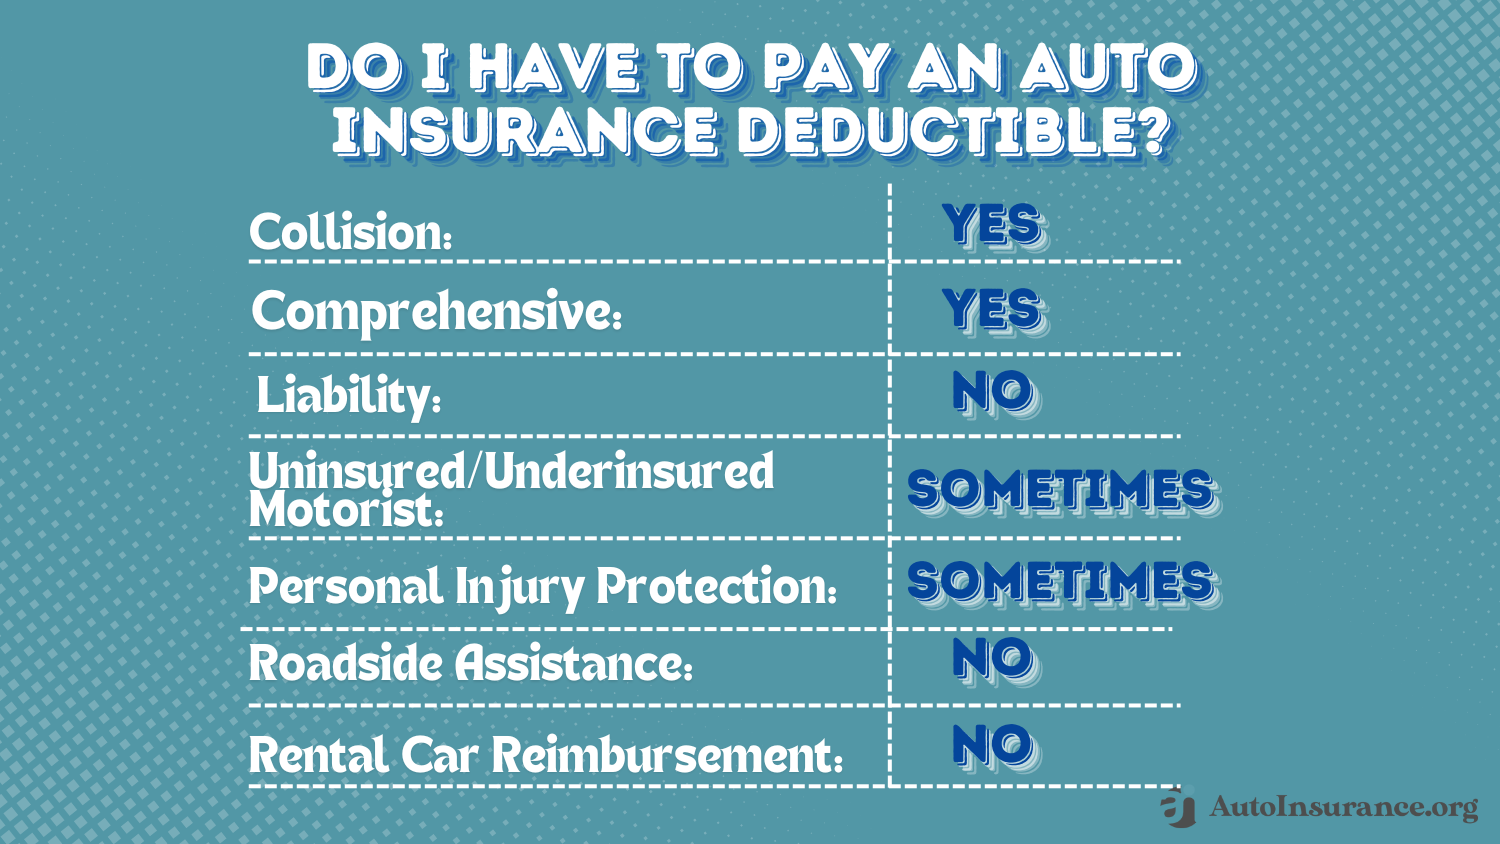
Unlike a deductible, which is a one-time out-of-pocket cost you pay only when filing a claim, the premium is an ongoing operational cost of owning a vehicle. Even if you never file a claim, the premium remains due for the duration of the policy term. This is because the insurer is providing continuous "readiness" to respond to a potential event. The premium covers the insurer’s administrative costs, the pooling of risk among many drivers, and the capital reserves necessary to ensure they can pay out claims when they occur.
How Premiums Are Determined
Insurance companies do not charge a flat rate to every driver. Instead, they use complex actuarial science to determine the premium for each individual. By analyzing vast sets of data, insurers calculate the statistical probability of a policyholder filing a claim. Several factors influence the final dollar amount of your premium:
- Driving History: This is often the most significant factor. Drivers with a history of at least-accidents, moving violations, or DUI/DWI convictions are statistically more likely to file future claims, resulting in higher premiums.
- Vehicle Characteristics: The make, model, age, and safety features of your car affect your rate. A vehicle that is expensive to repair, highly desirable to thieves, or lacks modern safety technology will generally cost more to insure.
- Demographic Data: Age, marital status, and geographic location play a role. Younger, inexperienced drivers typically face higher premiums because historical data shows them to be at a higher risk for accidents. Urban areas with higher crime or traffic density often carry higher premiums than rural settings.
- Credit-Based Insurance Scores: In many jurisdictions, insurers use credit information to predict the likelihood of a claim. Data suggests that individuals with higher credit scores are less likely to file claims, which can lead to lower premiums.
- Coverage Levels: The breadth of your policy directly impacts the cost. Minimum liability coverage required by state law is cheaper than a comprehensive policy that includes collision, comprehensive, uninsured motorist, and high-limit liability coverage.
Payment Structures and Frequency
Insurance premiums are rarely paid in a single lump sum for the life of a car. Instead, they are structured around specific policy terms.
- Policy Terms: Most auto insurance policies are issued for six-month or twelve-month periods. At the end of the term, the insurer re-evaluates your risk profile, and your premium may increase, decrease, or remain the same based on new data.
- Payment Installments: While you can often pay the full annual or semi-annual premium upfront to receive a discount, most insurers offer installment plans. You might pay monthly, quarterly, or bi-annually. Note that many insurers charge a small "installment fee" or "convenience fee" for processing smaller, more frequent payments.
- Automatic Deductions: To ensure coverage continuity, many providers encourage electronic funds transfer (EFT) or automatic credit card payments. This reduces the risk of an accidental lapse in payment, which could result in a policy cancellation and an immediate loss of legal status to drive.
The Consequences of Non-Payment
Failing to pay your premiums on time is a serious matter. Insurance contracts contain a "grace period," a short window—often 10 to 30 days—after a missed due date during which you can catch up on payments without losing coverage. If payment is not received by the end of this grace period, the consequences are immediate:
- Policy Lapse: Your coverage ceases to exist. If you are involved in an accident during this time, you will be personally liable for all damages, and your insurer will deny any claims.
- Legal Penalties: In almost all jurisdictions, auto insurance is mandatory. Driving without a valid policy can lead to the suspension of your driver’s license, vehicle impoundment, and heavy fines.
- Future Costs: When you attempt to obtain a new policy after a lapse, insurers view you as a "high-risk" applicant. This often results in significantly higher premiums for several years, as you have demonstrated an inconsistent history of maintaining financial responsibility.
Comparing Premium Costs Across Different Coverage Types
Understanding what you are paying for helps in managing your budget. The following table summarizes how different components of an auto insurance policy influence your premium.
| Coverage Type | Purpose | Impact on Premium |
|---|---|---|
| Liability | Covers injuries and property damage you cause others. | Mandatory; foundational cost. |
| Collision | Covers damage to your car from an accident. | Higher; based on vehicle value. |
| Comprehensive | Covers theft, fire, or weather damage. | Moderate; based on local risk data. |
| Uninsured Motorist | Protects you if the at-fault driver has no insurance. | Variable; high impact in high-traffic areas. |
| Medical Payments | Covers your own medical expenses regardless of fault. | Lower; supplemental coverage. |
Strategies for Managing Premiums
While premiums are mandatory, they are not necessarily stagnant. There are several verified methods to potentially reduce your annual expenditure without compromising on necessary coverage:
- Bundling Policies: Many insurers provide significant discounts if you "bundle" your auto insurance with other policies, such as homeowners or renters insurance.
- Increasing Deductibles: If you have the financial savings to handle a larger out-of-pocket expense in the event of an accident, opting for a higher deductible will lower your monthly premium. This is a common strategy for owners of older, lower-value vehicles.
- Maintaining a Clean Record: Over time, moving violations fall off your record. By driving safely and avoiding claims, you become eligible for "good driver" discounts, which can substantially lower your rates during the next renewal cycle.
- Shopping Around: Markets change. It is recommended to gather quotes from multiple reputable insurers every two to three years. Each company uses a unique internal algorithm, and a company that was expensive for your demographic two years ago might offer competitive rates today.
- Telematics Programs: Some insurers offer programs where you install a device or use a smartphone app to track your driving habits. If the data shows you are a safe driver—avoiding sudden braking, excessive speeding, or late-night driving—you may earn a discount on your premiums.
Frequently Asked Questions
Does the premium stay the same for the life of the vehicle? No. Premiums are adjusted at every renewal cycle. Changes in your driving history, the age and market value of your vehicle, and general inflationary trends in the insurance industry mean that your premium will fluctuate over time.
Can I get a refund if I cancel my policy early? Yes. If you pay your premiums in advance and decide to cancel your policy before the term ends, most insurers will provide a "pro-rated" refund for the unused portion of the premium, minus any applicable cancellation fees or administrative charges.
Is the premium the same thing as the deductible? No. The premium is the cost of having the insurance policy, while the deductible is the amount you pay out-of-pocket when you file a claim before the insurance company pays the remainder of the covered loss.
Why did my premium go up even though I didn't file a claim? Insurers frequently adjust rates for entire geographic regions or age groups based on localized accident statistics or the rising costs of auto repairs and medical services. Even if your personal driving record is pristine, market-wide cost increases can affect your premium.
What happens if I stop driving for a few months? If you plan to store your vehicle and not drive it, you may be able to drop liability coverage. However, it is vital to contact your insurance agent first. In many states, if your vehicle is registered, the state DMV expects you to maintain proof of insurance. Allowing a lapse in coverage can lead to severe fines even if the car is not being driven.
Next Actions for Policyholders
To ensure your financial and legal security, your next step should be to review your current policy declarations page. Identify your renewal date and the specific breakdown of your coverage. If you feel your current premiums are higher than market averages, request quotes from at least three different insurers to compare coverage limits and costs. Always prioritize maintaining continuous coverage to avoid the long-term financial penalties associated with a lapse.
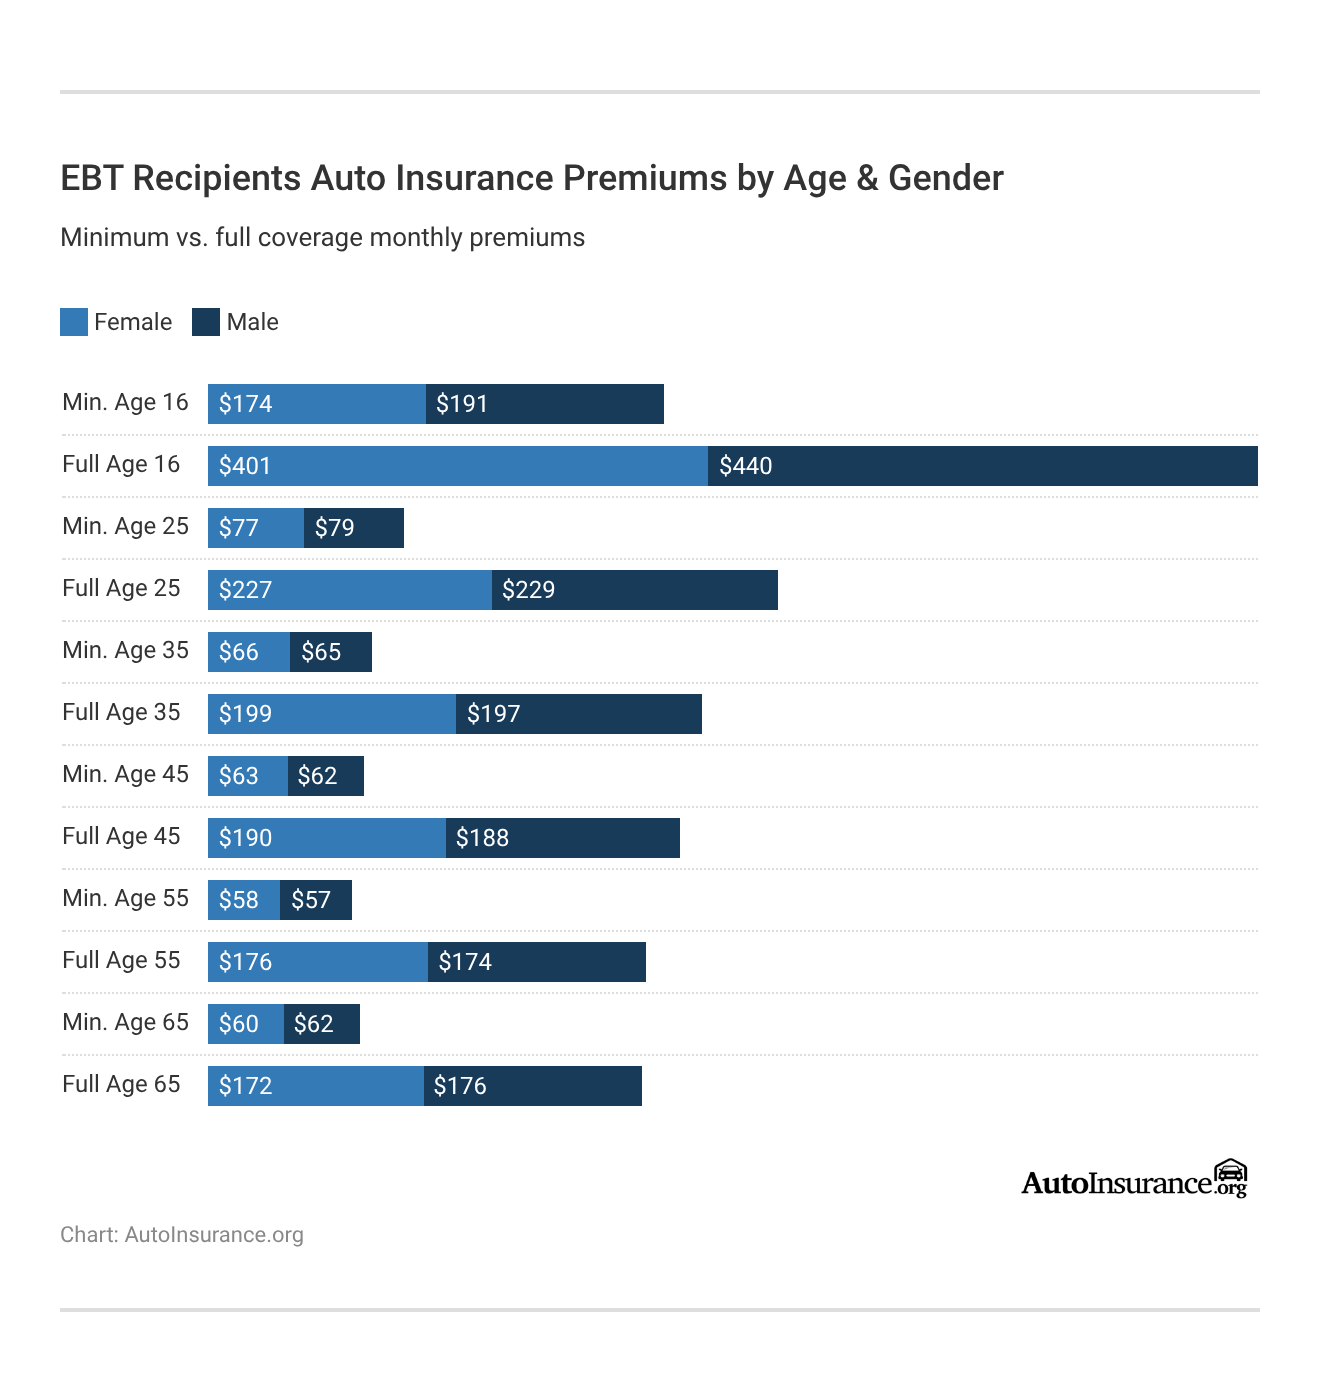
Image Gallery
Select an image to open it in a new tab.
Simon Caldwell
Enterprise Technology and Systems Editor
