
Bundling your car and home coverage can yield meaningful financial savings and administrative convenience, but deciding whether a combined policy is truly worthwhile requires a careful look at coverage limits, premium discounts, claims handling, and potential drawbacks. For most property owners, bundling is a financially sound strategy, provided the underlying policy terms meet your specific asset protection needs.
Evaluating the true value of insurance requires looking past marketing promises and promotional discounts to examine how policies function during a catastrophic loss. Insurance is fundamentally a risk-transfer mechanism designed to protect your personal net worth and financial stability from unpredictable events. When consumers ask whether auto and homeowners insurance is worth it, they are usually questioning if the combined cost of premiums yields adequate financial protection, or if alternative strategies—such as purchasing policies separately from different carriers—might offer better financial outcomes or higher coverage quality.
Understanding Policy Bundling and Multi-Policy Discounts
Policy bundling, commonly referred to as multi-policy insurance, occurs when a single insurance carrier provides coverage for two or more distinct assets. The most frequent combination involves pairing a homeowners insurance policy with a personal auto insurance policy. Insurance companies heavily incentivize this practice because multi-policy clients historically present lower churn rates and lower overall administrative costs.
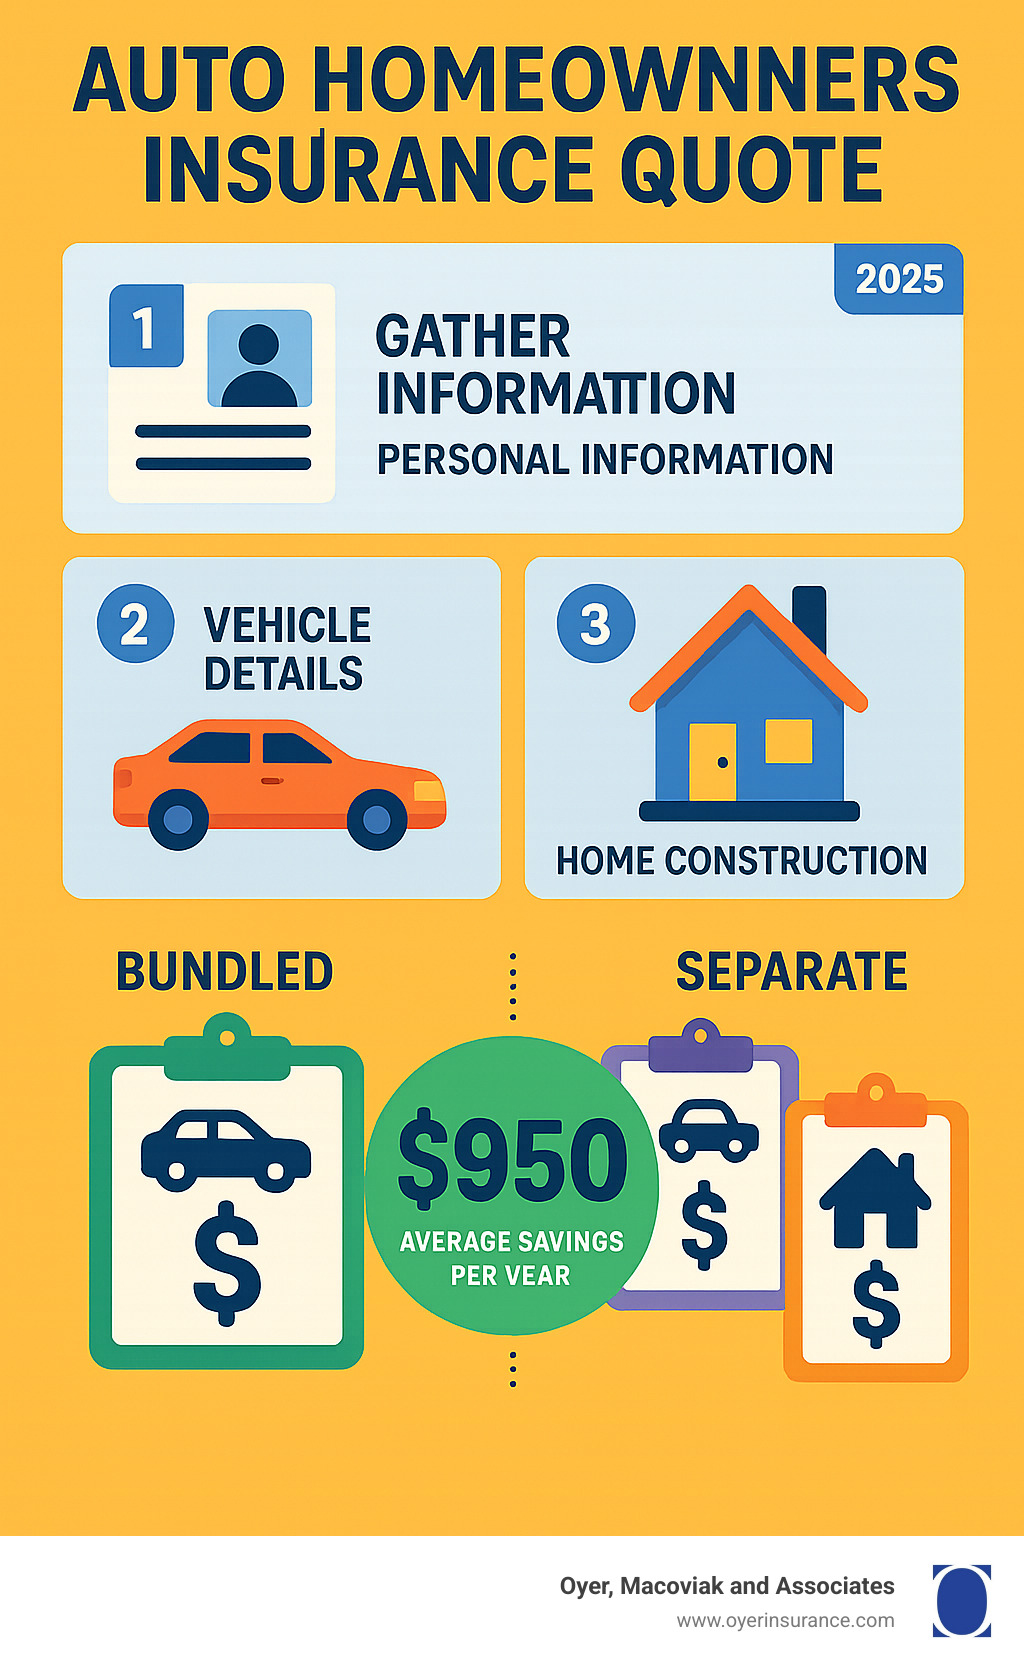
From an economic perspective, insurance carriers pass a portion of these operational savings back to the consumer through a multi-policy discount. These discounts vary significantly by provider and jurisdiction, frequently ranging from 5% to 25% off the total premium. However, a steep discount does not automatically mean the bundled option is the cheapest or most effective choice. To determine if bundling is worth it, you must calculate the final out-of-pocket cost of the bundled package against the cost of purchasing separate, best-in-class standalone policies from competing providers.
Furthermore, bundling introduces a centralized management dynamic. Instead of tracking separate billing cycles, renewal dates, policy numbers, and online portals with two distinct companies, policyholders interact with a single corporate entity. This consolidation reduces administrative friction, simplifies record-keeping, and ensures that policy documents are accessible through a unified dashboard.
Financial Advantages of Combining Auto and Home Policies
The primary driver for combining auto and homeowners insurance is financial optimization. Beyond the headline multi-policy discount, policyholders often unlock secondary cost-saving mechanisms that lower their total annual insurance expenditures.
Cumulative Premium Reductions
When you insure multiple assets with one carrier, your risk profile with that specific insurer expands. Underwriters use this expanded relationship to apply tiered pricing models. In many cases, the insurer applies the discount to both the auto policy and the homeowners policy, compounding the savings across both lines of coverage.
Reduced Deductible Disasters
Certain specialized bundling programs feature single-loss deductibles or disappearing deductible incentives. If a severe weather event damages both your residential dwelling and your parked vehicle—such as a severe hailstorm or a fallen tree—some insurers waive or reduce one of the deductibles if both claims are processed through the same master policy structure. This feature alone can save thousands of dollars during a catastrophic incident.
Loyalty and Longevity Rewards
Carriers frequently reward bundled customers with longevity perks. These can include accident forgiveness programs, diminishing deductibles for every claim-free year, and priority underwriting review. Over a multi-year timeline, these cumulative benefits add substantial value to the insurance relationship.
| Feature / Consideration | Bundled Auto and Home Policies | Separate Standalone Policies |
|---|---|---|
| Billing & Management | Single monthly invoice, unified portal, one renewal date. | Multiple bills, separate renewal timelines, distinct portals. |
| Average Discount Potential | 5% to 25% combined premium savings. | Varies; rarely captures multi-policy tier discounts. |
| Claims Experience | One adjuster or coordinated team for multi-asset losses. | Separate adjusters and distinct claims departments per asset. |
| Underwriting Risk | High dependency; carrier can drop both lines for excessive claims. | Low dependency; a home claim does not automatically impact auto rates. |
| Customization & Specialization | Limited to what a single carrier offers in your market. | Allows pairing high-risk auto specialists with high-value home insurers. |
Potential Drawbacks and Hidden Risks of Bundling
While financial savings make bundling attractive, consumers must evaluate the structural downsides. Insurance is not a commodity where price is the only variable; coverage breadth and claims responsiveness matter immensely when an emergency occurs.
The All-Eggs-in-One-Basket Vulnerability
When your auto and home policies reside with a single insurance provider, that company holds significant leverage over your entire insurance portfolio. If you file a major homeowners claim—such as a severe pipe burst or roof damage—the insurer evaluates your entire risk profile. Because both lines are tied together, a single high-value homeowners claim can trigger a non-renewal or a massive rate hike on your auto policy, even if you have maintained a pristine driving record for decades.
Compromised Coverage Quality
It is rare for a single insurance carrier to excel equally in both personal auto and high-value property insurance. A company known for highly competitive auto insurance rates might offer mediocre homeowners coverage with restrictive endorsements, high sub-limits on water backup, or actual cash value settlements instead of replacement cost for roofs. Bundling can tempt consumers into accepting inferior coverage terms on one asset simply to secure a discount on the other.
The Illusion of Savings
Aggressive marketing campaigns often highlight the percentage saved rather than the baseline dollar amount. A 20% discount on an overpriced baseline premium may still result in a higher annual cost than purchasing a competitively priced standalone policy from an independent carrier. Consumers must review the absolute dollar figures rather than relying solely on discount percentages.
Comparing Bundled Packages vs. Standalone Coverage
Deciding whether to bundle requires a systematic comparison of market alternatives. Independent insurance agents can run comparative rater software to display side-by-side pricing for bundled scenarios versus mismatched standalone combinations.
When performing this comparison, evaluate the following metrics:
- Total Annual Premium: Sum the cost of the auto and home policies under both models.
- Coverage Inclusions: Verify that dwelling coverage, liability limits, uninsured motorist protection, and personal property riders match across quotes.
- Deductible Structures: Ensure that percentage-based wind/hail deductibles or flat comprehensive deductibles are standardized for accurate comparison.
- Financial Strength Ratings: Check independent rating agencies such as A.M. Best to confirm that the proposed carriers possess strong financial backing to pay claims reliably.
In markets prone to natural disasters—such as coastal regions susceptible to hurricanes or wildfire-prone zones—specialized property insurers often provide vastly superior coverage terms compared to multi-line national carriers. In these scenarios, breaking the bundle and securing a specialized property policy while maintaining an auto policy elsewhere is frequently worth the administrative effort.
Factors to Consider Before Making a Decision
Before committing to a bundled policy or canceling an existing arrangement, examine your personal risk profile and financial objectives. Insurance needs evolve across different life stages, and a policy structure that makes sense for a young professional may fail to protect a family with substantial accumulated assets and multiple vehicles.
Asset Protection and Liability Limits
If your net worth exceeds standard auto and homeowners liability limits (typically $300,000 to $500,000), you must ensure that your chosen carrier offers high liability caps or seamless umbrella insurance integration. Bundling makes adding an umbrella policy easier, as most insurers require you to hold underlying auto and home policies with them before issuing personal umbrella liability coverage.
Vehicle Types and Driver Demographics
If your household includes youthful operators, high-performance vehicles, or drivers with past moving violations, standard multi-line carriers may penalize your entire bundle. In contrast, specialty auto insurers focus exclusively on high-risk or unique driving profiles, sometimes offering lower rates than a mainstream bundled carrier willing to take on both your home and your teen driver.
Property Characteristics
Historic homes, custom-built properties, or homes with specialized architectural finishes often require customized endorsements that standard multi-line insurers struggle to underwrite correctly. Specialized high-net-worth property insurers provide comprehensive coverage forms—such as guaranteed replacement cost—that far outweigh the savings of a standard bundled discount.
Common Misconceptions Regarding Multi-Policy Insurance
Several persistent myths surround auto and homeowners insurance bundling, often leading consumers to make suboptimal financial decisions.
- Myth 1: Bundling guarantees the lowest total price. Price is a function of underwriting algorithms, not marketing bundles. Always request separate quotes to verify if the bundle is genuinely cheaper.
- Myth 2: You cannot change one policy without canceling the other. While you receive the multi-policy discount by keeping both active, you are legally permitted to cancel or switch one policy mid-term, though you will forfeit the multi-policy discount on the remaining policy.
- Myth 3: Claims on one policy will never affect the other. As noted previously, multi-line underwriters monitor your comprehensive risk profile. Severe losses on a home policy can lead to underwriting actions on an auto policy at renewal time.
Frequently Asked Questions
Is auto and home insurance always cheaper when bundled?
No. While bundling triggers a multi-policy discount, a carrier with high baseline rates can still be more expensive overall than two separate, competitively priced standalone policies from different companies. Always compare the total annual cost.
What happens to my discount if I cancel my car insurance policy?
If you cancel one policy, the multi-policy discount is removed from the remaining policy at the next billing cycle or renewal, causing your premium for that remaining asset to increase.
Can I get an umbrella policy if my auto and home are with different companies?
Most major insurers require you to hold your underlying auto and homeowners insurance policies with them to qualify for a personal umbrella liability policy. A few specialty brokers offer standalone umbrella policies, but they are less common and often more expensive.
Does a home insurance claim raise my auto insurance rates?
It can. Insurance carriers evaluate your overall risk score at renewal. If you file a major homeowners claim, the insurer may classify you as a higher risk household and increase rates or adjust terms across all lines of coverage you hold with them.
How often should I re-evaluate my bundled insurance policies?
You should review your insurance policies at least once a year or whenever a major life event occurs, such as purchasing a new vehicle, remodeling your home, getting married, or moving to a new ZIP code. Insurance markets fluctuate rapidly, and competitor rates shift frequently.
Practical Next Actions for Policyholders
To determine if auto and homeowners insurance is worth it for your specific situation, gather your current policy declarations pages and verify your exact coverage limits, deductibles, and annual premiums. Contact an independent insurance broker who can access multiple competing carriers to run comparative quotes for both bundled and separated policy configurations. Calculate the net difference in cost, assess the quality of coverage provisions, and select the policy structure that maximizes your financial protection while keeping premiums manageable.
Image Gallery
Select an image to open it in a new tab.



Declan O'Connor
Higher Education and Campus Culture Reporter
