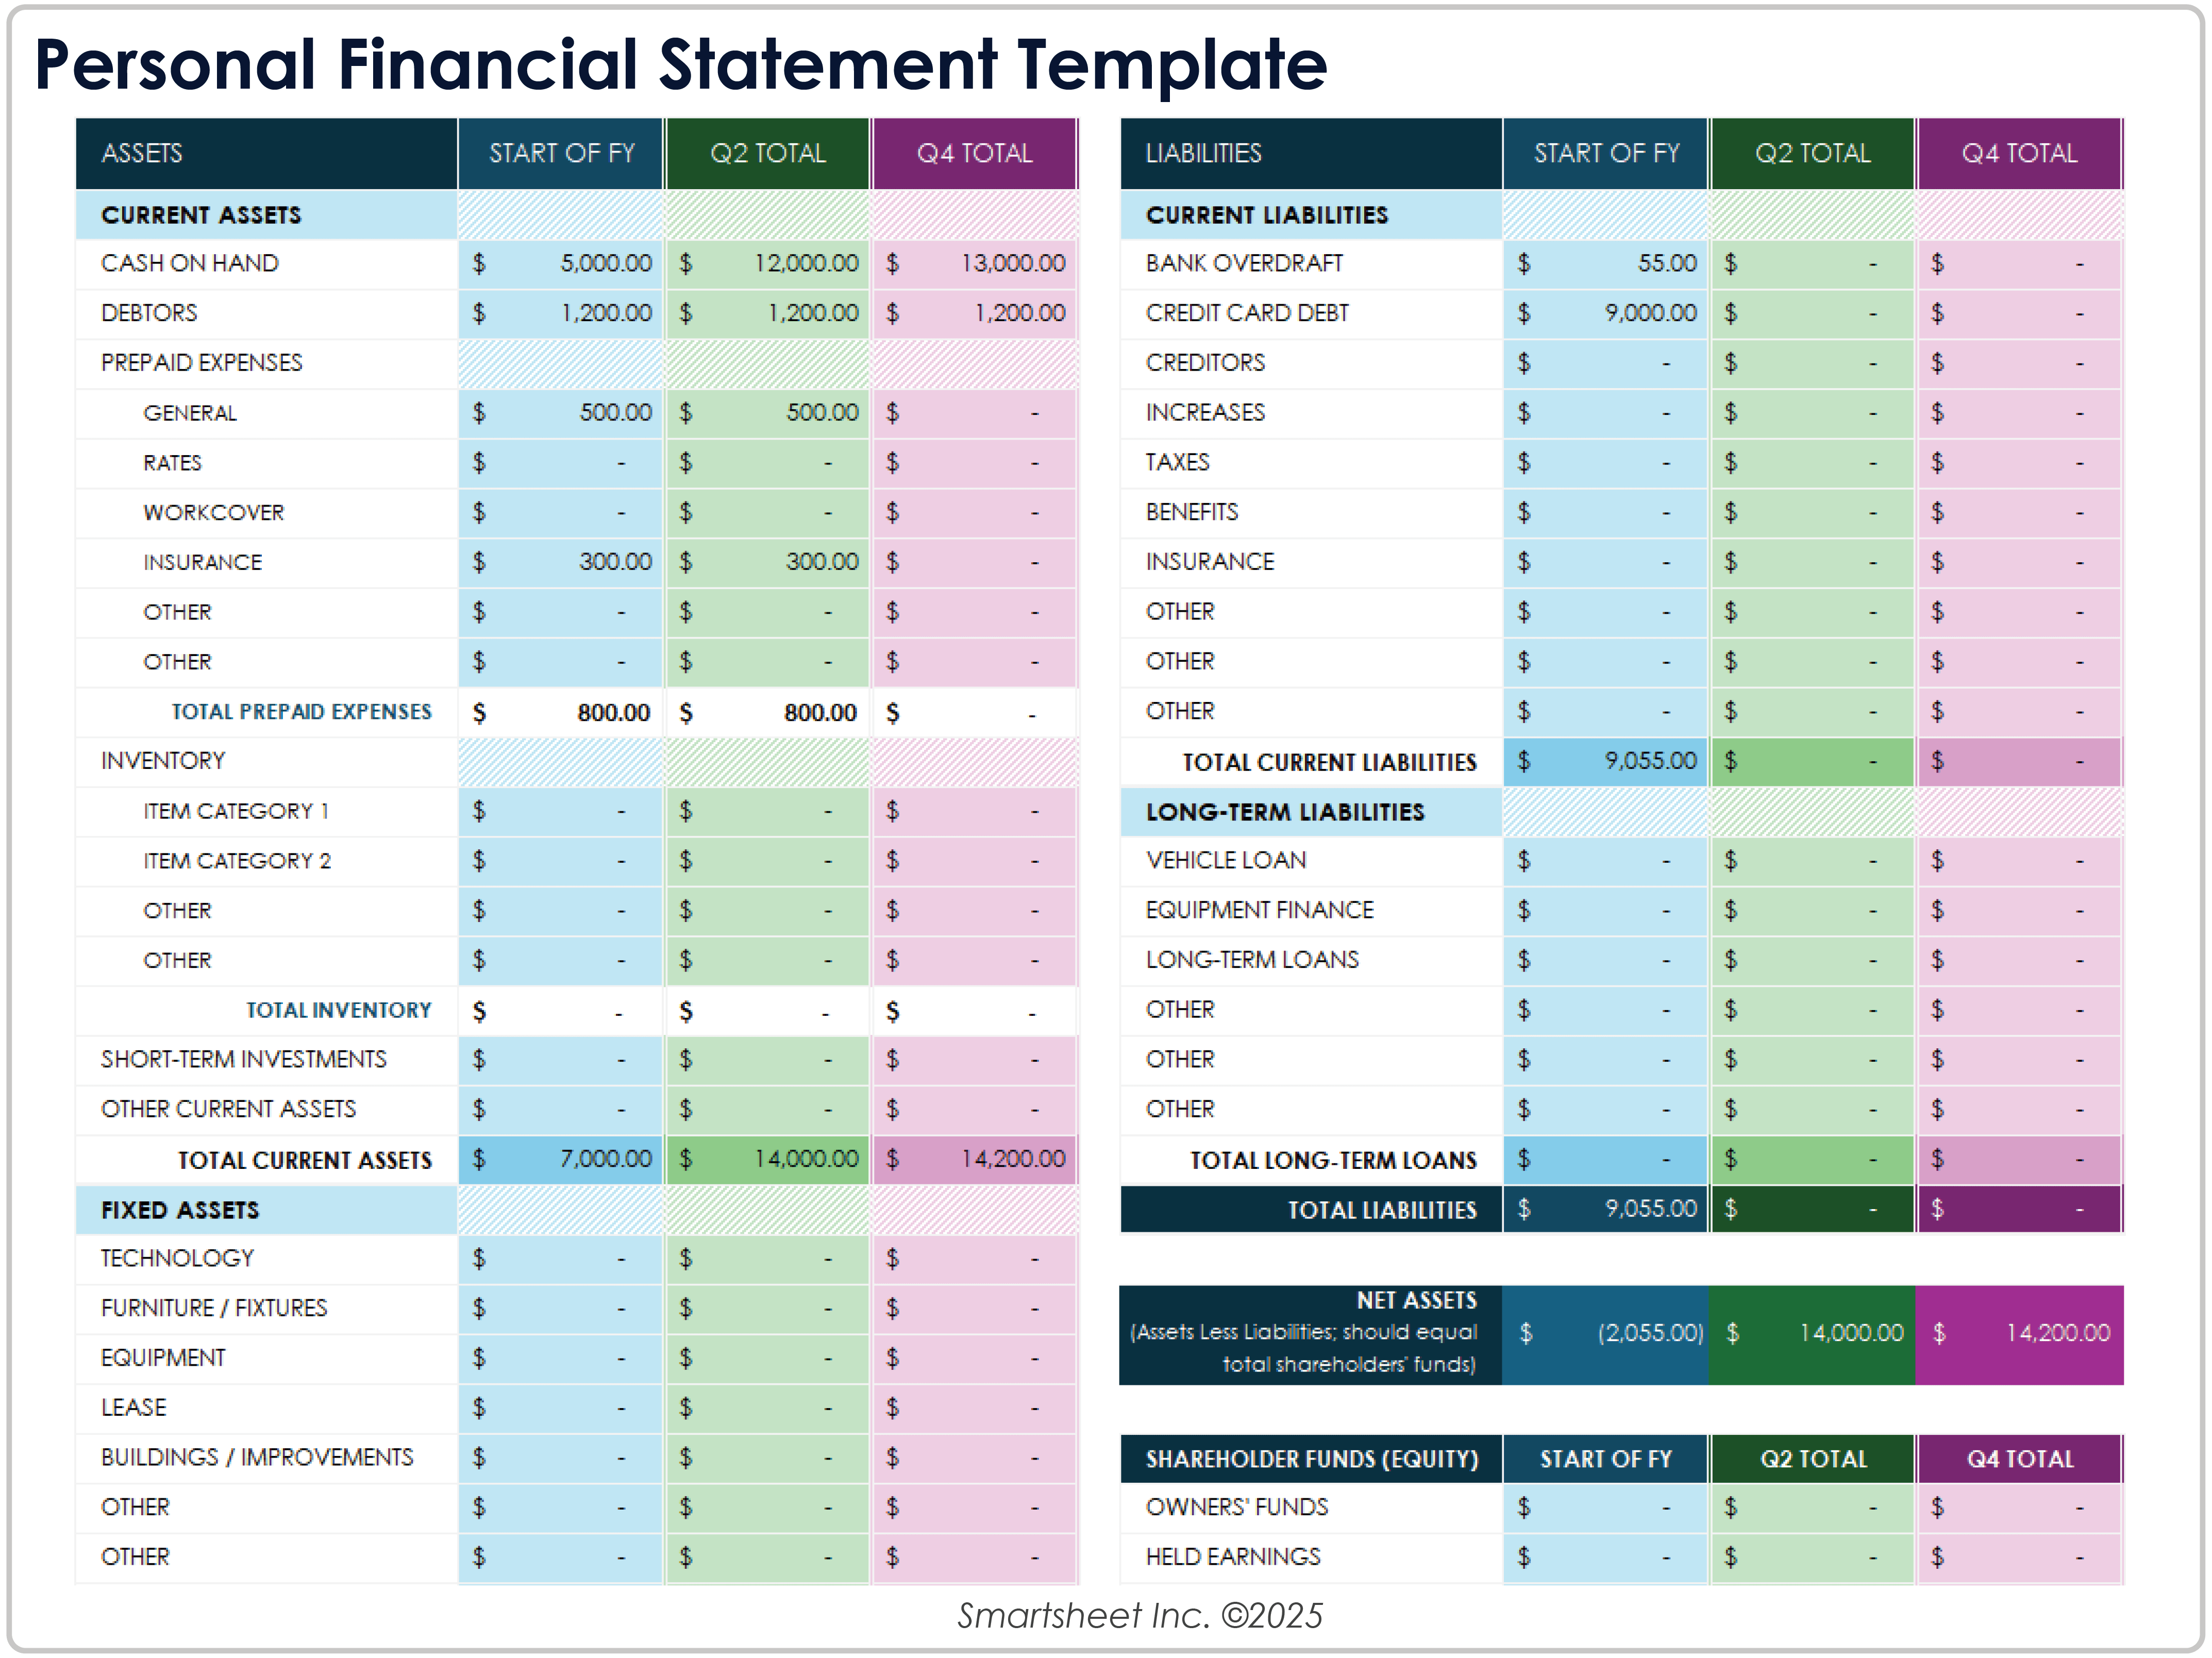
Financial planning in Massachusetts involves coordinating your personal wealth goals with state-specific regulations, such as the 5.0% flat income tax and the $2 million estate tax threshold. By integrating local tax incentives, like the 529 plan deduction, with strategic retirement and estate management, residents can navigate the Commonwealth’s unique economic landscape to achieve long-term financial security.
The Foundation of Massachusetts Financial Planning
Effective financial planning in the Commonwealth of Massachusetts requires a nuanced understanding of both the high cost of living and the specific state-level benefits available to residents. As of 2026, Massachusetts remains one of the most affluent states in the country, but it also presents unique challenges, particularly regarding housing costs and healthcare expenses. To make financial planning simple, one must first categorize their goals into three distinct buckets: short-term liquidity, mid-term growth, and long-term preservation.
The "Made Simple" approach begins with an assessment of the local economic environment. Massachusetts has a robust job market driven by the technology, healthcare, and education sectors. However, the concentration of wealth in the Greater Boston area often skews the perception of affordability. A simplified plan prioritizes an emergency fund that accounts for the state’s high rent or mortgage averages, typically recommending six to nine months of expenses rather than the national standard of three to six.
Furthermore, residents must account for the specific consumer protections offered by the Massachusetts Office of Consumer Affairs and Business Regulation. Understanding your rights regarding debt collection, credit reporting, and insurance can prevent common financial pitfalls. By establishing a solid foundation grounded in local reality, you can move toward more complex strategies like tax optimization and retirement readiness.
Navigating the Massachusetts Tax Landscape
One of the most significant aspects of simplifying your finances in Massachusetts is mastering the state’s tax structure. Often colloquially referred to as "Taxachusetts," the reality in 2026 is more nuanced. Massachusetts employs a flat income tax rate, which simplifies the calculation of your state liability compared to states with progressive brackets. However, the "Fair Share Amendment," which applies an additional 4% surtax on annual taxable income exceeding $1 million, adds a layer of complexity for high-earning residents.
Tax planning is not just about paying what you owe; it is about utilizing available credits to reduce your burden. For example, the Massachusetts "Circuit Breaker" tax credit provides relief to certain senior citizens whose property taxes or rent exceed a specific percentage of their income. Additionally, the state offers a deduction for rent paid, up to a maximum of $3,000 per year, which is a rare benefit not found in many other states.
For those focusing on education, the Massachusetts 529 College Savings Plan (the U.Fund) offers a state income tax deduction of up to $1,000 for single filers and $2,000 for married couples filing jointly. While these amounts may seem modest, the compounded tax-free growth within the account makes it a cornerstone of a simple but effective financial strategy. When you align these state-specific deductions with federal tax strategies, you create a cohesive plan that maximizes your take-home pay.

Retirement Planning for the Bay State
Retirement planning in Massachusetts requires a dual-track approach: managing private investments while understanding the complexities of the state's public pension systems. Many residents are employees of the Commonwealth, teachers, or municipal workers who participate in the Massachusetts Teachers’ Retirement System (MTRS) or the State Employees' Retirement System (MSERS).
The primary complication for public employees in Massachusetts is the Social Security Windfall Elimination Provision (WEP) and the Government Pension Offset (GPO). Because most Massachusetts public employees do not pay into Social Security through their state employment, their Social Security benefits from other private-sector work may be significantly reduced. Simplifying this process involves obtaining a detailed pension estimate early and using a "gap analysis" to determine how much additional private saving—through 403(b), 457(b), or IRAs—is necessary to maintain your lifestyle.
For private-sector workers, the focus should be on the high cost of late-stage retirement. Massachusetts is home to some of the nation’s best healthcare facilities, but the cost of assisted living and long-term care in the state is among the highest in the U.S. A simple retirement plan for a Massachusetts resident must include a dedicated strategy for long-term care, whether through traditional insurance, hybrid policies, or a robust health savings account (HSA) strategy.
Estate Planning and the $2 Million Threshold
Perhaps the most critical area where Massachusetts differs from the federal government is estate taxation. While the federal estate tax exemption is quite high, the Massachusetts estate tax threshold is set at $2 million as of 2026. Given the appreciation of real estate in markets like Newton, Cambridge, and even the South Shore, many middle-class families find themselves "accidentally" exceeding this limit.
If your total assets—including your home, life insurance payouts, and retirement accounts—exceed $2 million, your estate could face significant state taxes. Simplifying this issue often involves the use of trusts. A common strategy is the "Credit Shelter Trust" or "bypass trust," which allows couples to maximize both of their $2 million exemptions, effectively shielding up to $4 million from state estate taxes.
Beyond taxes, estate planning in Massachusetts is about ensuring your "MassHealth" (the state’s Medicaid program) eligibility is protected. Massachusetts has strict look-back periods for asset transfers. A simplified estate plan includes a Power of Attorney, a Health Care Proxy (which is the legally recognized term in MA for a medical power of attorney), and a Last Will and Testament. Without these, your assets may be subject to the lengthy and public probate process in the Massachusetts Trial Court.
Education Savings: The U.Fund and U.Plan
Massachusetts offers two distinct programs to help residents save for higher education, and choosing the right one is essential for a simple financial plan. The U.Fund is a traditional 529 plan managed by Fidelity Investments. It allows for flexible investment options and can be used at any accredited college in the country. The tax-free growth and state tax deduction make this the most popular choice for most families.
The U.Plan, however, is a unique "prepaid" tuition program. It allows you to lock in today’s tuition rates at over 70 participating Massachusetts colleges and universities. This program is backed by the Commonwealth’s "full faith and credit," making it an incredibly low-risk way to hedge against tuition inflation.
| Feature | U.Fund (529 Plan) | U.Plan (Prepaid Tuition) |
|---|---|---|
| Provider | MEFA / Fidelity Investments | MEFA / Commonwealth of MA |
| Investment Type | Market-based (Mutual Funds) | Tuition Certificates (Fixed Rate) |
| Where it’s used | Any accredited college globally | Participating MA colleges/universities |
| Risk Level | Market volatility dependent | Protected against tuition inflation |
| MA Tax Deduction | Yes ($1,000 / $2,000) | No |
| Federal Tax Status | Tax-free withdrawals for education | Tax-free withdrawals for education |
For a simplified approach, many advisors recommend using the U.Fund for its flexibility, especially if there is a chance the student will attend an out-of-state or private institution not covered by the U.Plan.
Investing and Asset Allocation in a High-Cost State
Investing in Massachusetts often requires a higher "hurdle rate" because of the cost of living. To maintain purchasing power, your portfolio must outpace both national inflation and the specific regional inflation of the Northeast. A simplified investment strategy for a Massachusetts resident often focuses on tax-efficient growth.
Since Massachusetts taxes interest and dividends at the same 5.0% rate as earned income (with some exceptions for certain types of capital gains), residents should prioritize holding tax-inefficient assets—like high-yield bonds or actively managed funds—inside tax-deferred accounts like 401(k)s or IRAs. Conversely, holding municipal bonds issued by Massachusetts entities can provide income that is exempt from both federal and state taxes, which is a powerful tool for those in higher tax brackets.
Furthermore, the "Massachusetts Uniform Prudent Investor Act" governs how fiduciaries should manage money in the state. This legal framework emphasizes the importance of diversification. A simple portfolio doesn't mean a limited one; it means a portfolio where every asset serves a specific purpose—whether it’s a low-cost S&P 500 index fund for growth or MA-specific "muni" bonds for tax-free income.
Finding and Vetting a Massachusetts Financial Advisor
While "doing it yourself" is possible, many find that the complexities of Massachusetts law require professional guidance. The key to keeping this simple is knowing how to vet an advisor. In Massachusetts, you should look for a Certified Financial Planner (CFP®) who operates as a fiduciary, meaning they are legally obligated to act in your best interest.
You can verify an advisor's credentials and disciplinary history through the Massachusetts Securities Division, led by the Secretary of the Commonwealth. This office provides public access to records that show whether an advisor has a history of complaints or regulatory issues. Additionally, check the SEC’s Investment Adviser Public Disclosure (IAPD) website for their Form ADV, which outlines their fee structure and investment philosophy.
Avoid advisors who "sell products" for commissions. Instead, look for "Fee-Only" advisors. This transparency ensures that the advice you receive is not clouded by the advisor's desire to earn a sales commission on an insurance policy or a high-load mutual fund. A simple relationship is one where you know exactly how much you are paying and what services you are receiving in return.
Common Mistakes in Massachusetts Financial Planning
- Ignoring the Estate Tax: Many residents assume they aren't "rich enough" for estate taxes, only to realize their home in a town like Lexington or Wellesley puts them over the $2 million limit.
- Misunderstanding Public Pensions: State employees often fail to account for the WEP/GPO reductions in Social Security, leading to a massive income gap in their 70s.
- Underestimating Healthcare Costs: Massachusetts has excellent healthcare, but the out-of-pocket costs for premium insurance and long-term care facilities are significantly higher than the national average.
- Inadequate Property Insurance: In coastal areas or historic towns, "standard" homeowners insurance may not cover the true replacement cost of a home or the unique risks of "King Tides" and coastal flooding.
- Forgetting the Rent Deduction: Every year, thousands of Massachusetts renters leave money on the table by failing to claim the $3,000 rent deduction on their state tax returns.
Frequently Asked Questions
Is there an inheritance tax in Massachusetts?
No, Massachusetts does not have an inheritance tax, which would be paid by the person receiving the money. However, it does have an estate tax, which is paid by the estate of the deceased person before assets are distributed. The current threshold for the Massachusetts estate tax is $2 million. If the estate exceeds this value, a return must be filed, and taxes may be owed on the entire value.
How does the Massachusetts 529 tax deduction work?
If you contribute to a Massachusetts 529 plan (U.Fund), you can deduct up to $1,000 from your state taxable income if you are a single filer, or up to $2,000 if you are married filing jointly. This is a "per-filer" limit, not a "per-child" limit. The contribution must be made to a plan sponsored by the Commonwealth of Massachusetts or the Massachusetts Educational Financing Authority (MEFA) to qualify for the state deduction.
What is the "Millionaire's Tax" in Massachusetts?
Formally known as the Fair Share Amendment, this is a 4% surtax on the portion of a taxpayer's annual taxable income that exceeds $1 million. For example, if you earn $1.2 million in 2026, the first $1 million is taxed at the flat 5% rate, and the remaining $200,000 is taxed at 9% (the 5% base rate plus the 4% surtax). This is a critical consideration for residents selling a business or a high-value property.
Do I need a trust if I live in Massachusetts?
While not everyone needs a trust, they are highly beneficial in Massachusetts for two main reasons: avoiding probate and minimizing estate taxes. Because the Massachusetts probate court system can be slow and expensive, a Revocable Living Trust allows assets to pass to heirs privately and quickly. Furthermore, specific types of trusts can help couples utilize both of their $2 million estate tax exemptions.
Are Social Security benefits taxed in Massachusetts?
No. Massachusetts is one of the states that does not tax Social Security benefits. While your benefits may be subject to federal income tax depending on your total income, the Commonwealth allows you to subtract Social Security income when calculating your Massachusetts adjusted gross income. This makes Massachusetts a relatively tax-friendly state for retirees who rely heavily on Social Security.
Practical Next Steps for Your Financial Plan
To simplify your financial planning in Massachusetts, start by calculating your total net worth, including the current market value of your home. If that number is near or above $2 million, your first priority should be consulting with an estate planning attorney to discuss tax-mitigation strategies. Next, review your state tax return to ensure you are claiming the rent deduction or the 529 plan contribution credit. Finally, if you are a public employee, use the MEFA or MTRS calculators to get a realistic view of your retirement income, accounting for Social Security offsets. By addressing these state-specific levers first, the rest of your financial plan will naturally fall into place.
Image Gallery
Select an image to open it in a new tab.


Mateo Castillo
Decentralized Finance and E-Payments Strategist
