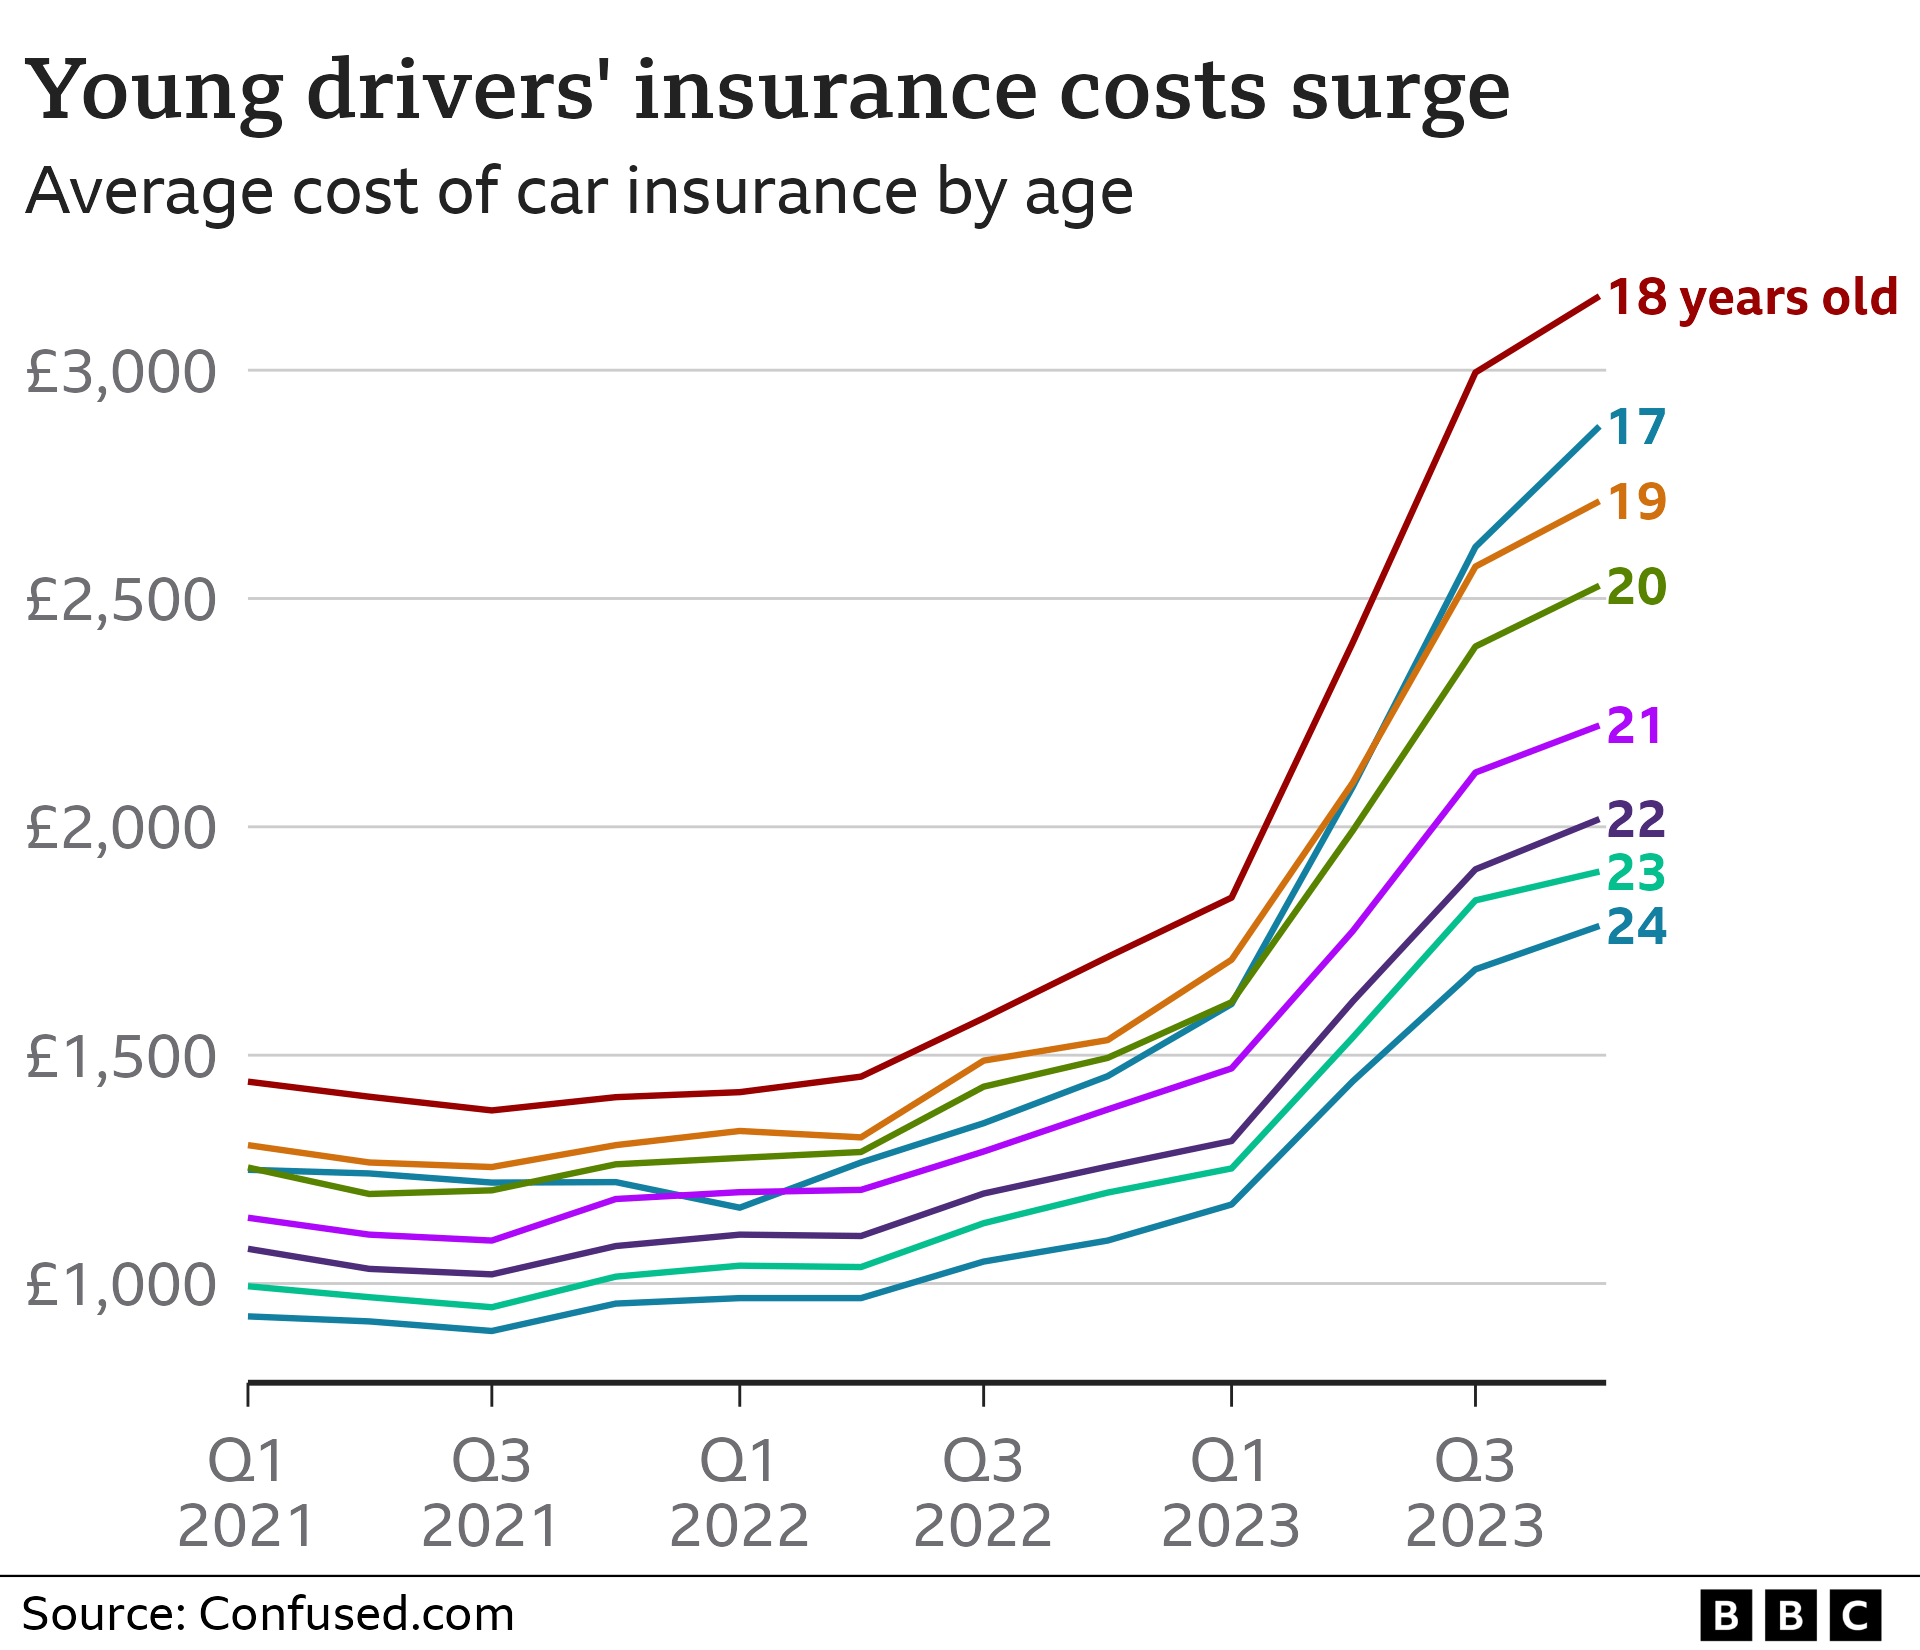
Car insurance for new drivers is priced significantly higher because insurers lack historical driving data to assess individual risk, forcing them to rely on high-risk statistical averages for the demographic. In 2026, these costs are further amplified by the extreme expense of repairing modern vehicle sensors, high inflation in medical care, and the rising prevalence of uninsured motorist surcharges.
For many young or first-time drivers, the arrival of an insurance quote can be a moment of genuine "sticker shock." While most expect to pay more than an experienced driver, the reality of 2026 premiums often exceeds those expectations by hundreds or even thousands of dollars. Understanding the layers of cost—from actuarial risk to the hidden impact of vehicle technology—is essential for any new motorist looking to navigate the modern financial landscape of vehicle ownership.
The Actuarial Reality: Statistical Risk and the "Inexperience Tax"
Insurance is, at its core, a game of probability. Actuaries—the professionals who calculate risk for insurance companies—utilize vast datasets to determine how likely a specific profile is to file a claim. For new drivers, the data is overwhelmingly negative. Statistics from the National Highway Traffic Safety Administration (NHTSA) and similar global bodies consistently show that drivers in their first two years of licensure are involved in significantly more accidents than any other age group.
This "inexperience tax" is not a judgment on the individual's character but a reflection of physiological and behavioral trends. Scientific research into brain development suggests that the prefrontal cortex, which governs risk assessment and impulse control, often does not fully mature until the mid-20s. Consequently, new drivers are statistically more likely to engage in speeding, distracted driving, and late-night travel—all of which are high-risk behaviors.
Furthermore, new drivers lack "muscle memory" for emergency maneuvers. An experienced driver might instinctively react to a hydroplaning event or a sudden obstacle, whereas a new driver’s delay in reaction—even by a fraction of a second—can turn a "near miss" into a total-loss collision. Because insurers have no way of knowing if a specific new driver is the exception to the rule, they must charge a premium that covers the high probability of a total-loss claim within the first 12 months.
Beyond the Driver: How 2026 Economic Factors Inflate Premiums
The cost of insurance is not just about the likelihood of a crash; it is also about the cost of making the "victim" whole again. In 2026, several economic factors have converged to drive these costs higher than ever before.
The Complexity of Vehicle Repairs
In previous decades, a "fender bender" involved replacing a piece of sheet metal and a plastic bumper. In 2026, even the most basic entry-level cars are equipped with Advanced Driver Assistance Systems (ADAS). A minor front-end collision now involves replacing delicate LiDAR sensors, high-definition cameras, and radar units housed within the bumper and windshield.
Replacing these components requires specialized labor and expensive recalibration software. A repair that would have cost $800 in 2016 can easily exceed $4,500 in 2026. Because new drivers are statistically more likely to be involved in these low-speed, high-cost impacts, their premiums must reflect the technological complexity of the modern fleet.
Medical Inflation and Legal Costs
The "Liability" portion of an insurance policy covers bodily injury to others. In 2026, the cost of emergency room visits, specialized surgeries, and long-term physical therapy has reached historic highs. Additionally, the legal environment has become increasingly litigious. Insurers must factor in the cost of defending their policyholders in court, which can involve massive legal fees even if the driver is eventually cleared of significant wrongdoing. For a new driver, the potential for a catastrophic liability claim is a primary driver of the premium.
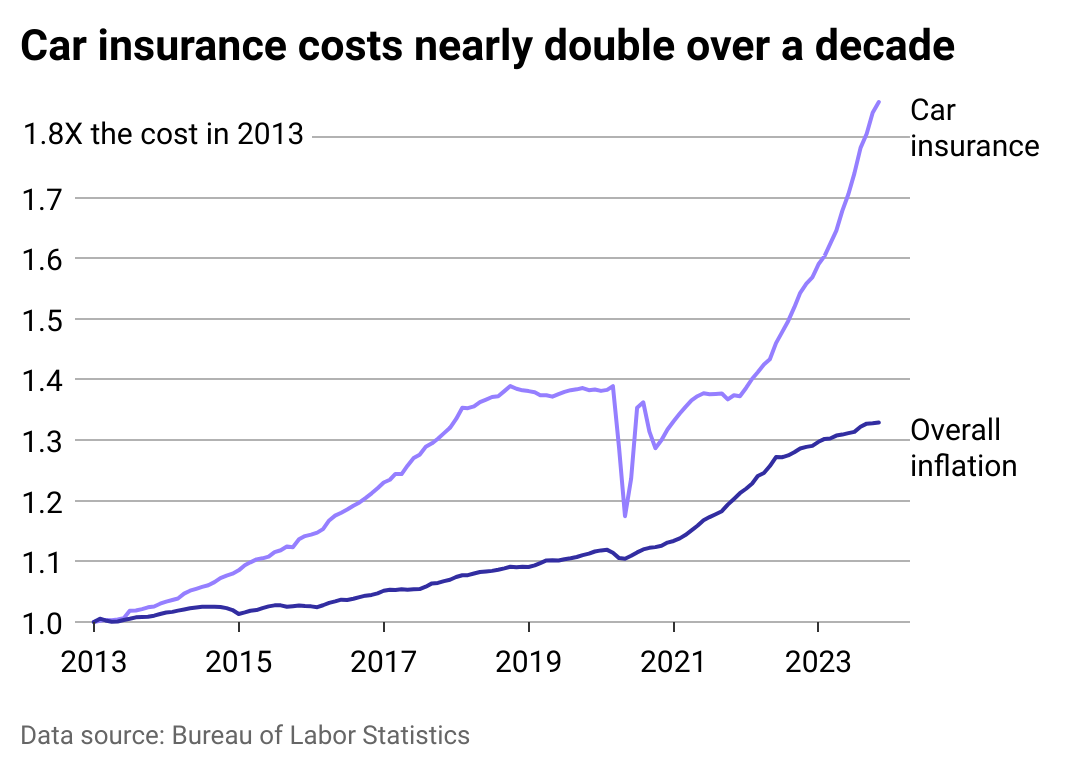
The "Zero History" Penalty: The Missing No Claims Discount
One of the most significant reasons insurance costs more than you think is the absence of a No Claims Discount (NCD) or No Claims Bonus (NCB). For experienced drivers, this discount can reduce premiums by 50% to 70%.
A new driver starts at zero. In the eyes of the insurer, you are a blank slate, and in the world of finance, "unknown" is often synonymous with "high risk." It takes years of documented, accident-free driving to earn the trust that results in a lower premium. When a new driver compares their quote to a parent’s or an older sibling’s, they aren't just seeing a higher base rate; they are seeing a rate that hasn't been softened by a decade of proven safety.
Hidden Costs: Admin Fees, Interest, and Mandatory Add-ons
The quote you see on a comparison site is often just the beginning. Several hidden layers can push the final cost significantly higher.
- Premium Finance Interest: Most new drivers cannot afford to pay an annual premium of $3,000 or more upfront. Opting for monthly installments usually involves an "arrangement fee" and a high interest rate (APR). In 2026, interest rates on insurance monthly payments can range from 12% to 19%, adding hundreds of dollars to the total annual cost.
- Telematics Installation: Some "Black Box" policies require a physical device to be fitted to the car. While these policies are often cheaper overall, there is sometimes an upfront installation fee or a "disconnection fee" if you cancel the policy.
- Compulsory Excess: New drivers are almost always saddled with a higher "Compulsory Excess" (the amount you pay toward a claim). While this doesn't increase your monthly premium, it represents a significant potential "out-of-pocket" cost that many new drivers fail to budget for.
- Uninsured Motorist Surcharge: In many jurisdictions, a portion of every premium goes into a fund to compensate victims of uninsured drivers. Because new drivers are perceived as part of a high-risk pool, their contribution to these collective risk funds is often disproportionately higher.
Impact of Vehicle Choice and Insurance Groups
In 2026, vehicles are categorized into insurance groups (typically ranging from 1 to 50) based on their performance, safety features, and repair costs. New drivers often underestimate how much the specific car affects the price.
A 10-year-old car might seem "cheap," but if it lacks modern safety features like autonomous emergency braking, the insurance might actually be higher than a newer, more expensive car. Conversely, a small car with a turbocharger might be classified as a "performance vehicle" by insurers, leading to a massive premium spike for a 17-year-old.
| Factor | Impact on New Driver Premium | Why It Matters in 2026 |
|---|---|---|
| Vehicle Group | High | Groups 1-5 are the only affordable options; high groups can be uninsurable for new drivers. |
| Location/Postcode | Very High | Crime rates and traffic density in 2026 are analyzed down to the street level via AI. |
| Telematics (Black Box) | Negative (Discount) | Can save 20-30% but requires strict adherence to speed and curfew rules. |
| Annual Mileage | Moderate | Higher mileage increases the "exposure window" for an accident. |
| Voluntary Excess | Moderate | Raising this lowers premium but increases personal financial risk in an accident. |
Strategies to Lower the Burden in 2026
While the costs are daunting, there are technical and strategic ways to mitigate the expense.
Telematics and AI Monitoring
The most effective way for a new driver to prove they are not a "statistical average" is through a telematics policy. These systems monitor braking, acceleration, cornering, and the time of day the vehicle is used. In 2026, many of these systems are app-based, using the smartphone's internal gyroscope and GPS. By providing the insurer with real-time data, the driver can earn "safety scores" that result in monthly or quarterly premium rebates.
Adding an Experienced Named Driver
Adding a parent or older relative with a clean driving record to the policy can often lower the total premium. The insurer assumes that the experienced driver will be behind the wheel for a portion of the time, statistically lowering the overall risk of the vehicle being involved in an accident. Caution: The new driver must remain the "Main Driver." Falsely claiming an experienced driver is the primary user is a fraud known as "fronting," which can lead to policy cancellation and criminal charges.
Choosing "Low-Tech" but Safe Cars
While ADAS increases repair costs, cars with high passive safety ratings (like those rated highly by Euro NCAP or the IIHS) still command lower premiums because they protect the occupants better, reducing the likelihood of expensive medical claims. Aiming for a vehicle in the lowest five insurance groups is the most reliable way to keep costs manageable.
Common Mistakes New Drivers Make
Many new drivers inadvertently inflate their own premiums through simple errors during the application process:
- Estimating Mileage Incorrectly: Overestimating annual mileage by even 2,000 miles can trigger a higher risk tier.
- Job Title Selection: Insurers use historical data associated with professions. For example, a "Chef" might pay more than a "Catering Professional" because chefs are statistically more likely to drive late at night when tired. Always use the most accurate title that describes your role from the insurer's drop-down list.
- Waiting Until the Last Minute: Buying insurance on the day you need it is a "high-risk" signal. Statistics show that people who plan ahead (buying 21 days in advance) are more responsible and less likely to crash. Buying 21 days early can save up to 20% compared to buying "on the day."
Frequently Asked Questions
Why does my location matter so much even if I have a garage?
In 2026, location data is incredibly granular. Insurers look at the frequency of "crash-for-cash" scams in your area, the rate of catalytic converter thefts, and even the local weather patterns (flood or hail risks). Even if your car is garaged, you must drive it on local roads where these risks exist.
Can I use my parents' No Claims Discount?
Generally, no. A No Claims Discount is non-transferable. However, some insurers offer "accelerated" policies where you can earn a full year of NCD in just ten months, or they may offer a small discount if you have been a named driver on a parent's policy without any accidents.
Does the color of my car affect the insurance cost?
Directly, no. There is no "red car tax." However, if a specific color is only available on a "Sport" trim of a vehicle, that trim level will be in a higher insurance group, leading to a higher cost.
Why is third-party-only insurance sometimes more expensive than fully comprehensive?
This is a classic "risk signal" paradox. In the past, high-risk drivers chose third-party-only insurance to save money. This created a data pool where third-party-only drivers were involved in significantly more accidents. Consequently, insurers now often charge more for lower coverage levels because the type of person who chooses them is statistically more likely to claim.
Is car insurance for electric vehicles (EVs) more expensive for new drivers?
In 2026, yes. EVs are typically heavier, faster (higher torque), and more expensive to repair than internal combustion engine (ICE) vehicles. For a new driver, the instant acceleration of an EV is seen as a major risk factor, often pushing these vehicles into much higher insurance groups.
Final Recommendation
To minimize the cost of car insurance as a new driver in 2026, you must move beyond the role of a "statistical probability" and become a "data-backed safe driver." Begin by choosing a vehicle in insurance groups 1 through 3, opting for a telematics policy to provide the insurer with proof of your safety, and purchasing your policy exactly 21 days before your start date. Avoid the temptation to pay monthly if you can secure a low-interest personal loan or use savings, as the interest rates on insurance premiums are currently at a premium.
Disclaimer: This article provides general information regarding car insurance trends in 2026 and does not constitute financial or legal advice. Insurance regulations and pricing vary by jurisdiction and individual circumstances. Always consult with a licensed insurance professional before making coverage decisions.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
