
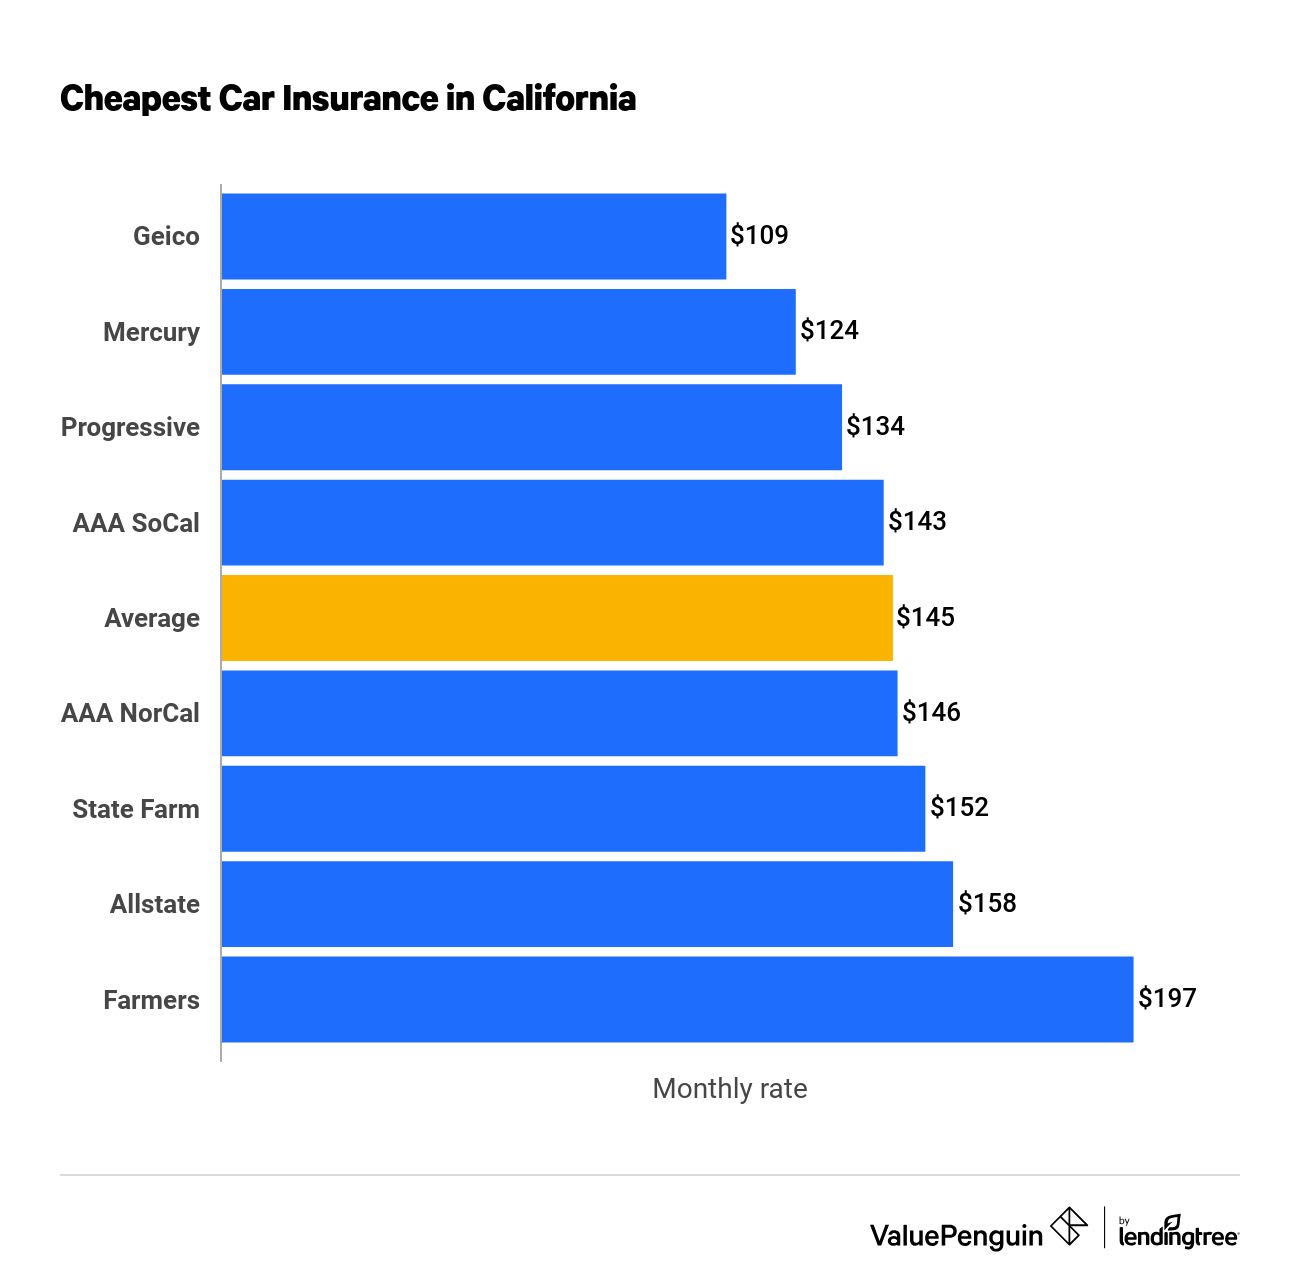
Finding the best auto insurance in Yorba Linda for 2026 requires balancing California’s evolving regulatory landscape with the specific needs of suburban Orange County commuters. For most everyday drivers, the top-tier options are the Auto Club of Southern California (AAA), Wawanesa, and State Farm, as they offer the most competitive rates and reliable claims processing for the high-traffic conditions common in the 92886 and 92887 zip codes.
The Yorba Linda Driving Landscape in 2026
Yorba Linda, often referred to as the "Land of Gracious Living," presents a unique set of variables for auto insurance. While the city itself maintains a reputation for safety and well-maintained residential streets, the typical "everyday driver" in this area is frequently subjected to the high-risk environments of the Riverside Freeway (SR-91) and the 241 Toll Road.
By 2026, the California insurance market has reached a new stage of stability following the Department of Insurance’s Sustainable Insurance Strategy. However, premiums in Orange County remain reflective of high vehicle repair costs and the density of the surrounding Los Angeles-bound commute. Drivers in Yorba Linda must account for high-value vehicle concentrations, which increases the likelihood of encountering expensive property damage claims.
The Impact of Zip Codes: 92886 vs. 92887
Insurance providers distinguish between the two primary zip codes in Yorba Linda.
- 92886 (Central/West): This area typically sees slightly lower premiums due to its proximity to established infrastructure and lower susceptibility to the specific environmental risks found further east.
- 92887 (East/Bryant Ranch): Drivers in this zip code may see variations in their comprehensive coverage rates. Because portions of 92887 border the Cleveland National Forest and wildland-urban interfaces, insurers sometimes factor in the increased risk of environmental hazards or specific road conditions related to the Santa Ana Canyon.
Top-Rated Insurers for Everyday Drivers in Yorba Linda
Selecting the right provider involves looking beyond the lowest monthly premium. For an everyday driver, the quality of the claims app, the availability of local agents near Yorba Linda Boulevard, and the speed of roadside assistance are critical factors.
1. Auto Club of Southern California (AAA)
The Auto Club remains a dominant force in Yorba Linda for 2026. Because AAA operates as a mutual organization in Southern California, its interests are often better aligned with long-term policyholders than stock-held companies.
- Why it fits: The legendary roadside assistance is almost a necessity for those commuting through the "Santa Ana Canyon" stretch of the 91 freeway, where breakdowns can be hazardous.
- Best for: Families with multiple vehicles and drivers who value a local physical branch for service.
2. Wawanesa Insurance
Historically a favorite for "good drivers" in California, Wawanesa continues to offer some of the most competitive rates in Orange County for 2026.
- Why it fits: Wawanesa utilizes strict underwriting. If you have a clean driving record and live in a low-crime area like Yorba Linda, you aren't "subsidizing" higher-risk drivers.
- Best for: Drivers with zero accidents or tickets in the last three to five years who want a no-frills, high-value policy.
3. State Farm
With one of the largest networks of local agents in the 92886 zip code, State Farm offers a personalized experience that many Yorba Linda residents prefer.
- Why it fits: Their "Drive Safe & Save" program has become highly sophisticated by 2026, allowing everyday drivers to leverage the safety of Yorba Linda’s residential streets to lower their premiums via telematics.
- Best for: Drivers who want a dedicated agent to manage their bundled home and auto policies.
4. Progressive
Progressive remains a leader for drivers who utilize technology to manage their policies.
- Why it fits: For the everyday driver who may have a minor incident on their record, Progressive’s Name Your Price tool and competitive rates for "mid-tier" credit and driving profiles make it a viable alternative to the stricter mutual companies.
- Best for: Tech-savvy commuters and those looking for competitive rates on Teslas and other electric vehicles (EVs) common in the area.

Essential Coverage Levels for Orange County Commuters
California state law requires minimum liability limits of 15/30/5 ($15,000 per person for bodily injury, $30,000 per accident, and $5,000 for property damage). However, for an everyday driver in Yorba Linda in 2026, these limits are dangerously inadequate.
Recommended Liability Limits
Given that the median vehicle value in Yorba Linda is significantly higher than the national average, a $5,000 property damage limit could be exhausted by a minor fender-bender with a modern luxury SUV or EV. Professionals recommend a minimum of 100/300/100. This covers $100,000 per person, $300,000 per accident, and $100,000 for property damage.
Uninsured/Underinsured Motorist Coverage (UM/UIM)
Despite strict laws, California continues to have a high percentage of uninsured drivers. In the event of a collision on the 91 or 57 freeways, UM/UIM coverage ensures that your medical bills and vehicle repairs are covered even if the at-fault party lacks insurance.
Comprehensive and Collision
For everyday drivers with vehicles less than ten years old, maintaining both comprehensive (theft, fire, vandalism) and collision is standard. In Yorba Linda, comprehensive coverage is particularly useful for glass damage, which is common for commuters dealing with construction debris on the 91 freeway.
Comparison of Top Insurance Providers in Yorba Linda (2026)
| Provider | Best Known For | Typical Discounts Available | Ideal Driver Profile |
|---|---|---|---|
| AAA (SoCal) | Roadside & Reliability | Multi-policy, Member loyalty | Families & Long-term residents |
| Wawanesa | Low Premiums | Good Driver (California mandated) | Clean records, No accidents |
| State Farm | Local Agent Service | Drive Safe & Save, Student away | Bundled Home/Auto owners |
| Progressive | Tech & Flexibility | Snapshot, Online quote | Commuters with newer EVs |
| GEICO | Efficiency | Military, Government employee | Budget-conscious professionals |
Factors Influencing 2026 Rates in Yorba Linda
Several hyper-local factors influence what you will pay for auto insurance in this part of Orange County.
The "91 Freeway Factor"
Insurers look at the primary route of your commute. If your daily drive involves the 91 freeway toward Corona or the 55 toward Irvine, your risk profile increases. Statistics show a higher frequency of low-speed rear-end collisions in these congested corridors. Drivers who can prove they use surface streets or work from home often see a "low-mileage" discount.
Vehicle Safety and Theft Rates
Yorba Linda has one of the lowest vehicle theft rates in the state. This keeps the "comprehensive" portion of your insurance premium lower than it would be in neighboring cities like Anaheim or Fullerton. Furthermore, the high adoption of vehicles with Advanced Driver Assistance Systems (ADAS) in the area helps lower the frequency of claims, though it does increase the cost of repairs when they occur.
The California "Good Driver" Discount
Under California Proposition 103, which remains the cornerstone of state insurance law in 2026, insurers must offer a 20% discount to drivers who have been licensed for at least three years and meet specific safety criteria. In a high-cost environment like Orange County, ensuring you qualify for this discount is the most effective way to manage costs.
Common Mistakes to Avoid
When shopping for insurance in Yorba Linda, everyday drivers often fall into traps that can lead to either overpaying or being under-insured.
- Setting Deductibles Too Low: Many drivers keep a $250 deductible. Raising this to $500 or $1,000 can reduce your annual premium by 15-20%. In a safe city like Yorba Linda, where the risk of non-collision damage is lower, a higher deductible often makes financial sense.
- Ignoring Telematics: By 2026, privacy concerns regarding tracking devices have largely been addressed by stricter California data laws. Programs like State Farm's "Drive Safe & Save" or Progressive's "Snapshot" can offer significant savings for Yorba Linda drivers who avoid late-night driving and hard braking.
- Underestimating the Value of an Independent Agent: While "direct-to-consumer" brands like GEICO are popular, local independent agents in Yorba Linda can often shop multiple "B-rated" or regional carriers that the average consumer cannot access.
How to Verify Your Policy and Provider
Before signing a new policy, it is essential to verify the standing of the company with the California Department of Insurance (CDI). The CDI provides a "Complaint Index" that shows how many complaints a company receives relative to its size. For a city with high standards like Yorba Linda, choosing a company with a low complaint index ensures that if you do have a claim, it will be handled with the "gracious" service the city is known for.
Additionally, checking the financial strength of an insurer through AM Best is recommended. You want a company with an "A" rating or higher to ensure they have the capital to pay out claims following large-scale events, such as the wildfires that occasionally threaten the canyon areas of Orange County.
FAQs About Yorba Linda Auto Insurance
Does living in a gated community in Yorba Linda lower my insurance?
While living in a gated community may slightly reduce the risk of vehicle theft or vandalism—impacting your comprehensive coverage—it generally does not have a massive effect on your overall premium. Insurers are more concerned with your driving record and your daily commute on public roads.
How does the 2026 California Sustainable Insurance Strategy affect my Yorba Linda policy?
The strategy was designed to ensure that insurers remain in the California market by allowing them to use "forward-looking" catastrophe models for rate setting. For Yorba Linda drivers, this means rates are more stable than they were in the 2023-2024 period, but they are more accurately priced for risks like wildfire and high-cost tech repairs.
What is the average cost of auto insurance in Yorba Linda for 2026?
While rates vary wildly based on the driver, the average everyday driver in Yorba Linda (age 35-50, clean record, mid-sized SUV) can expect to pay between $1,800 and $2,600 per year for a full-coverage policy with 100/300/100 limits.
Can I get a discount for taking a defensive driving course in Orange County?
Yes, many insurers, including AAA and State Farm, offer discounts for drivers (especially those over 55) who complete a California-certified mature driver improvement course. For younger drivers, "Good Student" discounts are also widely available for students at Yorba Linda High School or Esperanza High School.
Is "Gap Insurance" necessary for Yorba Linda drivers?
If you are financing a new car or leasing one—which is very common among Yorba Linda residents—Gap insurance is highly recommended. Because new cars depreciate quickly, if your car is totaled on the 91 freeway, your standard insurance will only pay the "Actual Cash Value." Gap insurance covers the difference between that value and what you owe on your loan.
Final Recommendation for Everyday Drivers
For the best experience in 2026, everyday drivers in Yorba Linda should start by requesting quotes from the Auto Club of Southern California and Wawanesa. These two providers consistently offer the best balance of local service and competitive pricing for the Orange County demographic. If you have a high-value home in the 92887 zip code, ask about a "Personal Umbrella Policy," which extends your liability coverage across both your home and auto, providing an extra layer of protection for your assets in one of California’s most affluent communities.
Image Gallery
Select an image to open it in a new tab.

Akira Tanaka
International Academic Trends Correspondent
