Why the Auto Insurance Rankings by State Matter for Drivers
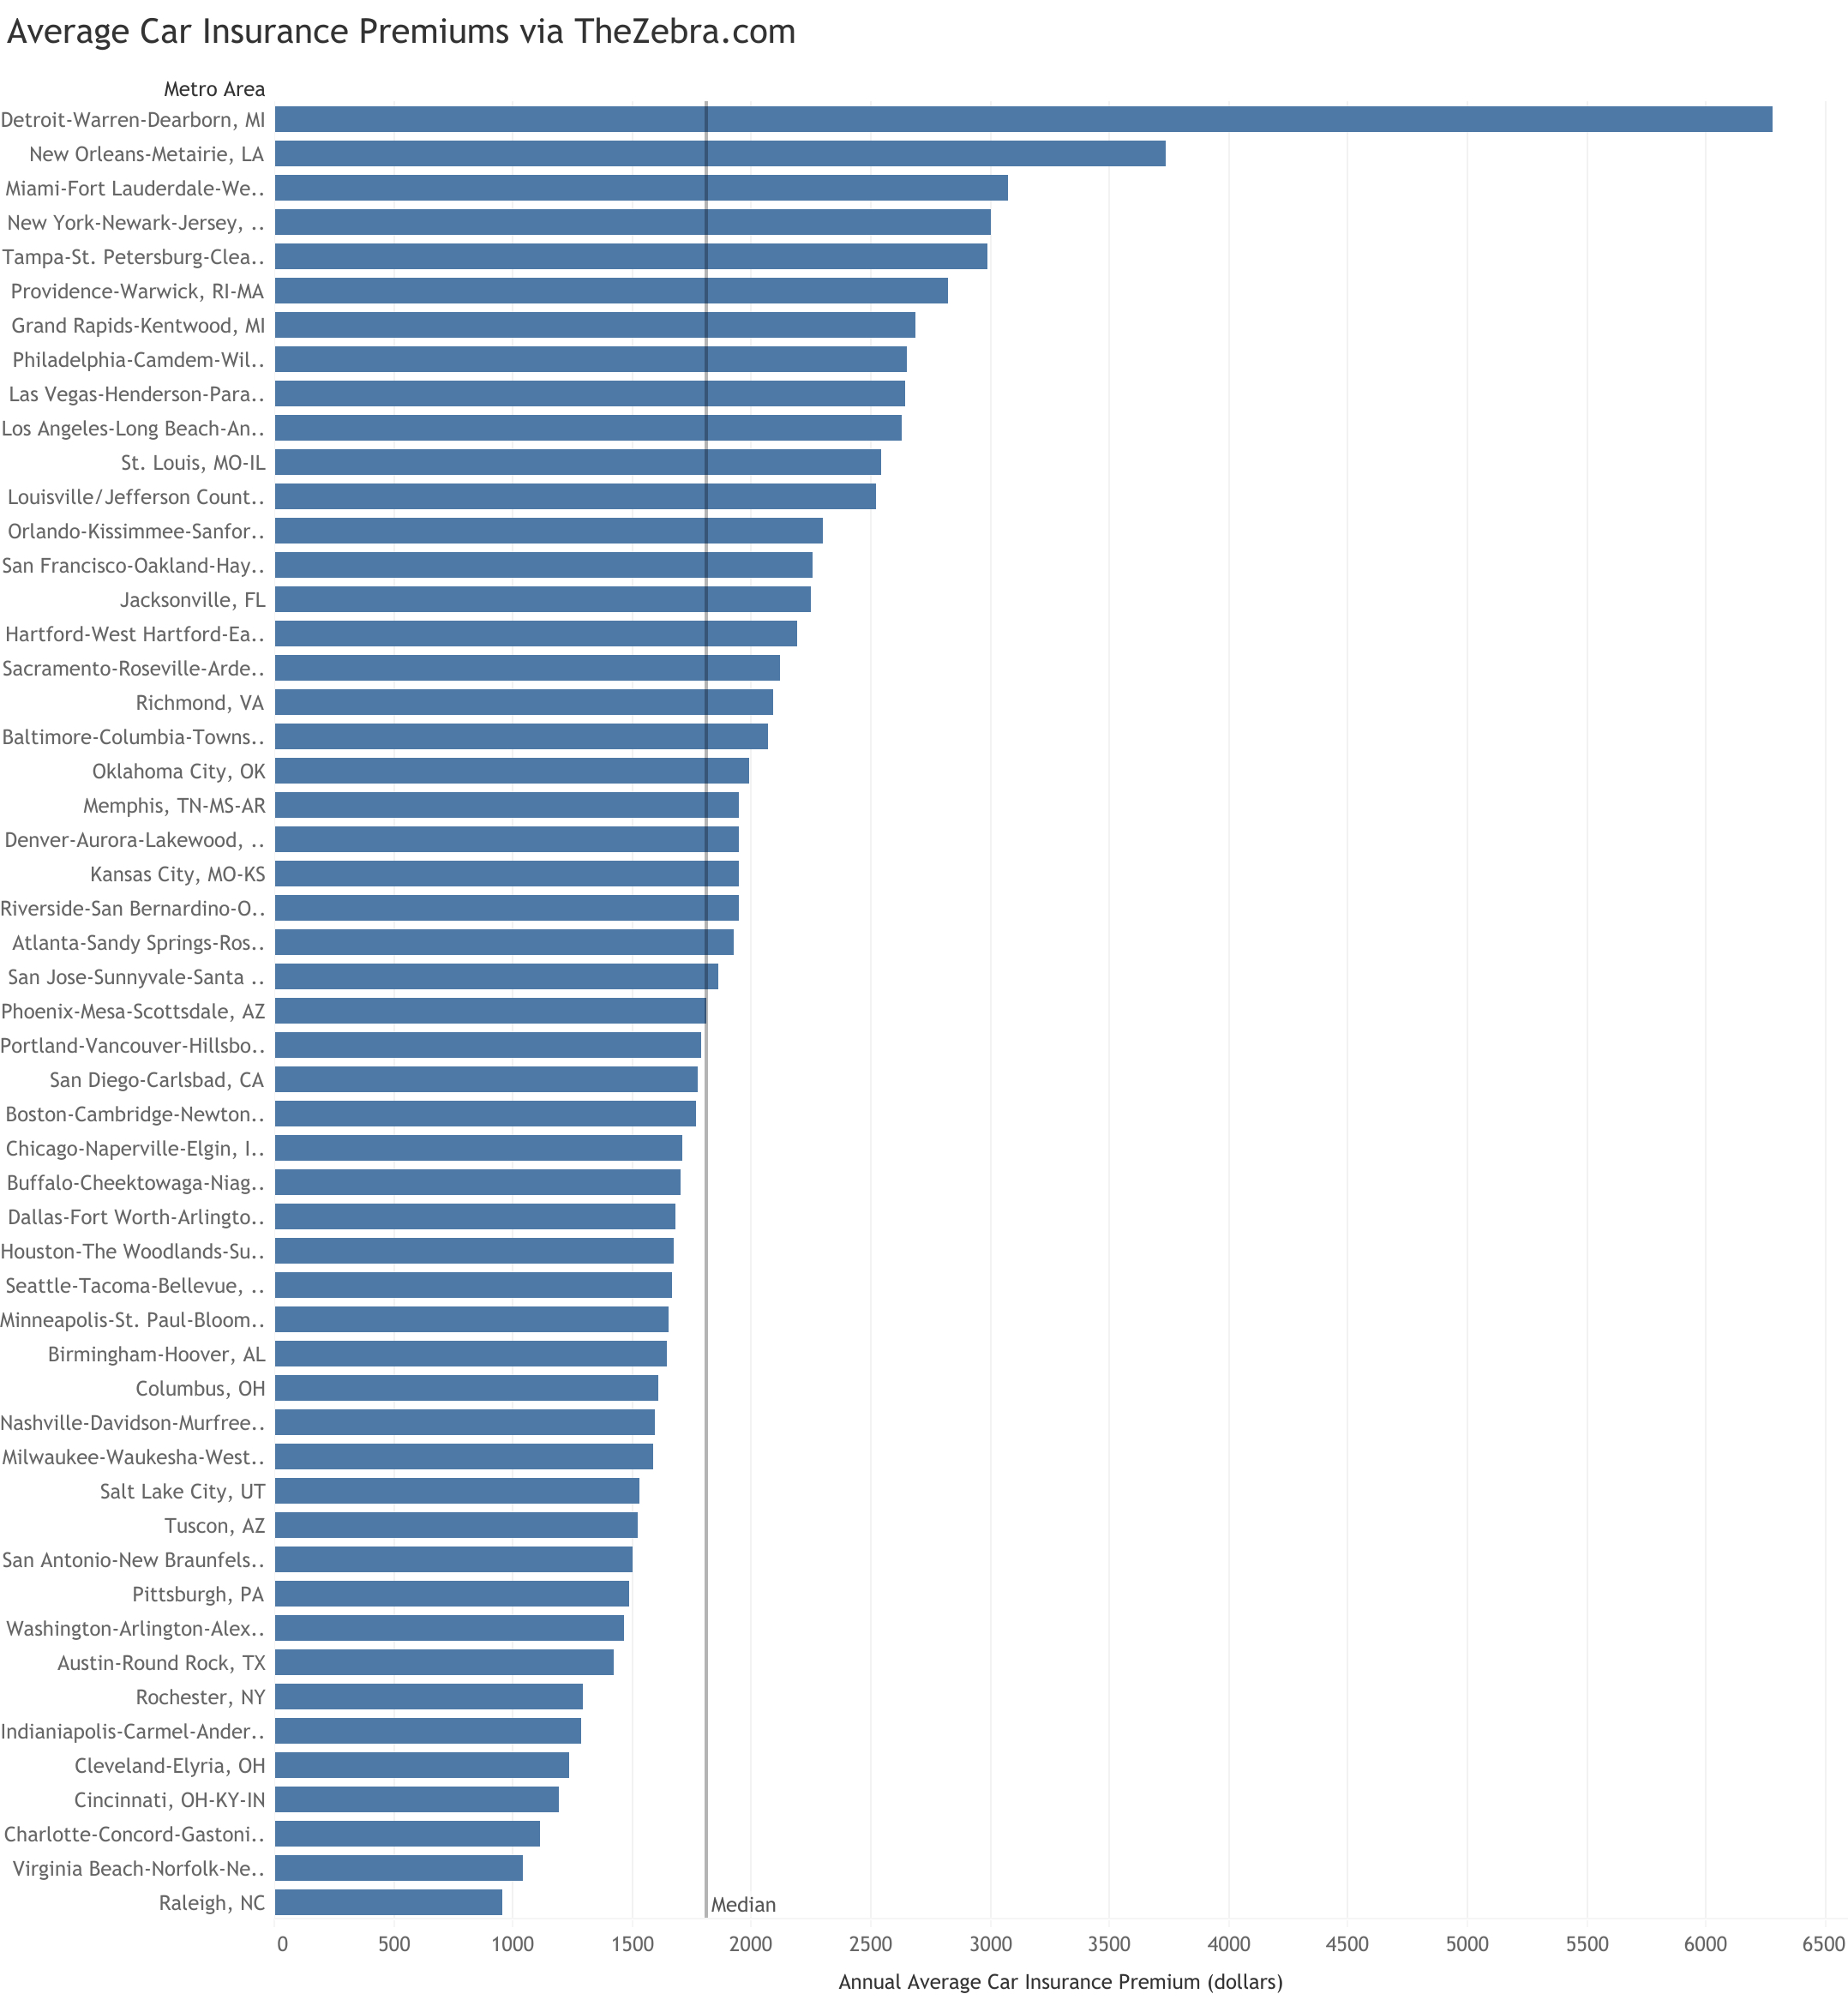
Auto insurance rankings by state provide a standardized metric for evaluating the average cost of coverage, regulatory environments, and the competitive landscape of the insurance market. By analyzing these rankings, drivers gain transparency into how their geographic location influences premium volatility, mandatory coverage minimums, and the financial stability of regional insurers, enabling more informed purchasing and budgeting decisions.
Understanding the Mechanics of State-Based Insurance
Auto insurance is not a singular, national product; it is a highly localized service governed by state-specific statutes. When you examine auto insurance rankings, you are effectively looking at the intersection of state law, population density, climate risk, and local economic factors. Each state's department of insurance sets specific guidelines regarding minimum liability coverage, no-fault versus tort systems, and how insurers are permitted to calculate risk based on credit history or driving records.
Because these regulations vary so drastically across state lines, a policy that is considered affordable in a low-density rural state might be prohibitively expensive in a state with high litigation rates or severe weather patterns. Rankings serve as a macro-level diagnostic tool, allowing drivers to see where their state stands in relation to national averages. This context is vital because it helps distinguish between an individual "bad deal" and a broader, systemic issue prevalent in your specific jurisdiction.
Key Factors Influencing State Rankings
Rankings are rarely based on a single variable. Instead, they are typically synthesized from several weighted data points that reflect the realities of the market in 2026. Understanding these components is essential for interpreting why your state might rank high or low on a comparative list.
1. Regulatory Environment and Tort Laws
States operate under either "at-fault" or "no-fault" insurance systems. In no-fault states, your own insurance company covers your medical bills regardless of who caused the accident, which often leads to higher mandatory premiums. Rankings often penalize or reward states based on how these laws influence total payouts.
2. Risk Profiles and Climate
States with higher incidences of catastrophic events—such as wildfires, hurricanes, or hailstorms—frequently occupy the higher end of cost rankings. Insurers factor in the probability of "total loss" claims, which are passed on to consumers in the form of higher premiums.
3. Litigation and Healthcare Costs
In some regions, the legal environment is more conducive to lawsuits following minor accidents. When legal costs and medical expenses are inflated, the insurance pool must adjust accordingly. Rankings that account for these trends provide a clearer picture of why certain states remain perpetually expensive.
4. Traffic Density and Infrastructure
The sheer number of vehicles on the road in a given state directly correlates to accident frequency. Urban centers with high traffic congestion consistently rank poorly in terms of affordability, as the probability of collision—and subsequently, the volume of claims—is statistically higher.
Comparative Market Analysis
To better understand how these rankings function, it is useful to view the landscape through a comparative lens. The following table illustrates the conceptual differences between high-rank (generally more affordable/stable) and low-rank (generally more expensive/volatile) states based on typical market drivers.
| Feature | Low-Cost States (Top Ranked) | High-Cost States (Lower Ranked) |
|---|---|---|
| Regulation | Consumer-friendly, stable rates | High litigation, complex mandates |
| Density | Low population/sparse traffic | High urban density/congestion |
| Risk Factors | Minimal weather-related events | Frequent natural disasters |
| Legal System | Limited tort or restrictive liability | Broad "at-fault" litigation risk |
| Claim Volume | Lower frequency of claims | High frequency and higher severity |
The Role of Transparency in Consumer Choice
For the individual driver, the primary value of state-level rankings is the removal of information asymmetry. Without these rankings, a consumer might assume that a premium increase is the result of a personal driving record or an arbitrary decision by their insurer. When a driver knows their state is ranked as having the highest average premiums due to systemic issues like "litigation-heavy courts," they can approach their insurance agent with more relevant questions.
Furthermore, these rankings allow consumers to identify "market outliers." If a state is ranked as highly expensive, but a specific insurer maintains competitive rates within that same state, it signals an opportunity to shop for coverage that performs better than the regional average. This knowledge empowers consumers to act as intelligent market participants rather than passive recipients of rising premiums.
Limitations and Nuances in Data Interpretation
While rankings are valuable, they are not absolute predictors of what you will pay. A common mistake is to assume that because a state is ranked "cheap," every policy in that state will be inexpensive. This is incorrect. Insurance companies utilize granular, individual-level data—known as "actuarial underwriting"—that supersedes state averages.
Your specific credit score, vehicle safety rating, annual mileage, and parking location provide a more precise calculation of your risk than a statewide average ever could. Use rankings as a compass for the general environment, but rely on personalized quotes for your actual financial planning. Additionally, always verify the source of the ranking. In 2026, ensure that the data comes from a reputable regulatory body or a transparent, independent research firm, rather than an entity with a clear conflict of interest, such as an insurance carrier marketing its own low-cost policies.
When Rankings Influence Personal Decisions
Drivers often ask if they should use these rankings to make life-altering decisions, such as moving to a different state. While it is rarely advisable to choose a place of residence solely based on auto insurance, it is a legitimate component of the "cost of living" assessment. If you are comparing two potential cities near a state border, the difference in mandated coverage, minimum limits, and average premiums can result in hundreds of dollars of variance annually.
Strategic Next Steps for the Informed Driver:
- Verify State Minimums: Visit your state’s Department of Insurance website. Understand exactly what coverage is legally required versus what is recommended for financial protection.
- Analyze Local Trends: Look for news reports regarding regional insurance crises or legislative changes. If your state is undergoing a massive reform of its "no-fault" system, expect rate volatility regardless of the current ranking.
- Benchmark Your Rates: Once you know your state’s standing, compare your current premium against the state average. If you are significantly above that average, investigate why (e.g., credit-based insurance scoring or recent claims).
- Evaluate Insurer Stability: Rankings aren't just about cost; they are about security. Use financial strength ratings from agencies like A.M. Best to ensure that the insurers operating in your "low-cost" state are actually solvent and capable of paying out claims.
Frequently Asked Questions
Do state rankings account for my specific driving history? No. State rankings are aggregate metrics representing the average environment. They do not account for individual variables like your age, traffic violations, or the make and model of your vehicle, which remain the primary drivers of your personal premium.
If my state has a high ranking for cost, does that mean I cannot find affordable insurance? Not necessarily. A high average cost usually indicates systemic pressures on all insurers in the state. However, it does not mean every company is equally expensive. Shopping the market remains the most effective way to find lower-than-average rates, even in a "high-cost" state.
Are these rankings updated annually? Most reputable rankings are updated on a yearly basis to account for changing laws, inflationary pressures on auto repairs, and regional economic shifts. Always check the publication date of the data to ensure it reflects current 2026 conditions.
Should I change my coverage levels based on how my state ranks? Never lower your coverage levels just because a state ranks as "affordable." Your insurance exists to protect your assets. If you are in a state with high litigation risks, you may actually need more liability coverage than the state-mandated minimum, even if the general market is relatively inexpensive.
Why do some states have such vastly different insurance requirements? Insurance is regulated at the state level under the McCarran-Ferguson Act. This allows states to tailor their insurance markets to fit local needs, such as the unique traffic laws of an urban-dense state versus the rural, expansive driving environments of others.
Final Recommendation
The most effective way to utilize auto insurance rankings by state is to treat them as a baseline for your expectations rather than a final verdict on your costs. In 2026, use these rankings to gauge whether you are paying for the market conditions of your area or if you are overpaying for your specific risk profile. For the best outcome, combine this macro-level data with a direct, personal comparison of at least three quotes from insurers licensed to operate in your state, ensuring you maintain the coverage levels necessary to protect your financial future.

Image Gallery
Select an image to open it in a new tab.
Vivian Cho
Executive IT and Emerging Technologies Reporter
