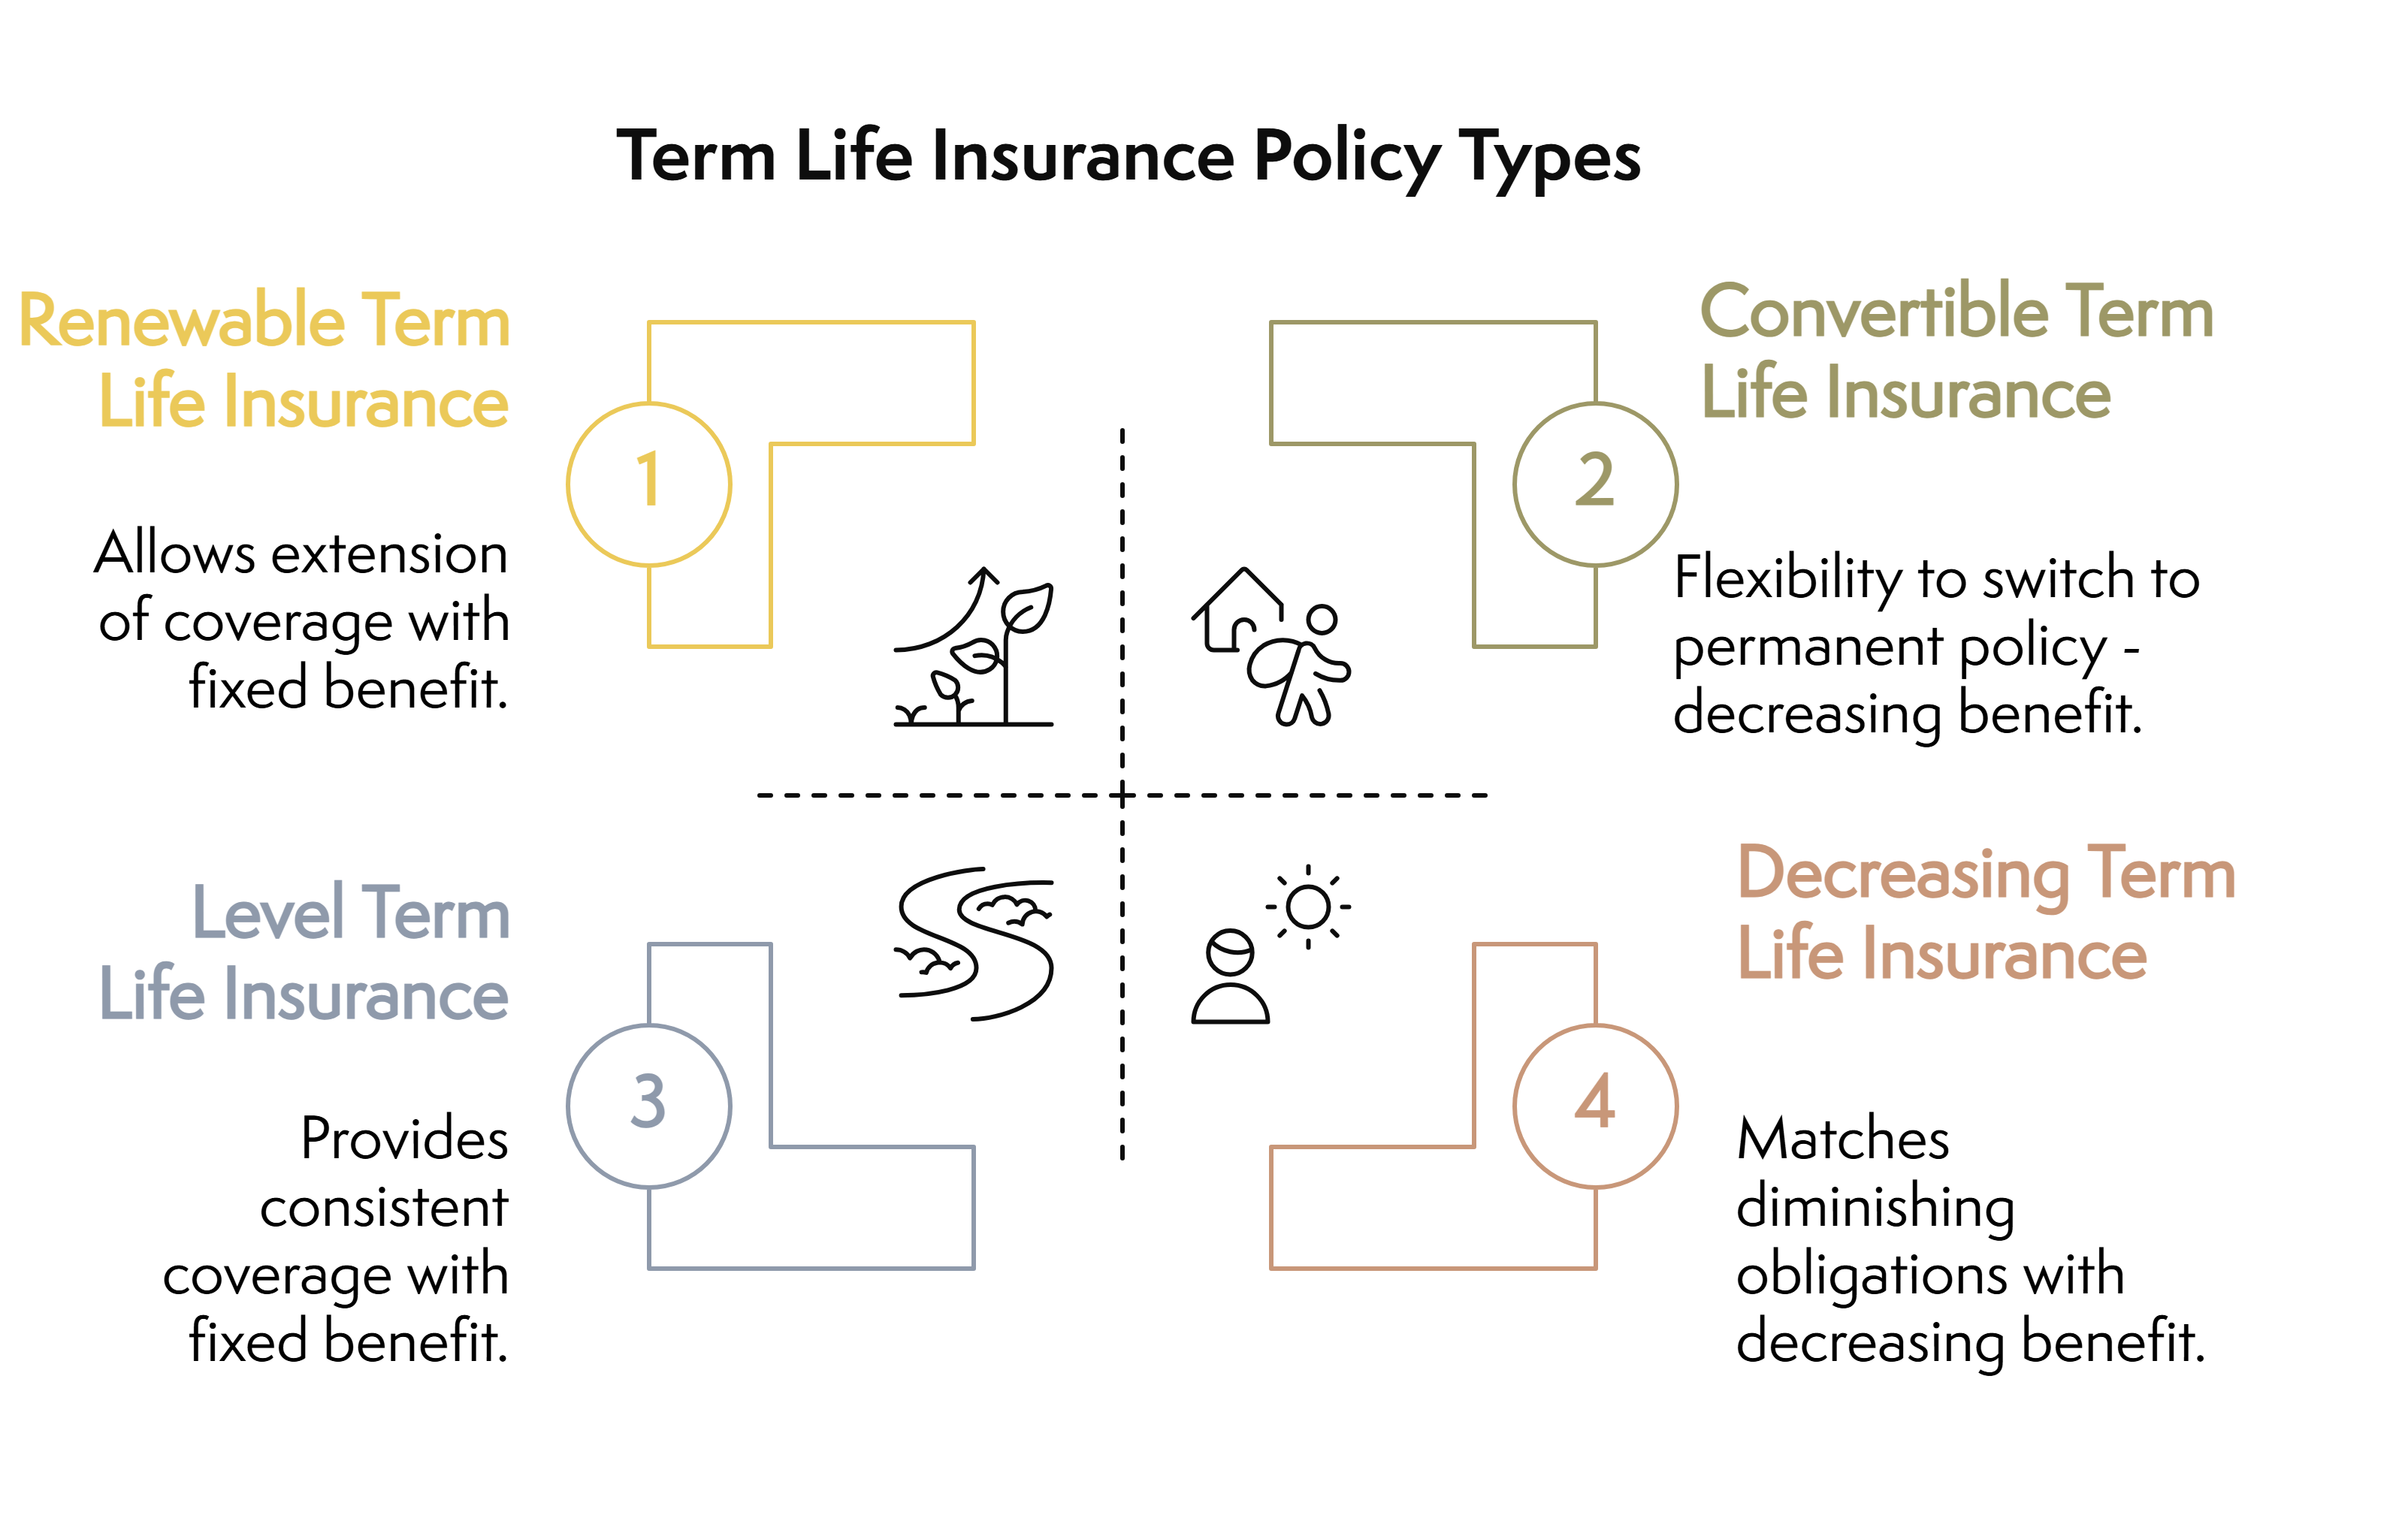
A 20-year term life insurance policy provides a fixed death benefit and level premiums for exactly two decades. It is a cost-effective financial tool designed to protect families during peak liability years, such as child-rearing or mortgage repayment, typically costing significantly less than permanent life insurance options while offering substantial coverage.
Understanding the Mechanics of 20-Year Term Life Insurance
Term life insurance is the most straightforward form of life insurance available. When you purchase a 20-year term policy, you are essentially entering into a contract with an insurer where they agree to pay a specific sum (the death benefit) to your beneficiaries if you pass away during the 20-year window. In exchange, you pay a set premium, which in 2026 remains largely "level," meaning the cost does not increase as you age or if your health declines during the term.
The 20-year duration is often considered the "sweet spot" of the insurance industry. It is long enough to cover the most critical financial years of a person's life—such as the time it takes for a newborn to reach adulthood or for a homeowner to pay down the bulk of a mortgage—but short enough to remain affordable. Unlike whole life insurance, term insurance does not have a "cash value" component. It is pure protection; if the 20 years pass and you are still living, the policy simply expires unless you choose to renew it or convert it to a permanent policy.
In the current 2026 market, many insurers have integrated advanced data analytics into these policies. This means that while the core product remains the same, the speed at which these policies are issued has increased. Many 20-year terms now utilize "accelerated underwriting," which leverages electronic health records and credit data to provide approvals in minutes rather than weeks, often without the need for a traditional medical exam for healthy applicants under age 50.
Who Does a 20-Year Term Policy Serve?
Identifying whether a 20-year term is appropriate requires an analysis of your "financial horizon." This policy serves specific demographics who have a clear end date for their largest financial obligations.
New Parents and Young Families
For parents of young children, a 20-year term is often the standard choice. If you have a one-year-old, a 20-year policy ensures that if the unthinkable happens, funds are available to support that child until they finish college and enter the workforce. It covers the "dependency window," providing for daily living expenses, childcare, and eventually, tuition.
Homeowners with 15- to 20-Year Mortgages
While 30-year mortgages are common, many homeowners opt for 15-year or 20-year fixed-rate loans. Aligning your life insurance term with your mortgage duration is a classic risk-management strategy. If the primary breadwinner passes away, the death benefit can be used to pay off the remaining balance of the home, ensuring the surviving family members can stay in their residence without the burden of a monthly housing payment.
Business Owners and Key Partners
In the business world, 20-year terms are frequently used for "buy-sell" agreements. If two partners start a business, they may each take out a 20-year policy on the other. If one partner dies during that time, the payout allows the surviving partner to buy out the deceased partner's heirs, maintaining business continuity. Since many businesses reach maturity or face a transition point within two decades, this term length is often ideal.
Individuals with Mid-Career Debt
For professionals who have taken on significant debt later in life—such as private student loans for advanced degrees or business expansion loans—the 20-year term provides a safety net. It ensures that these liabilities do not transfer to a spouse or co-signer if the borrower dies prematurely.
Analyzing the Costs in 2026
The cost of a 20-year term life insurance policy is determined primarily by the "mortality risk" the insurer assumes. In 2026, premium rates are influenced by several factors, including the higher interest rate environment which allows insurance companies to earn more on their reserves, potentially keeping premiums competitive despite general inflation.
Underwriting Classifications
Your "rate class" is the most significant driver of cost. Insurers generally categorize applicants into several tiers:
- Preferred Plus: Excellent health, no tobacco use, and a clean family medical history.
- Preferred: Great health, perhaps minor issues like well-controlled high blood pressure.
- Standard Plus/Standard: Average health, perhaps a higher Body Mass Index (BMI) or managed cholesterol.
- Substandard (Rated): Significant health issues like diabetes or heart disease.
The Impact of Age and Gender
Age is the most predictable factor in pricing. Every year you wait to purchase a policy, the premium increases by roughly 5% to 8%. Gender also plays a role; statistically, women have longer life expectancies than men, resulting in lower premiums for the same amount of coverage.
The following table illustrates estimated monthly premiums for a $500,000 20-year term policy for individuals in the "Preferred" health class in 2026.
| Age at Purchase | Monthly Premium (Male) | Monthly Premium (Female) |
|---|---|---|
| 25 | $22.50 | $18.75 |
| 35 | $28.40 | $24.10 |
| 45 | $58.90 | $46.30 |
| 55 | $145.20 | $108.50 |
| 65 | $410.00 | $295.00 |
Note: These are estimates based on standard 2026 actuarial trends and vary significantly by insurer and specific health profile.
Critical Policy Riders and Enhancements
When purchasing a 20-year term, you can often add "riders"—optional provisions that customize your coverage. While some add to the premium, others are included at no extra cost depending on the carrier.
- Accelerated Death Benefit: This is a crucial feature in 2026. It allows the policyholder to access a portion of the death benefit while still living if they are diagnosed with a terminal illness. This money can be used for medical bills or hospice care, providing "living benefits" to the insured.
- Waiver of Premium: If you become totally disabled and cannot work, this rider ensures your policy remains in force without you having to pay the premiums. In an era where long-term disability is a significant risk, this provides an extra layer of security.
- Conversion Rider: Most 20-year terms include a conversion option. This allows you to turn your term policy into a permanent (whole or universal) policy without undergoing a new medical exam. This is vital if your health declines during the 20-year term and you realize you will need insurance for the rest of your life.
- Child Term Rider: This provides a small amount of life insurance for all children in the household. It is an affordable way to cover funeral expenses or provide a "guaranteed insurability" option for the children when they become adults.
How to Determine If $500,000, $1 Million, or More is Needed
The "how much" question is as important as the "how long" question. A common mistake is choosing a round number without calculation. In 2026, inflation must be accounted for when projecting future needs.
A standard approach is the DIME formula:
- D (Debt): Total all debts, including your mortgage, car loans, and credit cards.
- I (Income): Multiply your annual income by the number of years your family would need support (e.g., 10 or 15 years).
- M (Mortgage): While included in debt, many prefer to isolate the primary residence balance.
- E (Education): Estimate the cost of college for all children.
If your DIME calculation totals $1.2 million, a $500,000 policy—while cheaper—leaves your family with a $700,000 shortfall. Because term insurance is relatively inexpensive, it is often better to over-insure slightly than to leave a gap that your beneficiaries cannot fill.
Comparing the 20-Year Term to Alternatives
It is helpful to view the 20-year term within the context of other available durations.
- 10-Year Term: Best for short-term needs, like a small business loan or if you are very close to retirement. It is the cheapest option but offers the least longevity.
- 30-Year Term: Ideal for young families starting a 30-year mortgage. It provides the longest protection but is significantly more expensive than a 20-year term because the insurer is statistically more likely to pay a claim as you reach your 50s and 60s.
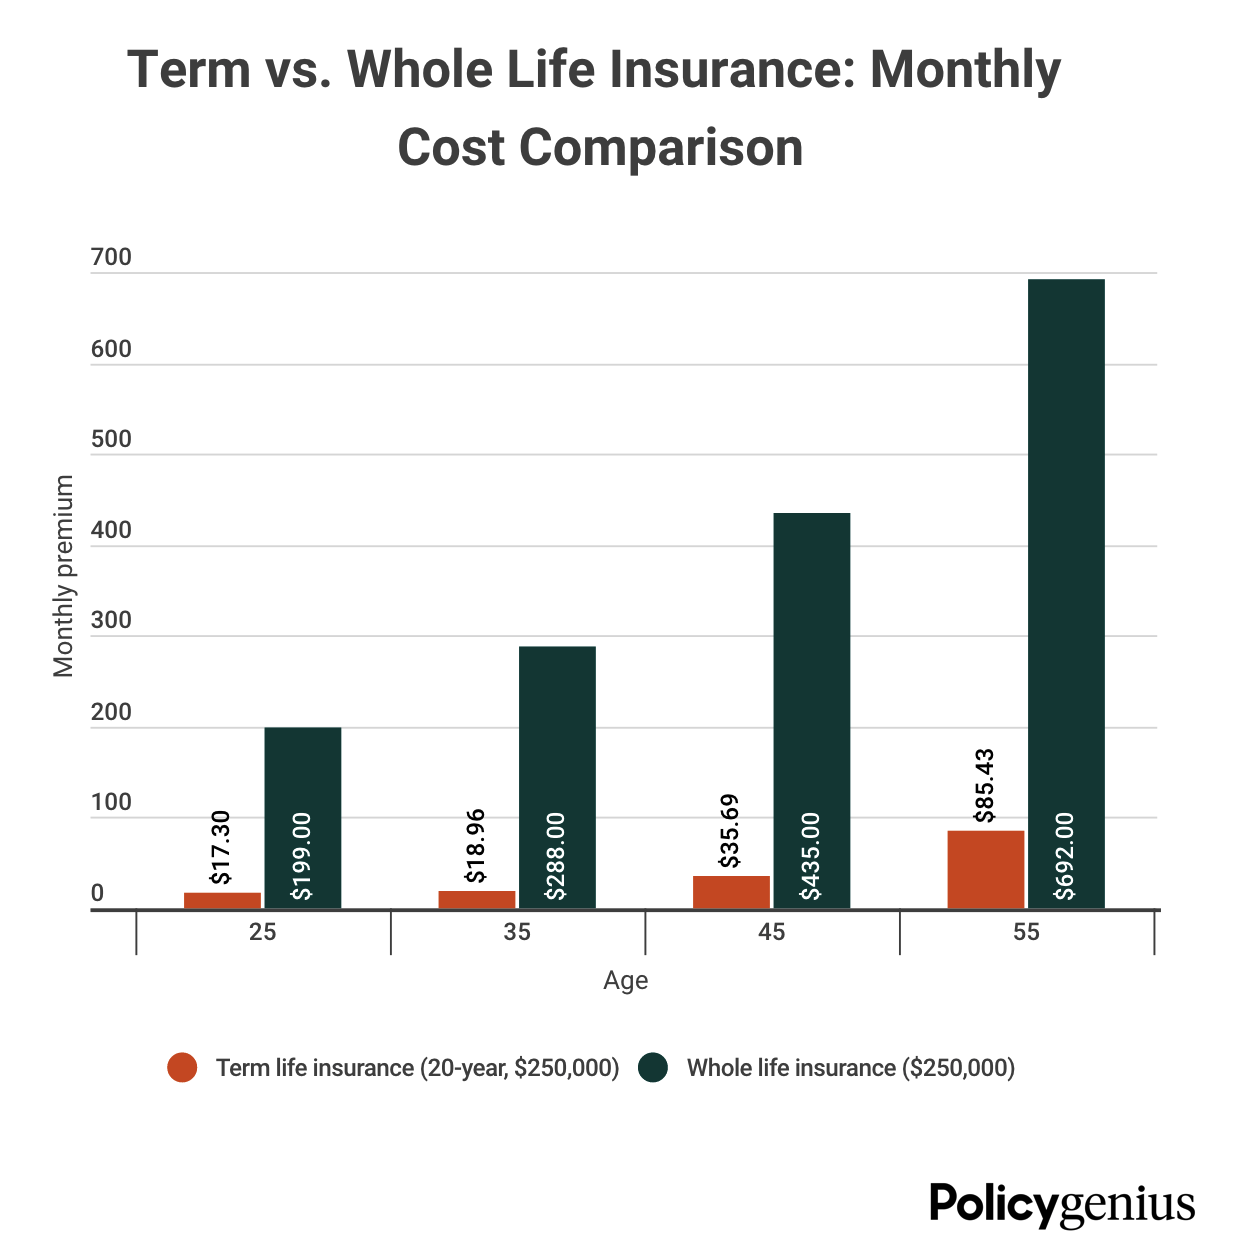
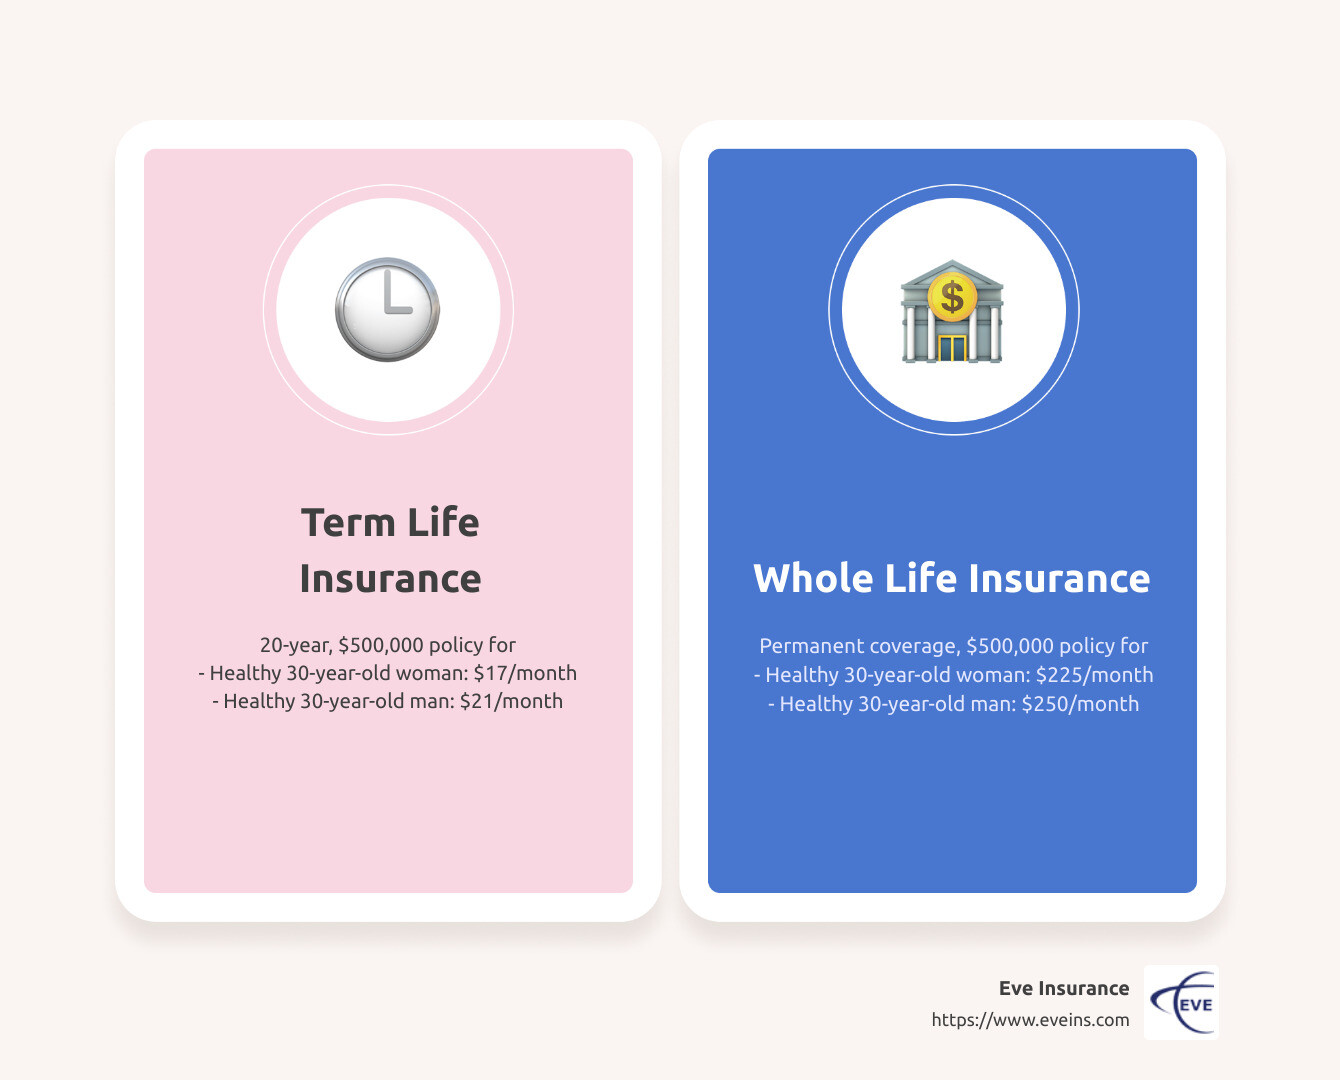
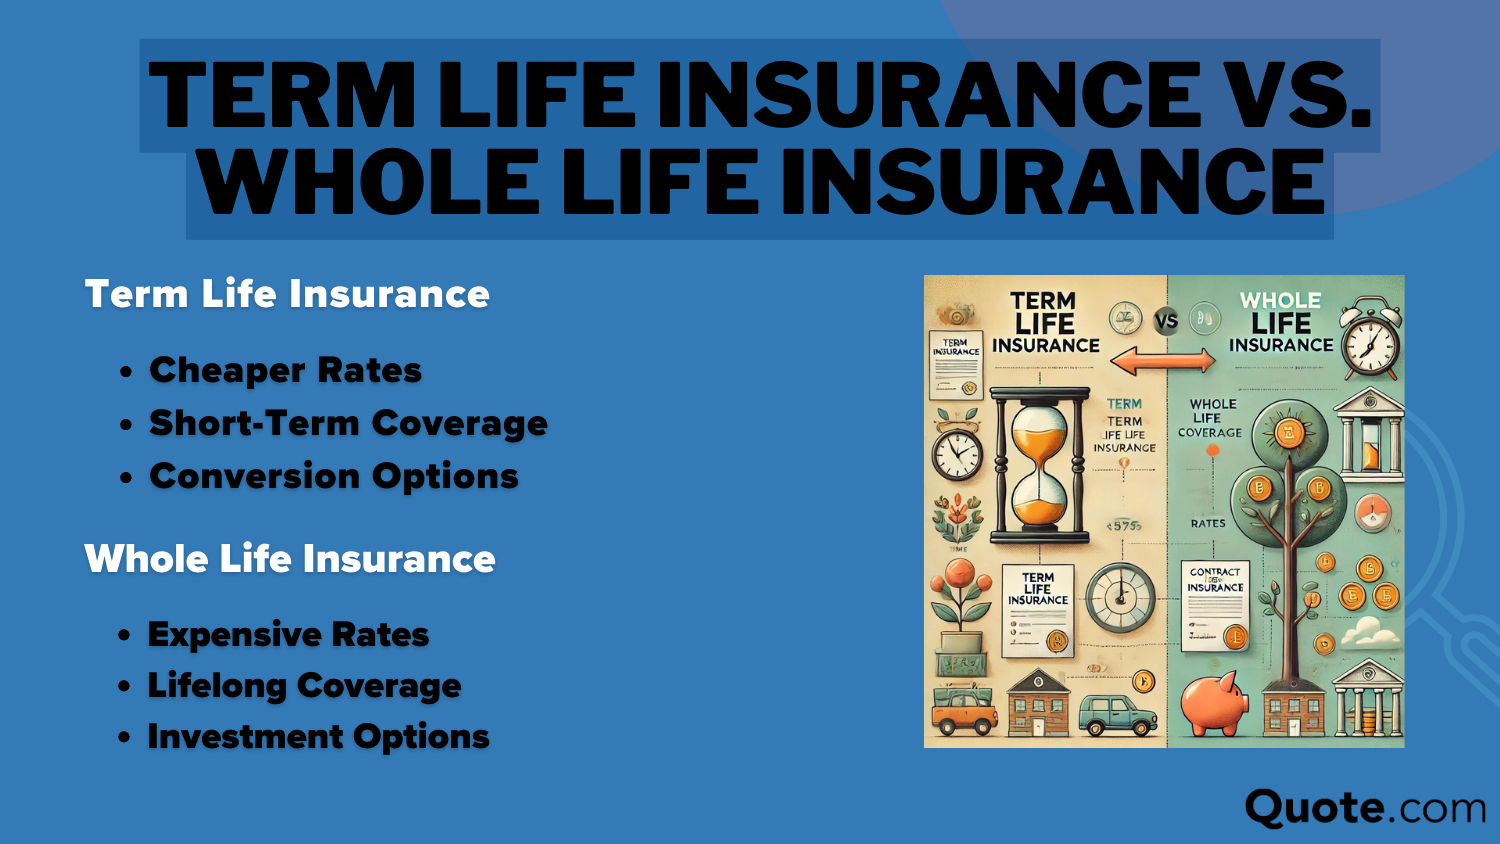
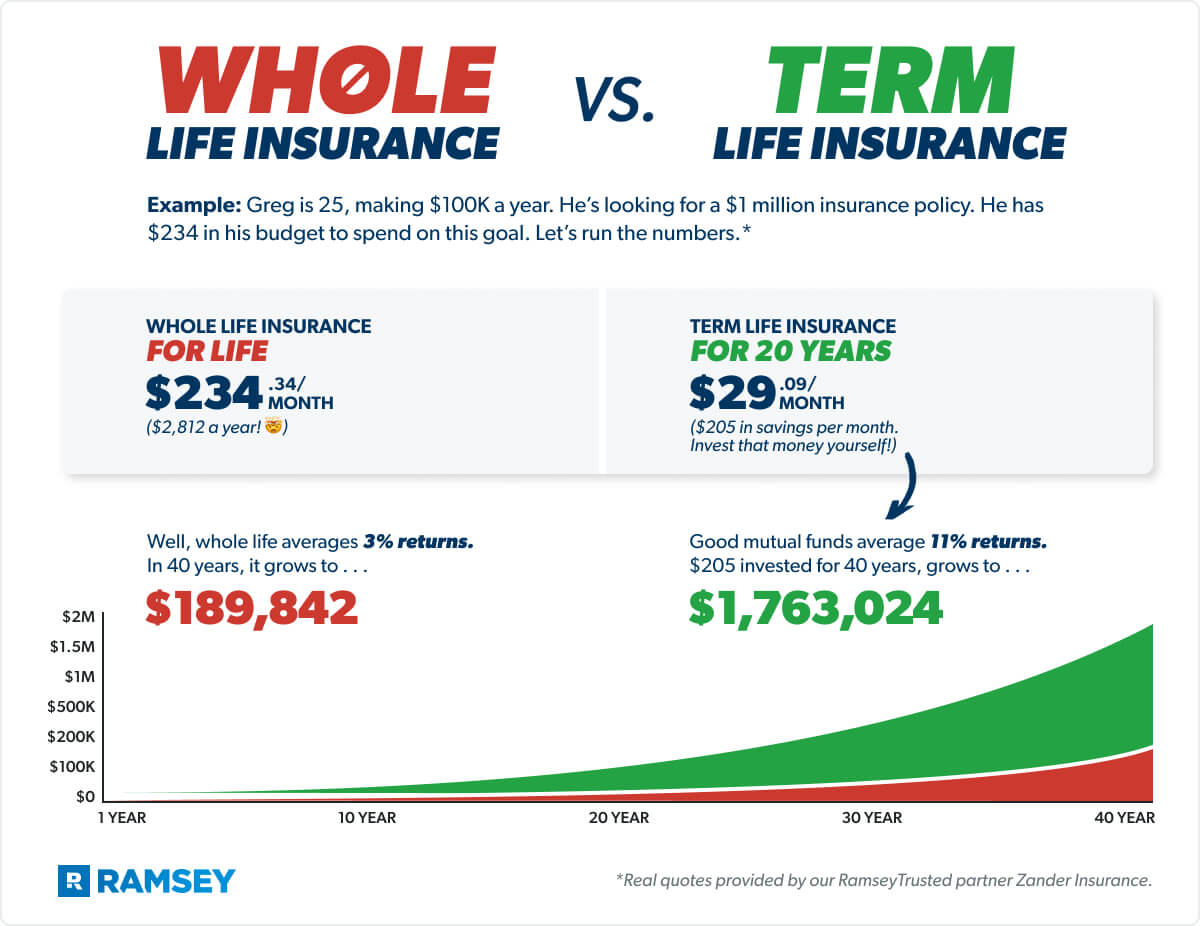
- Whole Life Insurance: This lasts your entire life and builds cash value. However, the premiums can be 10 to 15 times higher than a 20-year term for the same death benefit. For most families in 2026, "buying term and investing the difference" remains the more efficient wealth-building strategy.
Potential Pitfalls and Mistakes to Avoid
Even a straightforward product like 20-year term insurance has nuances that can lead to costly errors.
Waiting Too Long to Buy: Since premiums are locked in at the age of purchase, waiting five years to "see if you need it" can result in paying 30% more over the life of the policy. Furthermore, you risk developing a health condition that could make you uninsurable or move you into a higher rate class.
Underestimating the "Laddering" Strategy: Some savvy consumers use a laddering approach. Instead of one $1 million 20-year policy, they might buy a $500,000 20-year policy and a $500,000 10-year policy. This provides maximum coverage while the kids are young and the mortgage is high, but reduces the total premium cost as liabilities decrease over time.
Ignoring the Financial Strength of the Insurer: A life insurance policy is a long-term promise. In 2026, it is essential to check the ratings of your insurer through agencies like A.M. Best or Demotech. You want a company with an "A" rating or better to ensure they have the claims-paying ability two decades from now.
Frequently Asked Questions
What happens at the end of the 20 years?
When the 20-year term expires, the coverage ends. Most policies offer a "guaranteed renewability" clause, allowing you to continue coverage on a year-to-year basis. However, the premiums at that point will skyrocket because they are based on your age at age 50 or 60 rather than your original age. Most people either let the policy lapse (because their kids are grown and the house is paid off) or convert it to a permanent policy before the term ends.
Can I cancel a 20-year term policy before it expires?
Yes. You can cancel your policy at any time by simply stopping the premium payments. There are no penalties for canceling a term policy, but you will not receive any money back (unlike whole life insurance) because term insurance does not build cash value. You have essentially paid for protection for the months the policy was active.
Is a medical exam always required in 2026?
No. Many insurers now offer "no-exam" or "accelerated" underwriting for 20-year terms. If you are under a certain age (typically 50 or 55) and seeking coverage under $1 million or $2 million, the insurer may use your prescription history, motor vehicle records, and MIB (formerly Medical Information Bureau) reports to approve you instantly. However, if you have complex health issues, a traditional exam with bloodwork may still be required to get the best rate.
Does 20-year term life insurance cover suicide?
Almost all life insurance policies, including 20-year terms, have a "suicide clause." This clause typically states that if the insured commits suicide within the first two years of the policy, the death benefit will not be paid; instead, the insurer will refund the premiums paid. After the initial two-year period, suicide is generally covered like any other cause of death.
Can I change my beneficiaries during the 20-year term?
Yes, in most cases. Unless you have designated an "irrevocable beneficiary," you can change who receives the death benefit at any time by filing a form with the insurance company. It is recommended to review your beneficiaries every few years or after major life events like marriage, divorce, or the birth of a child.
Practical Recommendation: Taking the Next Step
If you have identified that a 20-year term life insurance policy aligns with your financial goals, the first step is to conduct a formal needs analysis. Do not guess your coverage amount; use a calculator provided by the National Association of Insurance Commissioners (NAIC) to determine your exact requirements.
Once you have a number, gather quotes from at least three different high-rated carriers. Because 2026 underwriting is highly specialized, one company might "favor" certain health conditions (like controlled Type 2 diabetes) more than another. If you have a unique health profile or a high-risk hobby (like scuba diving or private aviation), consider working with an independent broker who can shop your application to multiple insurers simultaneously to find the most aggressive pricing for your specific risk profile.
Image Gallery
Select an image to open it in a new tab.



Celine Dubois
Contemporary Living and Global Arts Columnist
