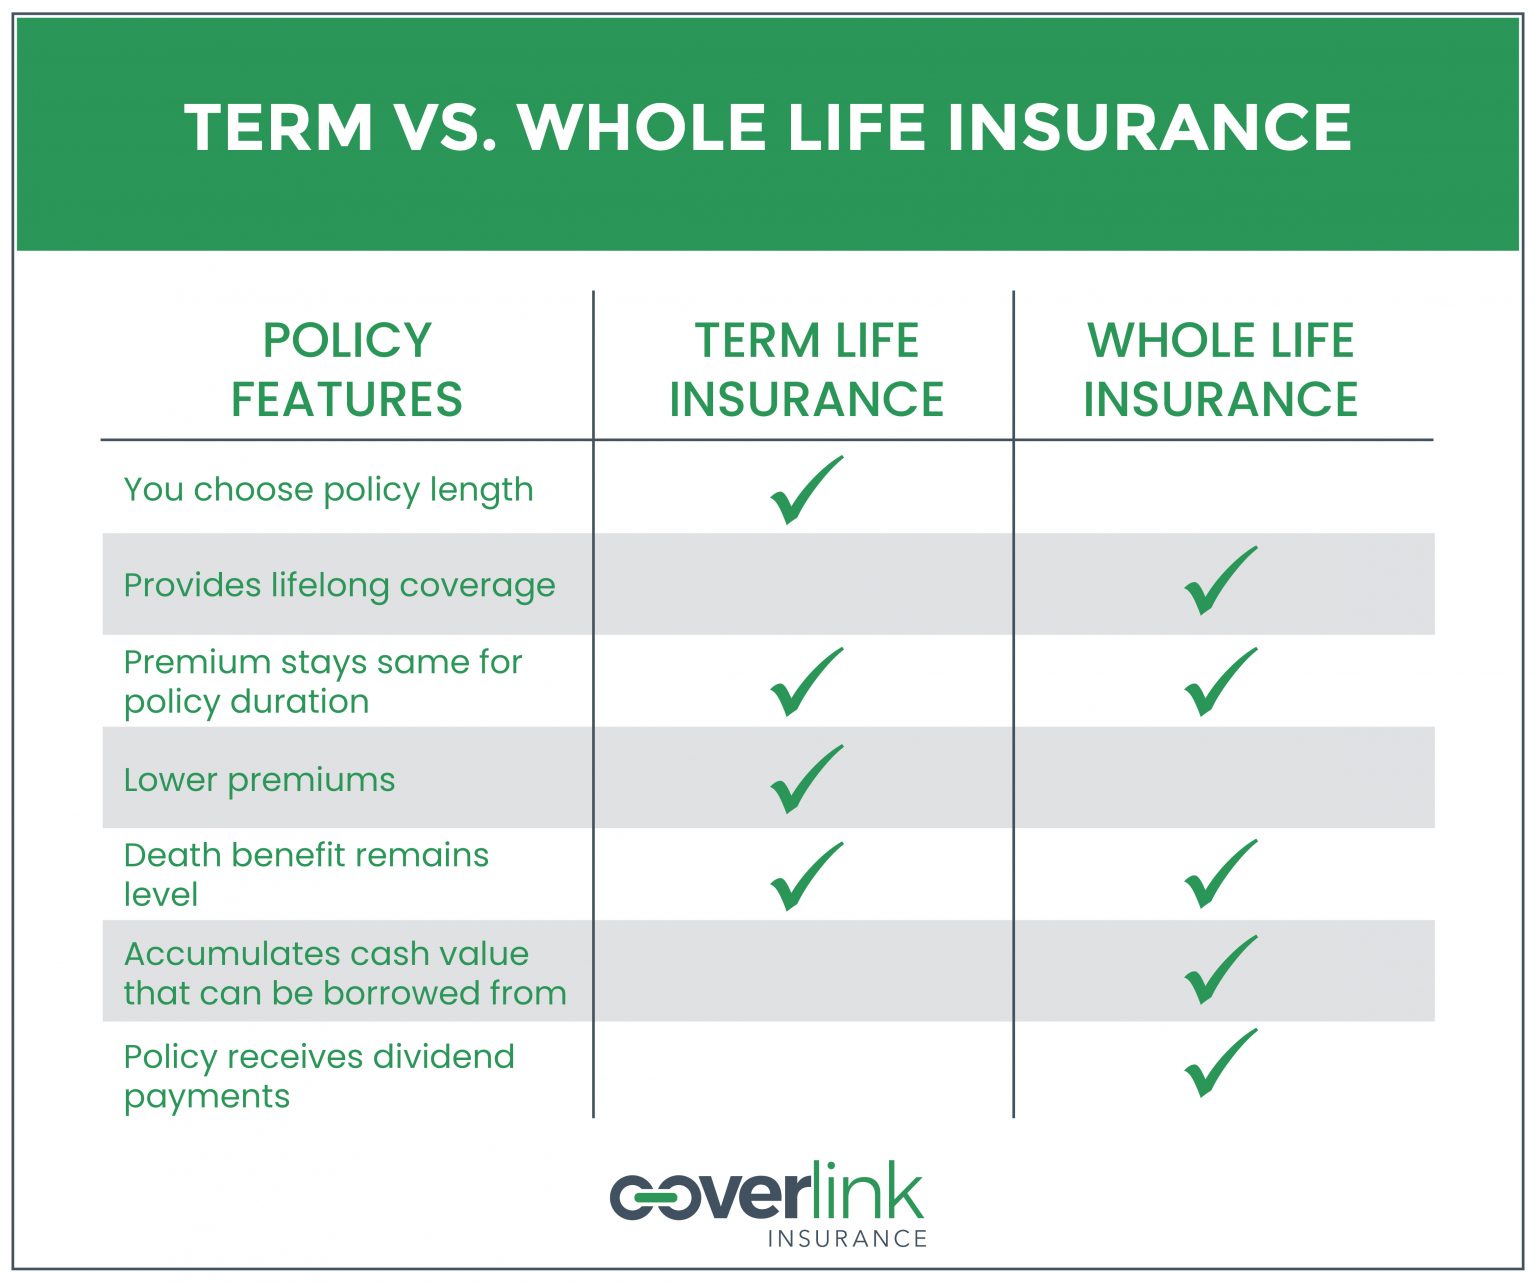
Choosing between whole and term life insurance requires balancing immediate affordability against long-term financial goals. In 2026, term life insurance remains the most cost-effective solution for temporary needs like mortgages and child-rearing. Conversely, whole life insurance serves as a permanent asset with a guaranteed death benefit and a growing cash value component suitable for estate planning.
Deciding on a life insurance policy is one of the most significant financial decisions a household can make. As we navigate the economic landscape of 2026, the distinction between "protection" and "investment" has become increasingly defined. This consumer report provides an objective analysis of the two primary forms of life insurance, evaluating their mechanics, cost structures, and suitability for various demographic profiles. By understanding the underlying architecture of these products, consumers can avoid common marketing traps and select coverage that aligns with their actual risk profile.
The Fundamentals of Term Life Insurance
Term life insurance is the simplest and most accessible form of life insurance. It provides coverage for a specific period—typically 10, 15, 20, or 30 years. If the insured individual passes away during this "term," the insurance company pays a death benefit to the designated beneficiaries. If the term expires and the insured is still living, the coverage simply ends unless the policyholder chooses to renew it or convert it to a permanent policy.
Mechanics of Level Term Policies
Most modern term policies are "level term," meaning the premium stays exactly the same for the duration of the contract. In 2026, many carriers have refined their "algorithmic underwriting," allowing healthy individuals to secure these rates in minutes without a traditional medical exam. The primary advantage of the level premium is predictability; a 30-year-old can lock in a rate that will remain the same until they are 60, regardless of changes in their health.
Why Consumers Choose Term Life
The primary driver for term insurance is the "death benefit per dollar" ratio. Because term insurance has no cash value and most policies do not result in a claim (statistically, most people outlive their terms), the premiums are significantly lower than permanent options. This allows young families to secure large death benefits—often $1 million or more—for a fraction of the cost of a smaller whole life policy. It is ideally suited for "dwindling" liabilities, such as a mortgage that will eventually be paid off or children who will eventually become financially independent.
The Architecture of Whole Life Insurance
Whole life insurance is a type of permanent life insurance that remains in force for the insured's entire life, provided premiums are paid. Unlike term insurance, whole life combines a death benefit with a savings component known as "cash value."
How Cash Value Accumulates
A portion of every premium payment in a whole life policy is funneled into a cash value account. This account grows at a guaranteed rate set by the insurance company. In 2026, as interest rates have stabilized, many mutual insurance companies are also paying out non-guaranteed dividends to policyholders, which can be used to increase the death benefit, pay premiums, or be taken as cash.
The cash value is "tax-deferred," meaning you do not pay taxes on the growth as it accumulates. Policyholders can also take loans against the cash value, providing a source of liquidity that does not require credit checks or bank approvals. However, it is vital to note that unpaid loans will be deducted from the death benefit when the insured passes away.
The Permanence Factor
Whole life insurance is designed to be there "when," not "if," you die. This makes it a preferred tool for estate planning. For individuals with high net worth who may face estate taxes, or for those who have a lifelong dependent (such as a child with special needs), the guaranteed payout of whole life provides a level of certainty that term insurance cannot match.
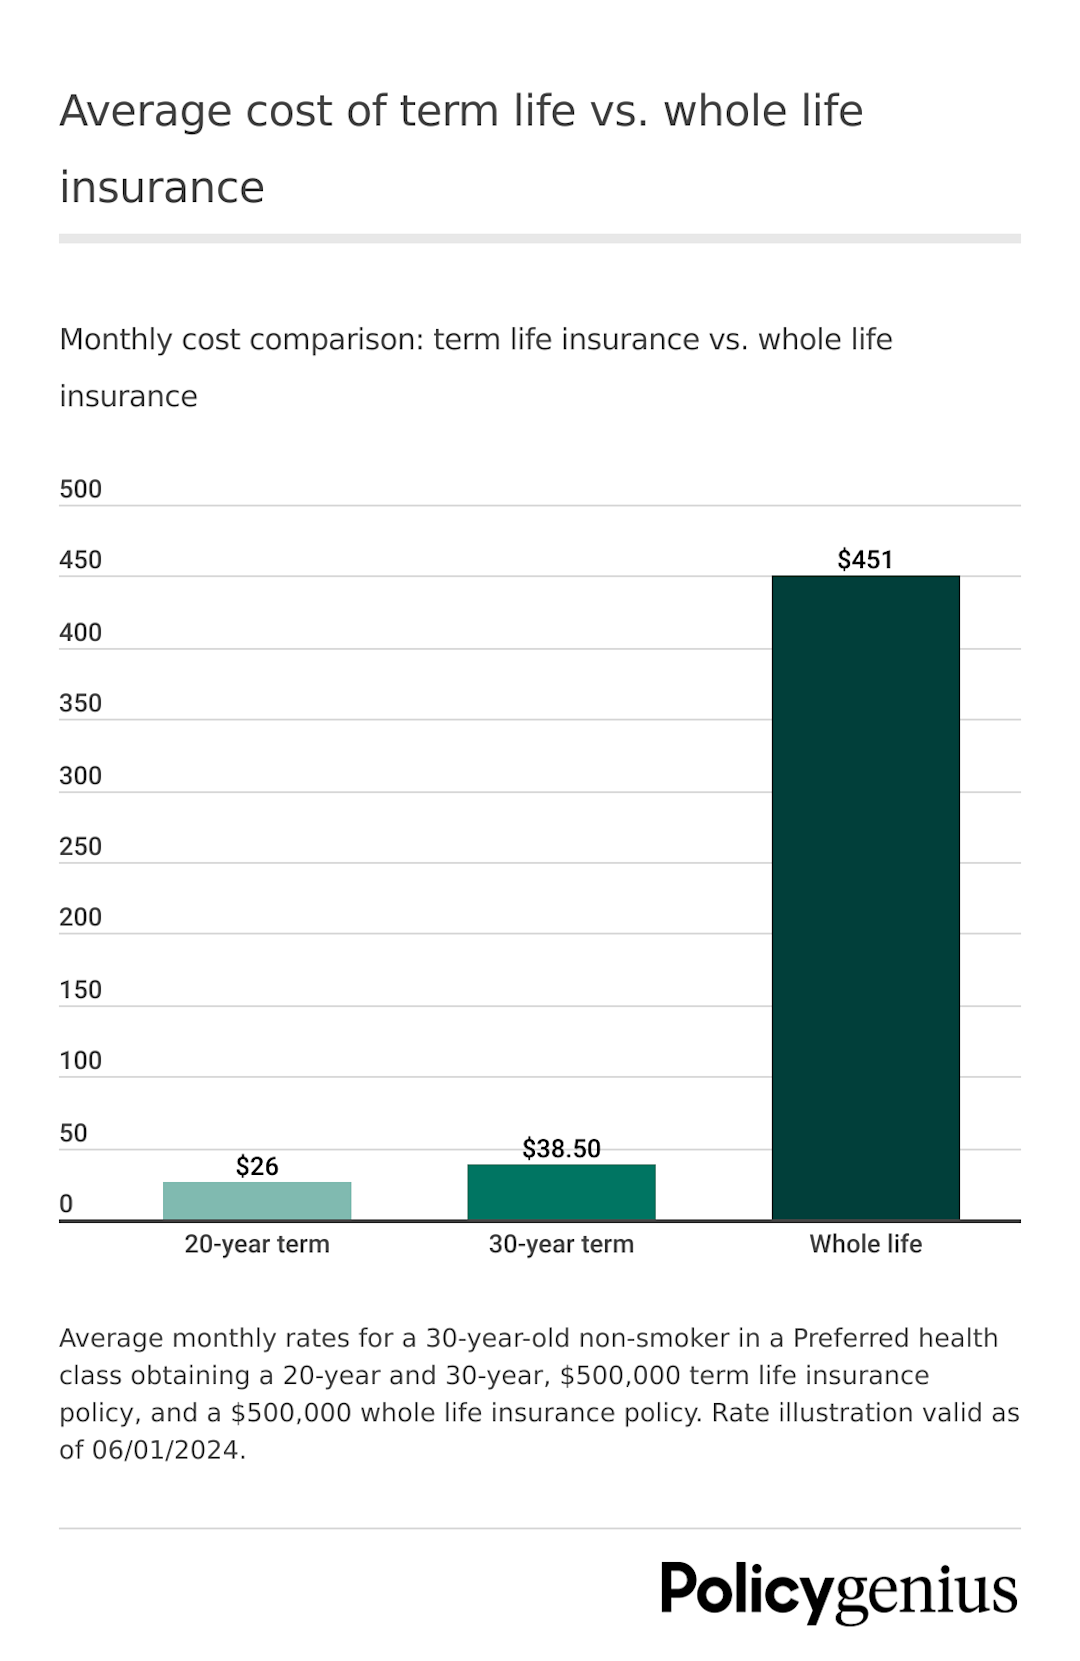
2026 Consumer Comparison: Term vs. Whole Life
To make an informed choice, consumers must compare these products across several key metrics including cost, duration, and flexibility.
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage Duration | Fixed period (10–30 years) | Entire lifetime (Permanent) |
| Premium Cost | Low (Initial affordability) | High (Often 10x–15x more than term) |
| Cash Value Build-up | None | Yes (Guaranteed growth) |
| Premium Stability | Level for the term | Level for life |
| Complexity | Low (Easy to understand) | High (Requires financial expertise) |
| Primary Goal | Income replacement | Estate planning / Wealth transfer |
| Dividends | Not applicable | Available in "Participating" policies |
Detailed Cost Analysis and Value Proposition
The cost disparity between whole and term life is the most significant hurdle for most consumers. A healthy 35-year-old male might pay $35 per month for a $500,000 term policy lasting 20 years. That same individual might be quoted $500 or more per month for a $500,000 whole life policy.
The Opportunity Cost of Whole Life
Critics of whole life insurance often point to the "Buy Term and Invest the Difference" (BTID) strategy. The logic is that if you buy the cheaper term policy and invest the remaining $465 (the difference in premiums) into a diversified stock market index fund, you would likely end up with a significantly larger nest egg over 20 years than the cash value accumulated in a whole life policy.
However, proponents of whole life argue that most consumers do not actually "invest the difference"—they spend it. For these individuals, whole life acts as a form of "forced savings." Furthermore, the cash value in a whole life policy is not subject to market volatility, providing a "safe bucket" of assets that can be useful during market downturns.
Surrender Charges and Early Policy Years
Consumers must be aware that whole life insurance is a long-term commitment. In the first few years of a policy, the "surrender value" (the amount you get back if you cancel) is often zero or very low. This is because the insurance company uses the initial premiums to cover commissions and administrative costs. If you buy a whole life policy and cancel it after three years, you will likely lose almost every dollar you paid in. Term insurance, by contrast, can be cancelled at any time with no penalty, other than the loss of coverage.
Modern Underwriting in 2026: What to Expect
The process of applying for life insurance has changed drastically by 2026. The days of waiting six weeks for a nurse to visit your home for a blood draw are largely over for standard policies.
- Accelerated Underwriting: Carriers now use "Big Data" to evaluate risk. They access prescription drug databases, motor vehicle records, and even credit attributes to determine your health status. If you are healthy, you may receive an approval instantly.
- Digital Health Records: Many insurers now request access to your electronic health records (EHR). This provides a more comprehensive view of your medical history than a one-time physical exam.
- Wearable Data: Some 2026 policies offer "wellness discounts" if you share data from your smartwatch or fitness tracker, rewarding you for maintaining an active lifestyle and healthy heart rate.
Regardless of the technology used, honesty remains paramount. Any material misrepresentation on an application can lead to a "contestability" period claim denial, where the insurer refuses to pay the death benefit if they discover you lied about your health or lifestyle.
Strategic Selection: Which Policy Fits Your Profile?
Choosing the right policy is not about which product is "better" in a vacuum, but which is better for your specific stage of life.
The Young Family
For a couple in their 30s with a new mortgage and young children, Term Life Insurance is almost always the superior choice. The goal during this phase is maximum protection for minimum cost. You need to ensure that if a breadwinner passes away, the mortgage is paid and the children can go to college. Term insurance allows you to buy the large amount of coverage necessary to meet those high-stakes needs.
The High-Net-Worth Individual
For an individual whose estate exceeds federal or state tax exemptions, Whole Life Insurance can be a strategic tool. The death benefit can be used to pay estate taxes, ensuring that heirs do not have to sell off property or businesses to pay the government. When held inside an Irrevocable Life Insurance Trust (ILIT), the proceeds can even be exempt from estate taxes themselves.
The Career Professional (Mid-Life)
By the time you reach your 50s, your needs might shift. If your mortgage is paid and your children are independent, you might not need a $1 million term policy anymore. However, you might want a smaller permanent policy to cover "final expenses" or to leave a guaranteed legacy. In this case, a "Term-to-Permanent" conversion (if your policy allows it) or a new, smaller whole life policy might be appropriate.
Common Pitfalls and Consumer Protection
The life insurance industry is heavily regulated, but "buyer beware" still applies. To protect your interests, consider the following:
- Avoid "Accidental Death" Only Policies: These policies only pay out if you die in an accident. They are very cheap but provide a false sense of security, as most people die from illnesses, not accidents.
- Check Financial Strength Ratings: Only buy from companies with high ratings from independent agencies like AM Best or Moody's. These ratings indicate the company’s ability to pay claims decades into the future.
- Understand the "Riders": Riders are add-ons to your policy. A "Waiver of Premium" rider pays your premiums if you become disabled. An "Accelerated Death Benefit" rider allows you to access a portion of the death benefit if you are diagnosed with a terminal illness. Evaluate if these are worth the extra cost.
- Review Your Policy Annually: Life changes. A divorce, a new child, or a significant promotion should trigger a review of your coverage amounts and beneficiary designations.
Frequently Asked Questions
Can I have both term and whole life insurance?
Yes. Many consumers use a "laddering" strategy. They maintain a base of whole life insurance for permanent needs (like funeral costs) and layer on a large term policy during their working years to cover income replacement and debt. This provides a balance of permanent security and high-volume temporary protection.
What happens if I can no longer afford my whole life premiums?
Whole life policies offer "non-forfeiture options." If you can't pay, you may be able to use the existing cash value to turn the policy into a "Reduced Paid-Up" policy, where you have a smaller death benefit but never have to pay another premium. Alternatively, you can surrender the policy for its current cash value, minus any fees.
Is term life insurance a waste of money if I don't die?
No. Insurance is the purchase of "risk transfer." You are paying the premium so the insurance company carries the financial risk of your death instead of your family. Similar to car insurance, the fact that you didn't have an accident doesn't mean the premium was wasted; it provided protection and peace of mind for the duration of the policy.
Are life insurance death benefits taxable?
Generally, no. Under current Internal Revenue Service (IRS) rules, life insurance death benefits paid to beneficiaries are not considered taxable income. However, if the policy is part of a very large estate, it could be subject to federal estate taxes. Additionally, if a policy is "sold" (a life settlement), the tax implications change significantly.
What is the "Free Look" period?
Most states mandate a "Free Look" period, usually lasting 10 to 30 days after you receive the policy. During this time, you can cancel the policy for any reason and receive a full refund of all premiums paid. This is a critical consumer protection that allows you to review the fine print without financial risk.
Practical Next Actions
To secure the right coverage in 2026, start by calculating your "Human Capital" value. Multiply your annual income by the number of years until you plan to retire; this gives you a baseline for the amount of protection your family would lose if you were gone.
- Request Multiple Quotes: Use independent brokers who represent multiple carriers rather than "captive" agents who only sell for one company.
- Evaluate Your Duration: If your youngest child is 5, a 20-year term policy is likely sufficient. If you have a lifelong dependent, look into permanent options.
- Read the Illustration: For whole life policies, ask for a "Full Illustration." This document shows both the guaranteed and non-guaranteed (dividend-based) growth of your cash value over 40+ years.
- Confirm Beneficiaries: Ensure your primary and contingent beneficiaries are clearly named. Avoid naming "my estate" as a beneficiary, as this can force the death benefit into a lengthy probate process.
By approaching life insurance as a tool for risk management rather than a "get rich" scheme, you can build a stable financial foundation that protects your loved ones regardless of what the future holds.
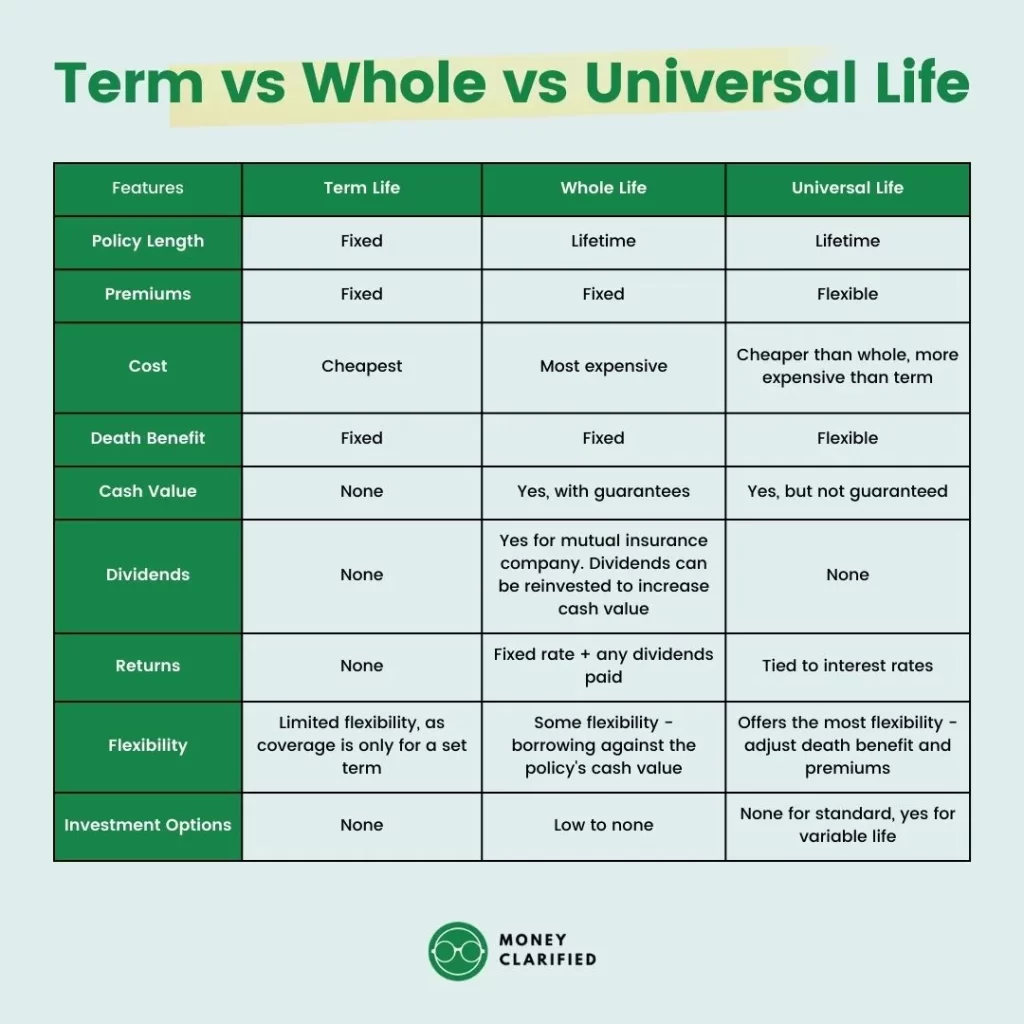
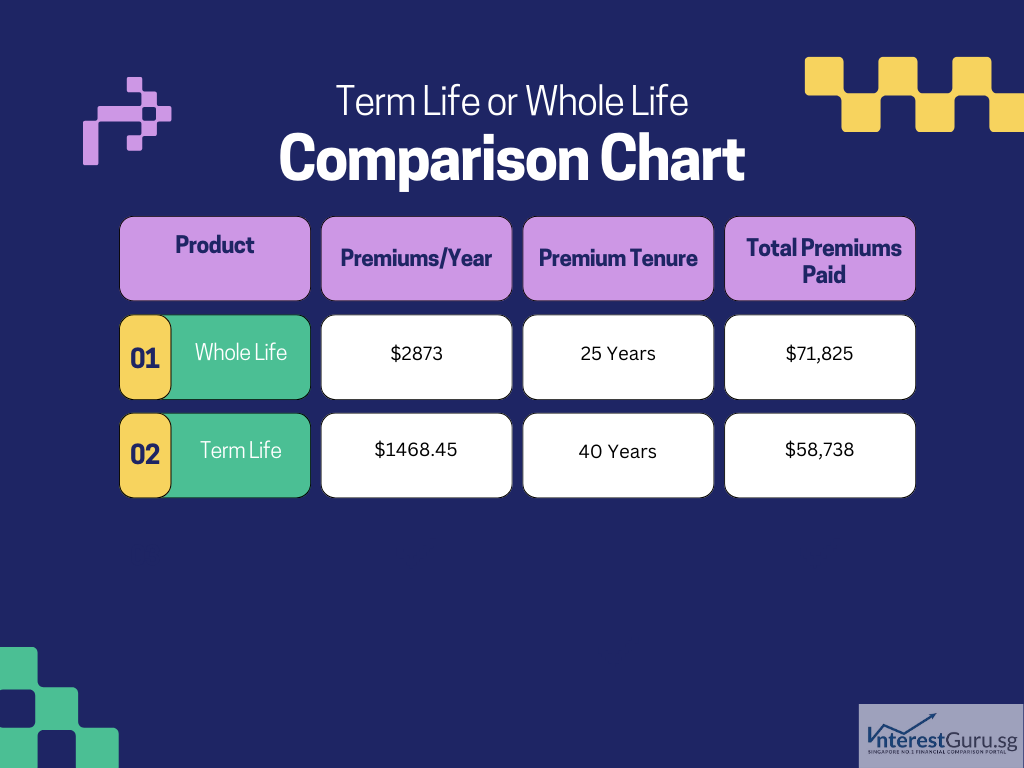
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
