In 2026, the best 15-year fixed mortgage rates currently range between 5.15% and 5.85% for borrowers with excellent credit scores and a loan-to-value ratio of 80% or less. These rates represent a significant interest saving over the standard 30-year fixed term, though they require a higher monthly debt commitment.
Navigating the mortgage market in 2026 requires a keen understanding of how macroeconomic shifts and personal financial health intersect. While the era of sub-3% rates is firmly in the past, the 15-year fixed-rate mortgage remains one of the most powerful tools for building home equity quickly and minimizing the total cost of borrowing. Finding the "best" rate today is not merely about a single number; it is about finding the optimal combination of interest, annual percentage rate (APR), and lender reliability that fits your specific financial trajectory.
The State of the 15-Year Mortgage Market in 2026
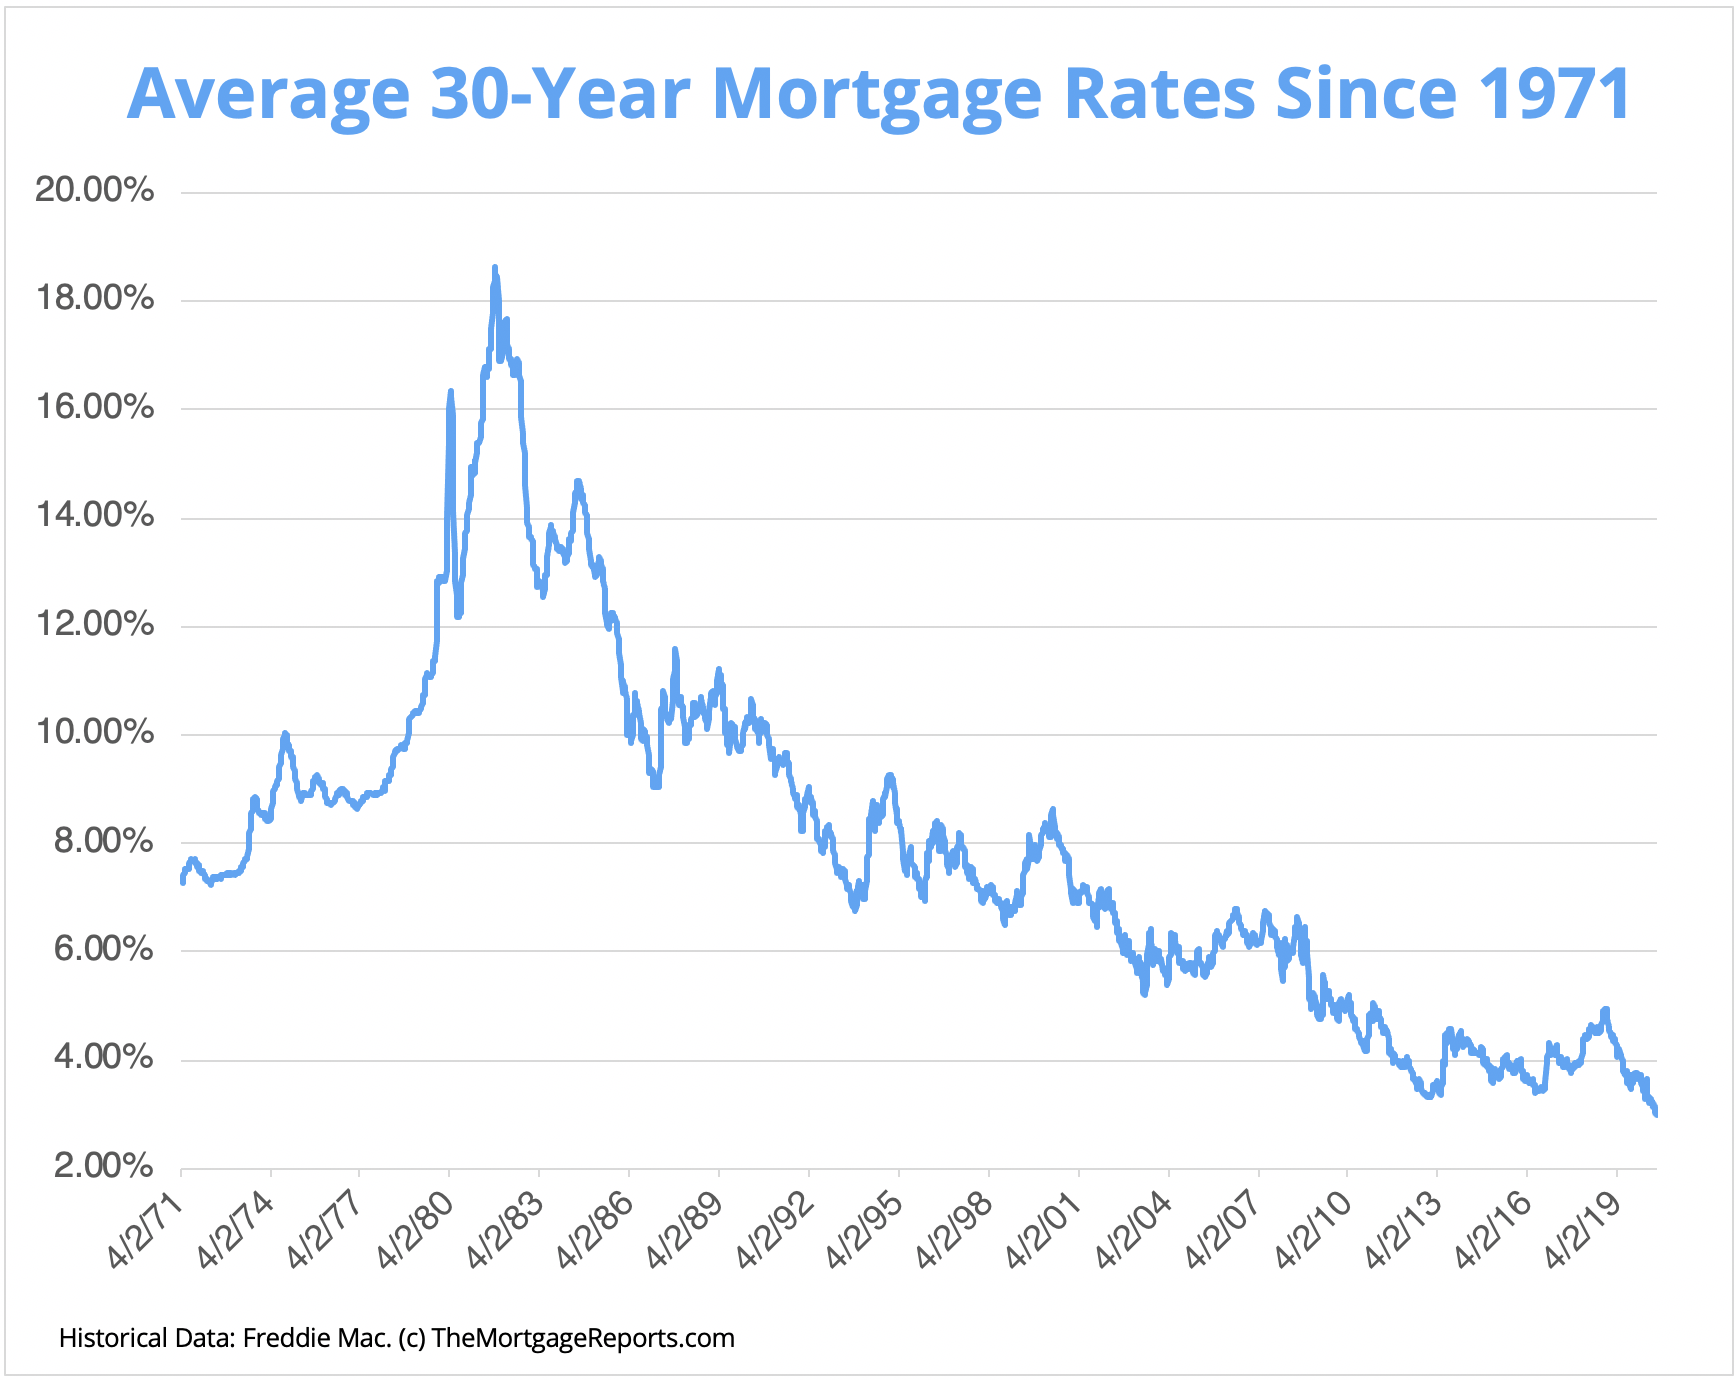
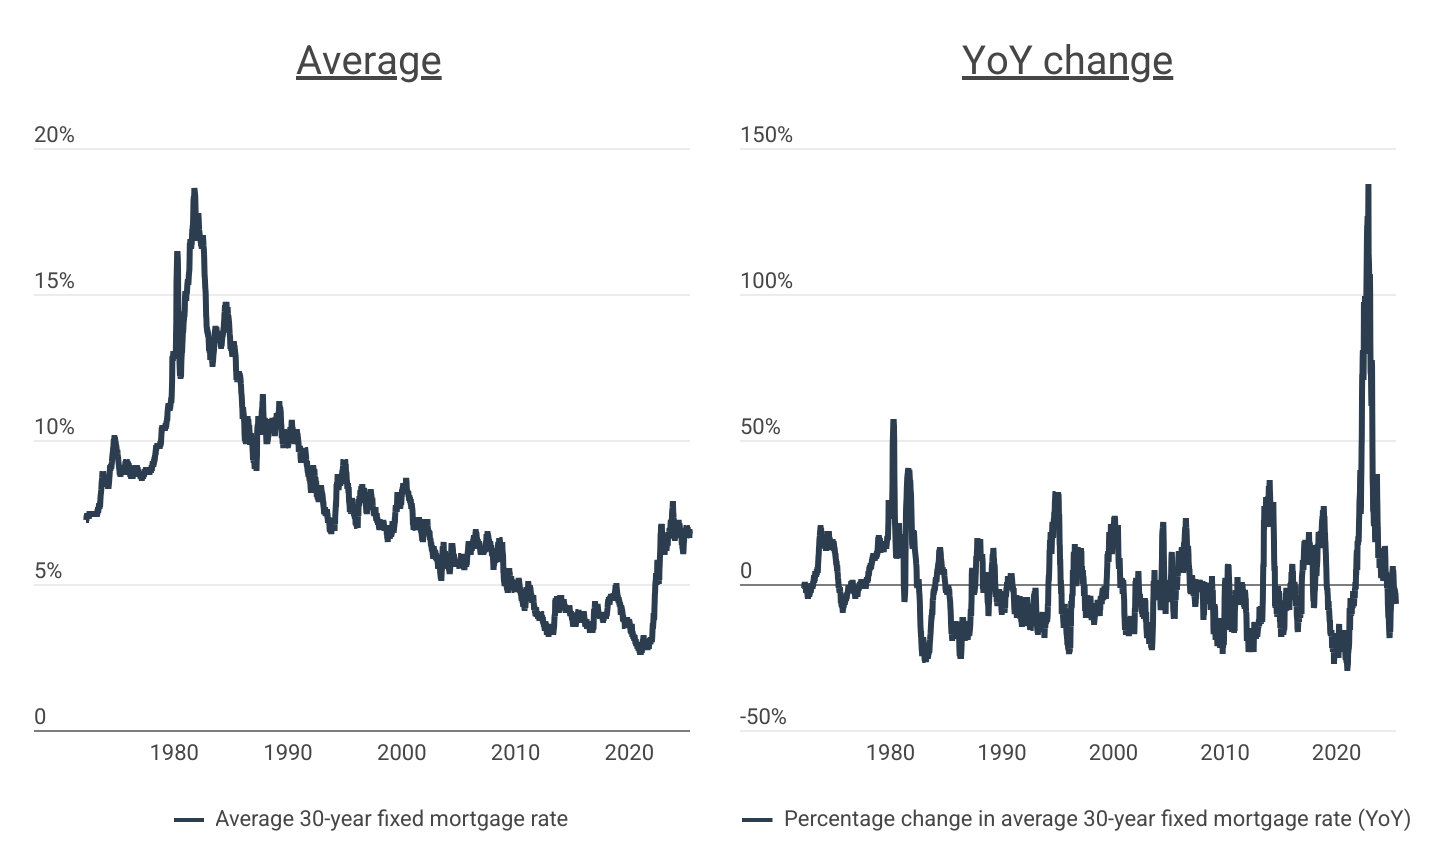
As we move through 2026, the mortgage landscape has reached a period of relative stabilization compared to the volatility seen in the early part of the decade. The Federal Reserve's long-term approach to balancing inflation and employment has kept mortgage benchmarks within a predictable corridor. For the 15-year fixed-rate mortgage, this has translated to a spread that is typically 0.50% to 0.75% lower than the 30-year fixed-rate counterpart.
The primary driver of 15-year rates remains the yield on the 10-year Treasury note, though mortgage-backed securities (MBS) pricing plays a direct role in daily fluctuations. Because 15-year loans represent less risk to lenders—both in terms of duration and the typically higher credit quality of the borrowers who select them—investors are willing to accept lower yields. This "short-term premium" is what allows the 15-year fixed rate to remain the gold standard for those looking to maximize their long-term wealth through real estate.
Why Choose a 15-Year Fixed-Rate Mortgage?
The decision to opt for a 15-year term instead of a 30-year term is a strategic trade-off between monthly cash flow and long-term interest expense. In the current 2026 market, the benefits of the shorter term are more pronounced than ever.
Massive Interest Savings
The most compelling reason to secure a 15-year rate today is the reduction in total interest paid. Because the principal is paid down much faster, interest has less time to accrue. On a $400,000 loan, the difference in total interest paid between a 15-year and a 30-year mortgage can exceed $250,000, depending on the specific rate spread.
Accelerated Equity Growth
With a 15-year mortgage, a larger portion of your very first payment goes toward the principal compared to a 30-year loan. This means you reach the 50% equity mark much faster, which is a critical advantage if you plan to use home equity for future investments, renovations, or as a safety net.
Discipline and Debt-Free Living
Many borrowers in 2026 choose the 15-year term as a forced savings mechanism. By committing to a higher monthly payment, they ensure the home is owned free and clear in half the time. This is particularly attractive for mid-career professionals looking to eliminate their largest monthly expense before reaching retirement age.
Factors Influencing Your Personal Mortgage Rate
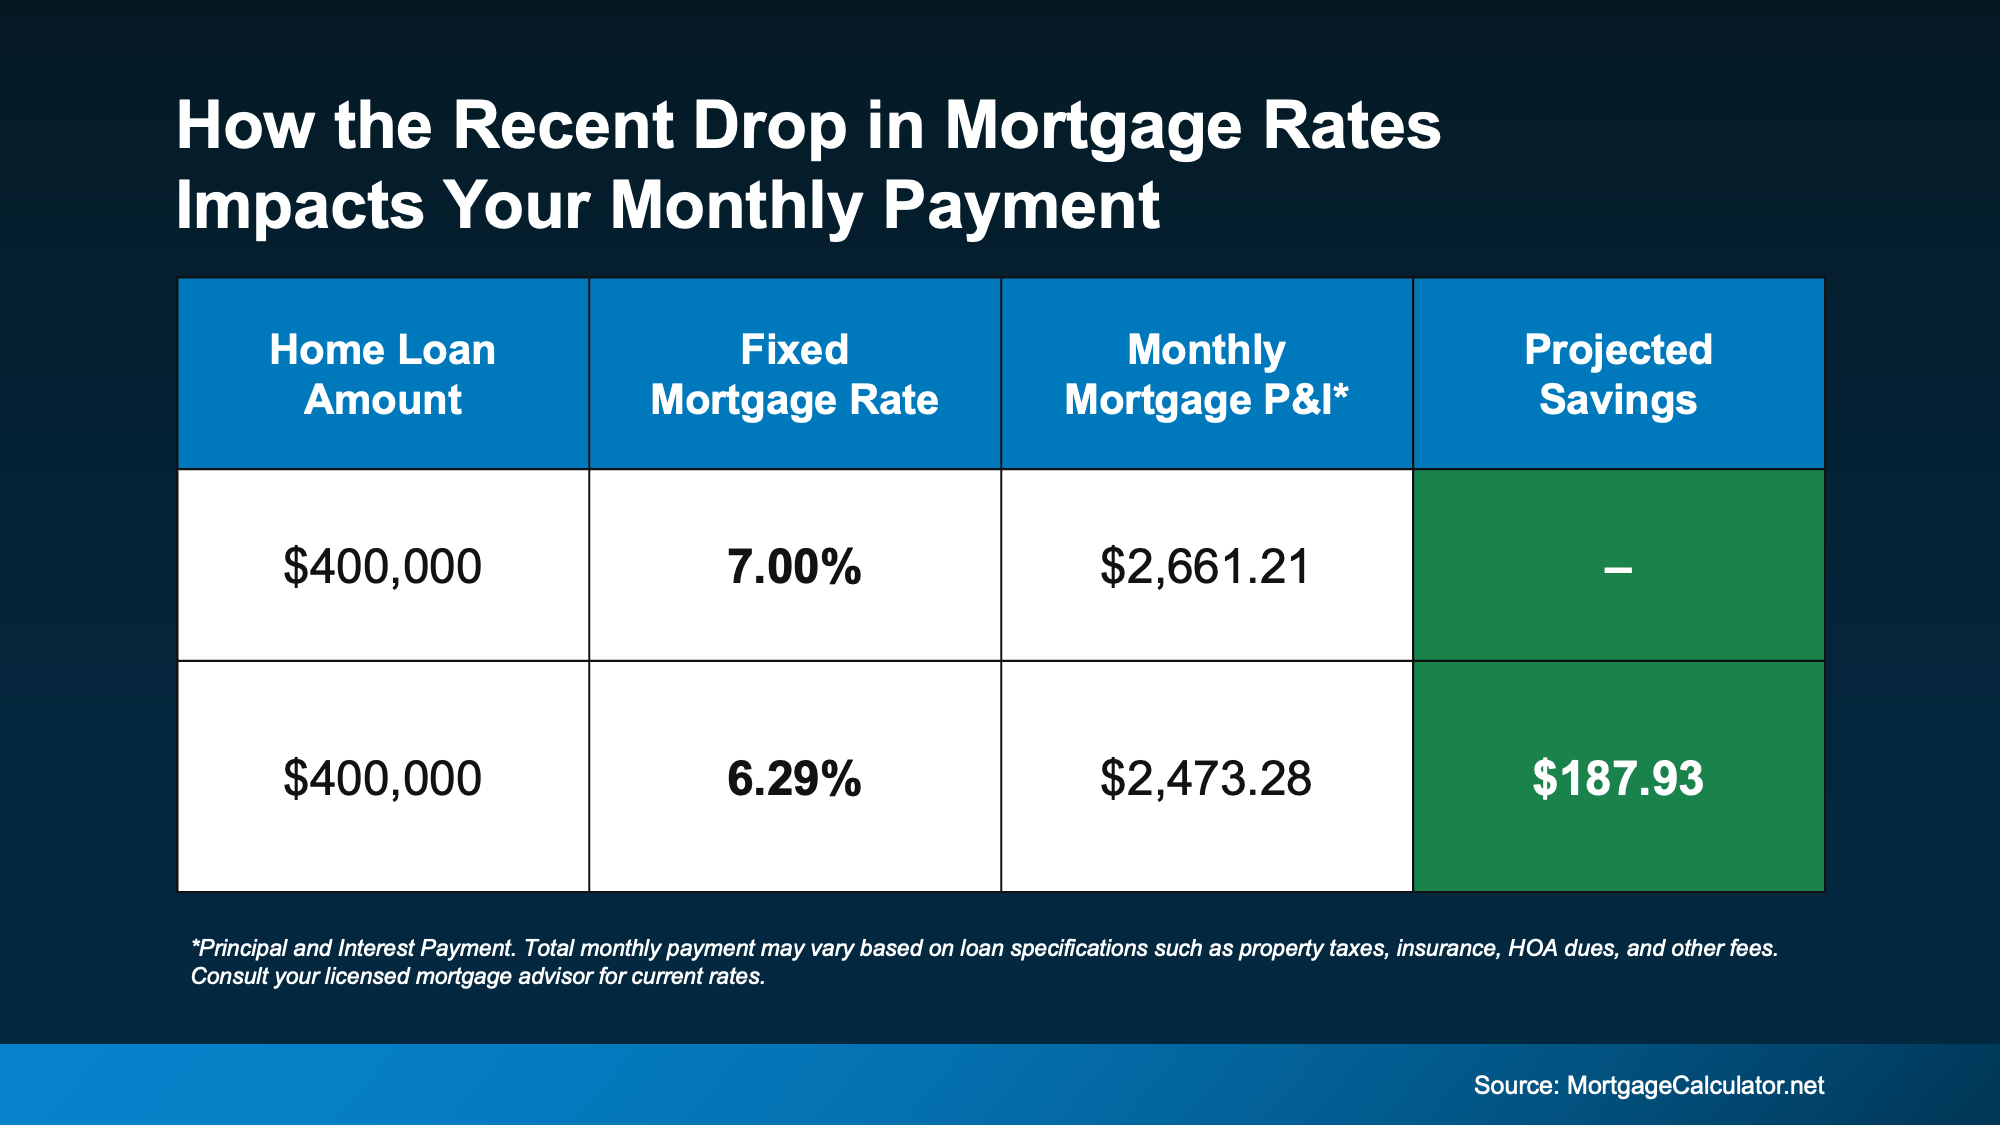
The "headline" rates you see advertised online are often reserved for "perfect" borrowers. To secure the best 15-year fixed mortgage rates today, your personal financial profile must align with several key lender requirements.
Credit Score (FICO)
In 2026, lenders have tightened their tiers for the lowest rates. To access the 5.15% to 5.25% range, a FICO score of 780 or higher is generally required. Borrowers with scores between 720 and 760 may see rates 0.25% to 0.50% higher, while those below 680 may find the 15-year term difficult to qualify for due to the higher monthly debt-to-income (DTI) requirements.
Loan-to-Value (LTV) Ratio
Your down payment significantly impacts your rate. A 20% down payment (80% LTV) is the standard benchmark for the best rates. If you can provide 25% or 30%, some lenders may offer a further discount. Conversely, if you are refinancing and your home value has shifted, an LTV above 80% will likely trigger private mortgage insurance (PMI) and a higher interest rate.
Debt-to-Income (DTI) Ratio
Because 15-year mortgage payments are substantially higher than 30-year payments, lenders scrutinize your DTI more closely. Most lenders prefer a back-end DTI (all monthly debts divided by gross monthly income) of 36% or less, though some programs allow up to 43% for otherwise strong candidates.
Loan Amount and Type
Conforming loan limits—the maximum loan amounts that Fannie Mae and Freddie Mac will back—are updated annually. In 2026, loans that fall within these limits generally carry lower rates than "Jumbo" loans, which are used for higher-priced properties and typically require even higher credit scores and larger reserves.
Comparing 15-Year vs. 30-Year Mortgage Scenarios
To understand the impact of today's rates, it is helpful to see the mathematical breakdown of a typical loan. The following table compares a standard $350,000 mortgage at 2026 market averages.
| Feature | 15-Year Fixed Mortgage | 30-Year Fixed Mortgage |
|---|---|---|
| Average Interest Rate | 5.35% | 6.10% |
| Monthly Principal & Interest | $2,833 | $2,121 |
| Total Interest Paid | $159,940 | $413,560 |
| Total Cost of Loan | $509,940 | $763,560 |
| Equity at Year 10 | ~73% | ~22% |
| Interest Savings | $253,620 | N/A |
Note: Estimates based on 2026 market projections; excludes taxes, insurance, and HOA fees. Figures rounded for clarity.
How to Compare Mortgage Offers (Beyond the Interest Rate)
When you are hunting for the best 15-year fixed mortgage rates today, the interest rate is only part of the equation. You must look at the Annual Percentage Rate (APR) to understand the true cost.
Interest Rate vs. APR
The interest rate is the cost of borrowing the principal. The APR includes the interest rate plus other costs like broker fees, points, and some closing costs. If Lender A offers a 5.25% rate with $5,000 in fees and Lender B offers a 5.35% rate with $500 in fees, Lender B may actually be the cheaper option over the life of the loan.
Discount Points
In 2026, many borrowers are "buying down" their rates using points. One point typically costs 1% of the loan amount and reduces your interest rate by roughly 0.25%. This is a "break-even" calculation: if the monthly savings from the lower rate pay for the cost of the point within 3 to 5 years, it is generally considered a wise investment for a 15-year loan.
Closing Costs and Fees
Expect to pay between 2% and 5% of the loan amount in closing costs. This includes appraisal fees, title insurance, attorney fees, and recording taxes. When comparing lenders, always request a Loan Estimate (LE). This standardized three-page document allows you to compare different offers side-by-side with 100% transparency.
Where to Find the Best 15-Year Rates Today
In the 2026 financial ecosystem, different types of lenders cater to different borrower profiles.
Online Mortgage Lenders
Online-first lenders often provide the most competitive 15-year rates because they have lower overhead costs than traditional brick-and-mortar banks. They excel in speed and digital document management, making them ideal for borrowers with straightforward financial situations.
Credit Unions
Credit unions are member-owned and often return profits to members in the form of lower interest rates. For a 15-year fixed mortgage, local credit unions frequently outperform national banks, especially for borrowers who already have an established banking relationship with them.
Large National Banks
While their "retail" rates might be slightly higher, big banks often offer "relationship discounts." If you hold significant assets (checking, savings, or investments) with a national bank, they may shave 0.125% to 0.25% off your 15-year mortgage rate to keep your business.
Mortgage Brokers
Brokers do not lend money themselves; they shop your profile to multiple wholesale lenders. In a complex market like 2026, a broker can be invaluable for finding niche programs or lenders that are currently "aggressive" on 15-year pricing to meet their quarterly quotas.
Common Pitfalls to Avoid
- Overextending Your Budget: The higher monthly payment of a 15-year mortgage leaves less "wiggle room" for emergencies. Ensure your emergency fund is fully funded before committing to the shorter term.
- Ignoring the APR: Focusing solely on the lowest interest rate can lead you to lenders who charge exorbitant origination fees.
- Skipping the Pre-Approval: In 2026, the real estate market remains competitive. Without a verified pre-approval letter, your offer on a home—or your ability to lock in a refinance rate—may be ignored.
- Waiting for the "Perfect" Rate: Trying to time the absolute bottom of the market is a gamble. If the numbers work for your budget today, it is often better to lock the rate than to risk a market shift.
Practical Steps to Secure Your Rate
- Check Your Credit Report: Obtain your reports from Equifax, Experian, and TransUnion. Dispute any errors at least three months before applying.
- Calculate Your Maximum Payment: Use a mortgage calculator to see how a 15-year payment fits into your 2026 budget.
- Gather Documentation: Have your last two years of tax returns, W-2s, and the last 60 days of bank statements ready. Digital versions are preferred by modern lenders.
- Get Three Quotes: Never settle for the first offer. Research shows that borrowers who get at least three quotes save an average of $1,500 to $3,000 over the life of the loan.
- Understand the Lock Period: Once you find a rate you like, ask for a "rate lock." This protects you from rate increases for a set period (usually 30 to 60 days) while your loan is being processed.
For official guidance on mortgage disclosures and your rights as a borrower, consult the Consumer Financial Protection Bureau (CFPB). Detailed historical data on rate trends can also be verified through the Federal Reserve Economic Data (FRED).
Frequently Asked Questions
Is a 15-year mortgage always better than a 30-year mortgage?
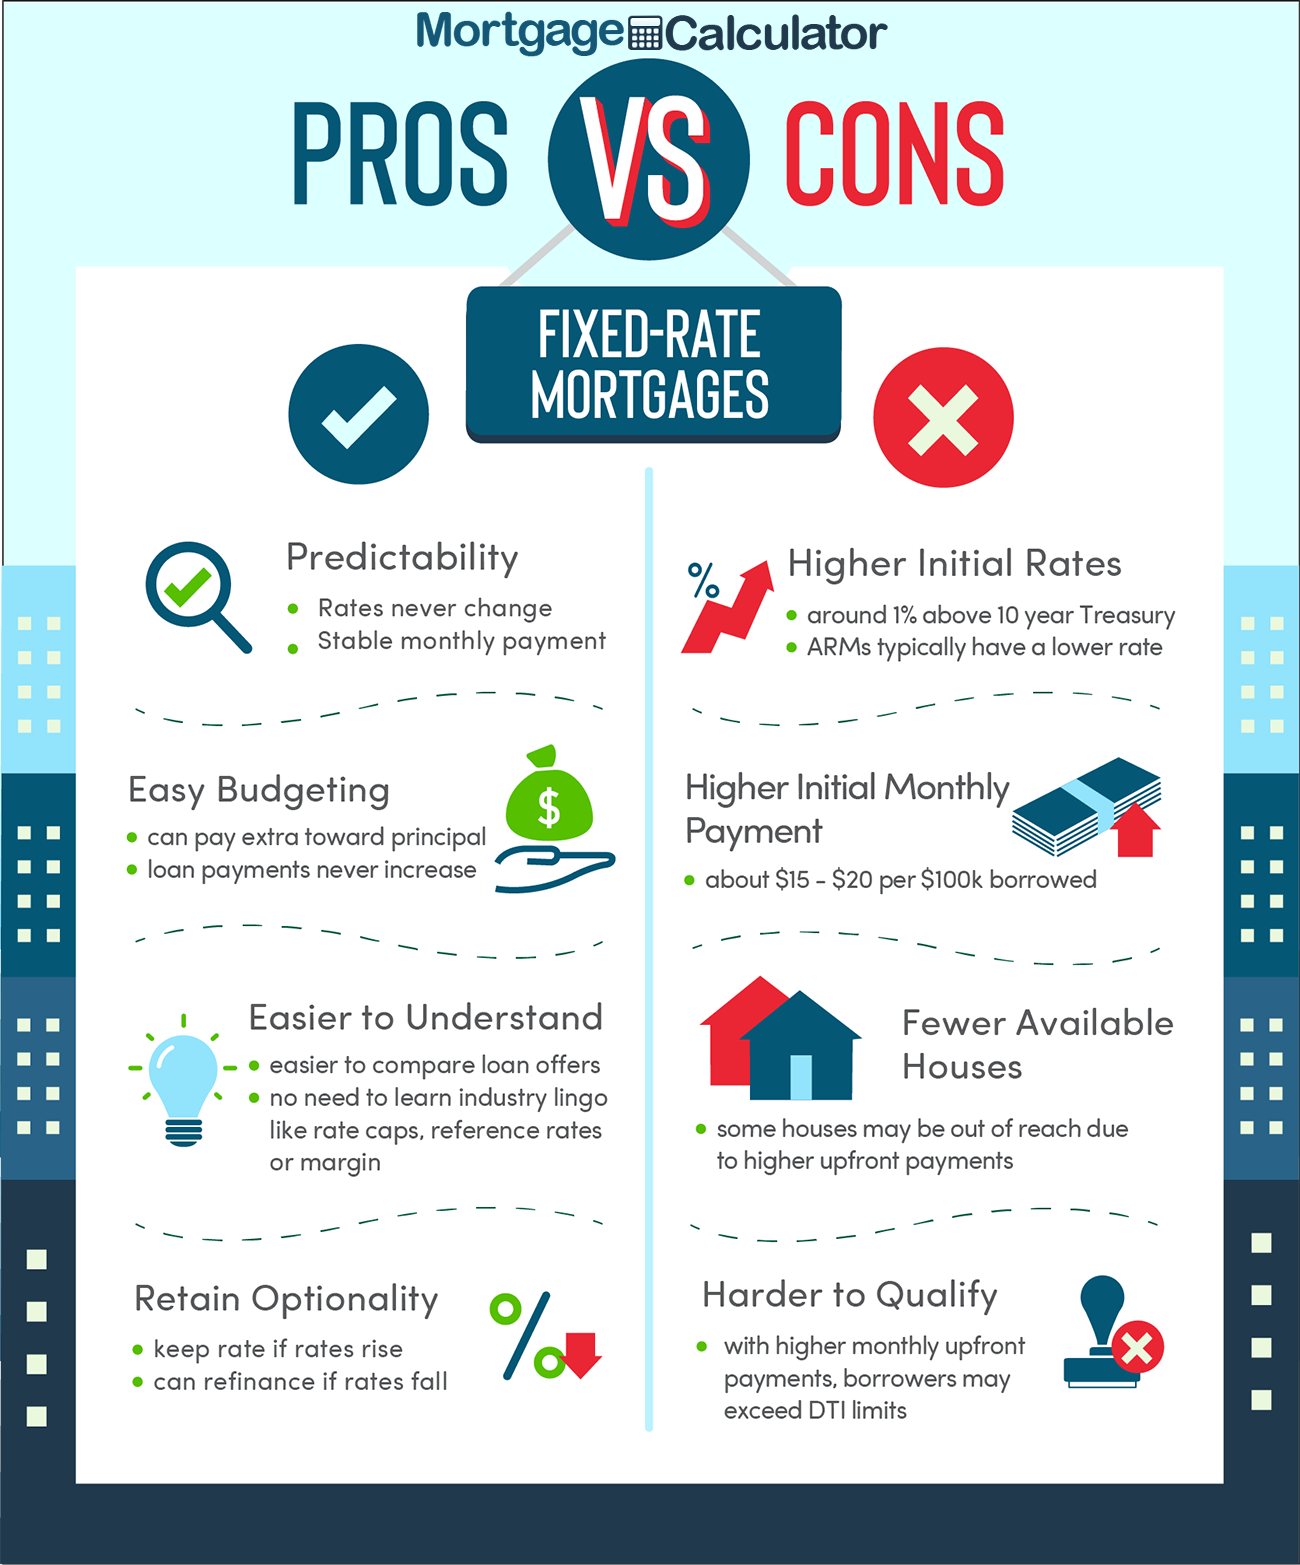
Not necessarily. While a 15-year mortgage saves a massive amount in interest and builds equity faster, the 30-year mortgage provides more flexibility. With a 30-year loan, you can always choose to pay extra toward the principal to "simulate" a 15-year term, but you aren't contractually obligated to the higher payment during lean months.
Can I refinance a 30-year mortgage into a 15-year mortgage in 2026?
Yes, this is a common strategy for homeowners who have seen their income increase or who have built significant equity. If 2026 rates are lower than your original 30-year rate, a refinance can lower your interest expense while simultaneously shortening your remaining term.
Do 15-year mortgages require a larger down payment?
Lenders typically apply the same down payment rules to 15-year and 30-year loans. However, because the monthly payment is higher on a 15-year loan, you may need a higher income to satisfy the Debt-to-Income (DTI) requirements, which a larger down payment can help mitigate by lowering the loan amount.
How much can I save by "buying points" on a 15-year mortgage?
Buying points allows you to pay an upfront fee to lower your permanent interest rate. For a 15-year mortgage, this is often highly effective because you are paying off the loan so quickly. The "break-even point" is usually reached faster on a 15-year term than a 30-year term.
Are 15-year mortgage rates the same for investment properties?
No. Mortgage rates for investment properties or second homes are typically 0.50% to 1.00% higher than rates for primary residences. Even with a 15-year term, expect to pay a premium if you are not planning to live in the home.
What happens if I can't make the higher payment on a 15-year loan?
Because the 15-year loan is a legal contract, you are required to make the full payment. If you are concerned about future income stability, you might be better off taking a 30-year loan and making voluntary extra principal payments, which achieves a similar result without the legal obligation.
Final Recommendation
If your goal is long-term financial independence and you have the stable income to support a higher monthly commitment, the 15-year fixed-rate mortgage remains the most efficient way to finance a home in 2026. To secure the best rate, focus on maintaining a credit score above 780, shopping at least three different lender types (online, credit union, and national bank), and carefully reviewing the APR on every Loan Estimate you receive.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
