
A life insurance policy with high cash value is a permanent insurance contract—typically Whole Life or Universal Life—structured to prioritize equity accumulation over the death benefit. By utilizing "Paid-Up Additions" (PUA) riders and overfunding the policy to its legal limits, policyholders can create a tax-advantaged, liquid asset that grows predictably and can be leveraged for private financing.
While most consumers view life insurance as a tool for protection against premature death, high-net-worth individuals and savvy investors frequently use it as a "volatility buffer" or a secondary "bank." In the financial landscape of 2026, where market fluctuations remain a primary concern for retirement planning, these policies offer a unique combination of tax-deferred growth, tax-free access to capital via loans, and a guaranteed floor on returns. However, achieving high cash value is not an accidental byproduct of buying insurance; it requires a specific technical design known as "max-funding."
The Mechanics of Cash Value Accumulation
To understand how a policy generates high cash value, one must distinguish between the "base premium" and "additional contributions." In a standard life insurance policy, a significant portion of your premium in the early years goes toward the agent's commission and the cost of insurance (COI). This results in little to no cash value for the first 3 to 10 years.
A high-cash-value policy flips this script. By minimizing the base death benefit—the minimum amount of insurance the IRS allows for a specific amount of premium—the policyholder reduces the COI drag. The remaining premium is funneled into riders, most commonly the Paid-Up Additions (PUA) rider. This capital goes almost entirely toward the cash value, minus a small company fee, and begins earning dividends or interest immediately.
The Role of Dividends and Interest
In 2026, mutual insurance companies remain the preferred choice for high-cash-value Whole Life policies. As a policyholder in a mutual company, you are essentially a partial owner. When the company performs well, it issues a dividend. While dividends are technically considered a "return of overpaid premium" by the IRS (and are therefore not taxable), they function as the primary engine for growth in a high-cash-value environment.
Universal Life policies, particularly Indexed Universal Life (IUL), take a different approach. Instead of dividends, the cash value growth is tied to the performance of a market index, such as the S&P 500, but with a "floor" (usually 0%) and a "cap." This allows for higher potential growth than Whole Life, though it introduces more risk regarding the future cost of insurance.
Key Policy Types for Cash Value Maximization
Not all permanent life insurance policies are created equal. Choosing the wrong chassis can result in high fees that erode your capital.
1. Dividend-Paying Whole Life
This is the "gold standard" for predictability. When structured by an agent specializing in the Infinite Banking Concept (IBC) or Bank On Yourself methods, these policies can have significant liquidity in the very first year. The growth is guaranteed by the contract, and the dividends provide an additional non-guaranteed boost. In 2026, top-tier mutual carriers are seeing internal rates of return (IRR) on cash value between 3% and 5%, depending on the age and health of the insured.
2. Indexed Universal Life (IUL)
IULs offer more flexibility than Whole Life. You can adjust your premium payments and death benefit more easily. The cash value growth is linked to an index, providing a hedge against inflation. However, IULs are "unbundled," meaning the cost of insurance increases as you get older. If the market stays flat for several years, the rising COI can eat into the cash value, requiring the policyholder to inject more cash to keep the policy from lapsing.
3. Variable Universal Life (VUL)
VULs allow the policyholder to invest the cash value directly into sub-accounts (similar to mutual funds). While this offers the highest potential for "high cash value," it also carries the highest risk. There is no floor; if the market crashes, your cash value can vanish, and your policy could require massive premium hikes to stay active.

The Critical Importance of the MEC Limit (IRS Section 7702)
When your goal is to maximize cash value, you run into a legal ceiling known as the Modified Endowment Contract (MEC) limit. Under IRS Section 7702, if you put too much money into a life insurance policy too quickly, the IRS reclassifies it as a MEC.
Once a policy becomes a MEC, it loses its most valuable tax advantage: the ability to take tax-free loans. Instead, any money taken out is taxed on a "gain-first" basis (LIFO), and if you are under age 59½, you may face a 10% penalty. Professional agents in 2026 use sophisticated software to "walk the line" of the MEC limit, ensuring the policy is funded as heavily as possible without crossing the threshold that would trigger adverse tax consequences.
Comparing High-Cash-Value Policy Features
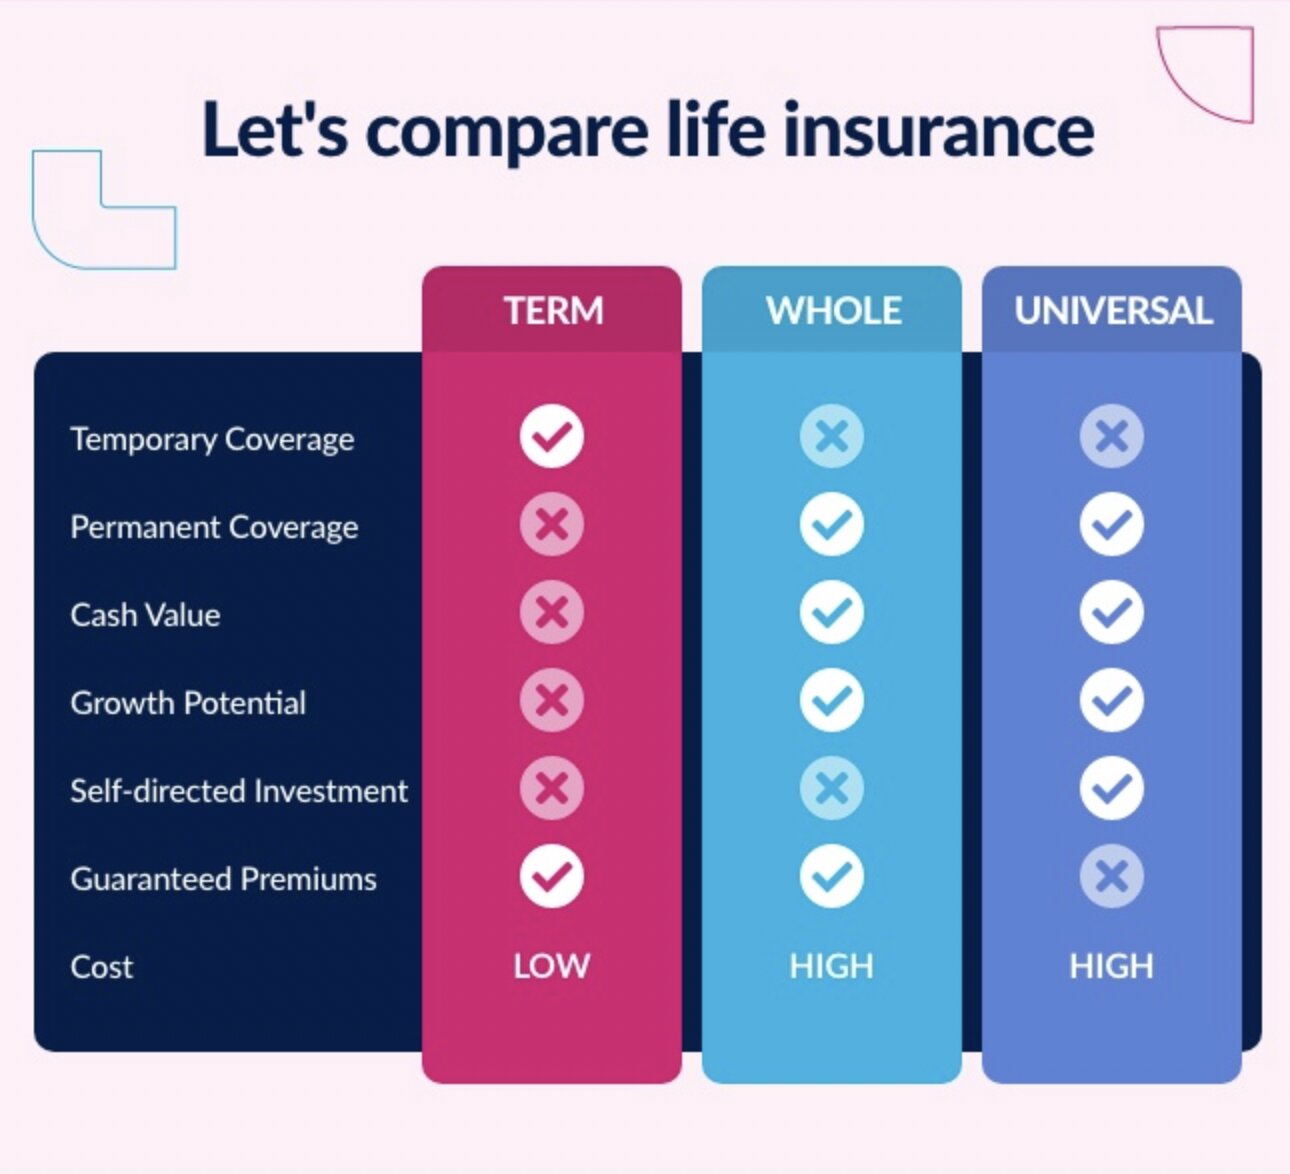
| Feature | Dividend-Paying Whole Life | Indexed Universal Life (IUL) | Variable Universal Life (VUL) |
|---|---|---|---|
| Growth Driver | Guaranteed Interest + Dividends | Market Index Performance | Sub-account Performance |
| Downside Protection | Contractual Guarantee (Floor) | 0% Floor (Usually) | None (Market Risk) |
| Premium Flexibility | Low (Fixed) | High (Adjustable) | High (Adjustable) |
| Fees | Front-loaded (High early) | Ongoing (Increasing with age) | Varies (Based on investments) |
| Best For | Predictable "Banking" & Liquidity | Long-term growth with flexibility | Maximum aggressive growth |
Accessing Your Capital: Loans vs. Withdrawals
The primary reason to build a high-cash-value policy is to use the money during your lifetime. You have two main ways to access the funds:
Policy Loans
Unlike a 401(k) loan, which you must pay back to your employer's plan, a life insurance loan is technically a loan from the insurance company's general fund, using your cash value as collateral.
- The Benefit: Your cash value remains inside the policy, continuing to earn interest and dividends as if you never touched it (this is known as Non-Direct Recognition).
- No Credit Checks: There is no application process. You simply request the funds.
- Tax-Free: Because it is a loan, it is not considered taxable income.
Withdrawals (Surrenders)
You can choose to withdraw cash value directly. This is tax-free up to your "basis" (the total amount of premiums you’ve paid). However, withdrawals reduce your death benefit and, unlike loans, the money is removed from the policy’s growth engine. Most experts recommend using the loan feature rather than withdrawals to keep the compounding effect intact.
Strategic Uses of High Cash Value Policies in 2026
In the current economic climate, these policies serve several strategic purposes beyond simple estate planning.
1. The Volatility Buffer
During market downturns, retirees often face "sequence of returns risk"—the danger of withdrawing from a depreciating 401(k) or IRA. A high-cash-value policy allows a retiree to stop taking 401(k) distributions during a bear market and instead live off policy loans. This gives the stock portfolio time to recover, significantly extending the life of the retirement nest egg.
2. Supplemental Executive Retirement Plans (SERP)
High-income earners often find themselves "capped out" of traditional retirement accounts like the 401(k). A high-cash-value policy acts as a "private pension" with no contribution limits (other than those dictated by the MEC rules) and no required minimum distributions (RMDs).
3. Business Financing
Business owners use the high cash value to finance equipment, fleet vehicles, or real estate. By "borrowing from themselves," they avoid high bank interest rates and keep the interest within their own financial ecosystem.
Costs and Limitations to Consider
While the benefits are significant, high-cash-value life insurance is not a "get rich quick" scheme. It is a long-term capital management strategy.
- Underwriting Requirements: You must be medically insurable. While "guaranteed issue" policies exist, they rarely offer the growth potential needed for a high-cash-value strategy.
- Initial Illiquidity: Even a perfectly structured policy will usually take 4 to 6 years to "break even" (where the cash value equals the total premiums paid).
- Surrender Charges: Most Universal Life policies have surrender charges that last 10 to 15 years. If you cancel the policy early, the company will keep a large portion of the cash value.
- Opportunity Cost: The money you put into a policy is money not invested in the S&P 500 or real estate. While the policy is safer, it will likely underperform an aggressive stock portfolio over 30 years.
Common Mistakes to Avoid
- Buying from a "Standard" Agent: Most insurance agents are trained to sell maximum death benefit for maximum commission. To get a high-cash-value policy, you must work with a specialist who understands how to blend base premium with PUA riders.
- Underfunding the Policy: If you set up a high-limit policy but only pay the minimum premium, the cost of insurance will eventually "hollow out" the cash value, potentially causing the policy to lapse.
- Ignoring the Dividend Option: If you have a Whole Life policy, ensure your dividends are set to "Purchase Paid-Up Additions." If you take them as cash, you lose the compounding power.
- Forgetting Interest on Loans: While you don't have to pay back policy loans, the interest will accrue. If the loan balance exceeds the cash value, the policy will lapse, triggering a massive tax bill on all the gains you've enjoyed over the years.
Frequently Asked Questions
Can I lose money in a high-cash-value policy?
In a Whole Life policy, your cash value is contractually guaranteed not to decrease, provided you pay your premiums. In an IUL, you have a 0% floor, so you won't lose money due to market performance, but you could lose money if the cost of insurance (COI) exceeds the interest credited. In a VUL, you can absolutely lose principal because the funds are directly invested in the market.
How soon can I access my cash value?
If structured correctly using a large "dump-in" or a heavy PUA rider, you can often access 60% to 80% of your first-year premium within 30 days of policy issuance. However, it takes several years for the policy to become a truly efficient wealth-building tool.
Is the cash value the same as the death benefit?
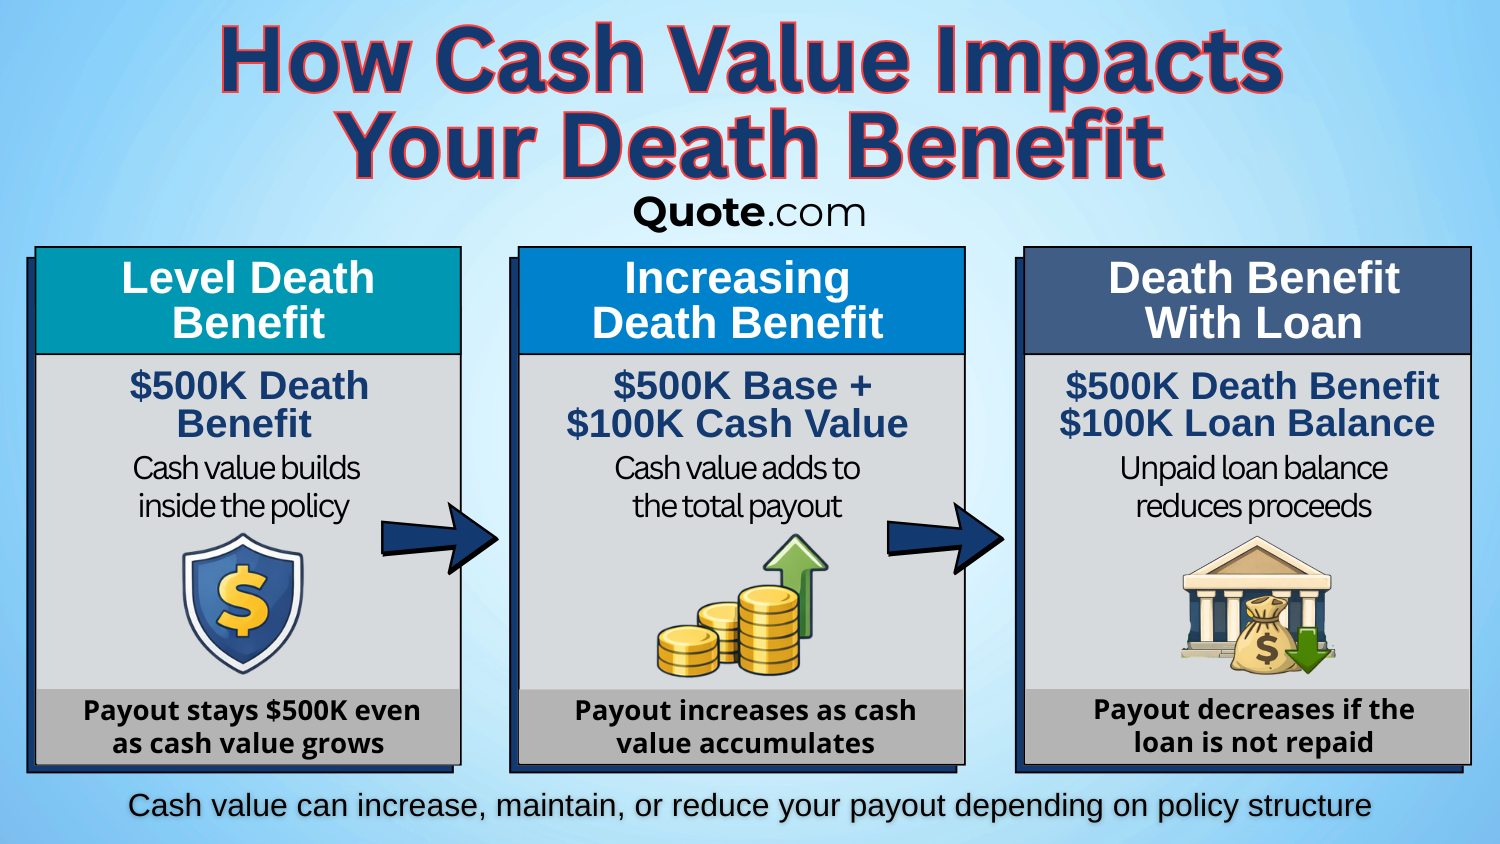
No. The cash value is the "living benefit" or equity you can use while alive. The death benefit is the amount paid to beneficiaries when you pass away. In most policies, the beneficiary receives the death benefit, and the insurance company keeps the remaining cash value, unless you have a specific rider (like an "Option B" or "Increasing" death benefit) that pays both.
Do I have to pay taxes on the growth?
Growth within a life insurance policy is tax-deferred. If you access the money via loans, it is tax-free. If you surrender the policy, you only pay taxes on the amount that exceeds the total premiums you paid (your basis).
What is the maximum I can put into a policy?
There is no absolute dollar limit, but the amount is limited by your "insurable interest" (your net worth and income) and the MEC limits. If you want to put $1 million a year into a policy, you must have a large enough death benefit to justify that premium under IRS rules.
Next Steps for 2026
If you are considering a high-cash-value life insurance policy, your first step should be an "Internal Rate of Return" (IRR) analysis. Request an "In-Force Illustration" (if you already have a policy) or a "New Business Illustration" from a carrier with an A+ or better rating from A.M. Best.
Ensure the illustration shows the "Cash Surrender Value" for every year. Look specifically at years 5, 10, and 20. If the cash value in year 1 is $0, the policy is not structured for high cash value. Seek a specialist who can demonstrate a "max-funded" design that aligns with your 2026 liquidity needs and long-term legacy goals.
Image Gallery
Select an image to open it in a new tab.

Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
