Finding an Auto Insurance Broker Near Me: A Comprehensive Guide to Local Expertise
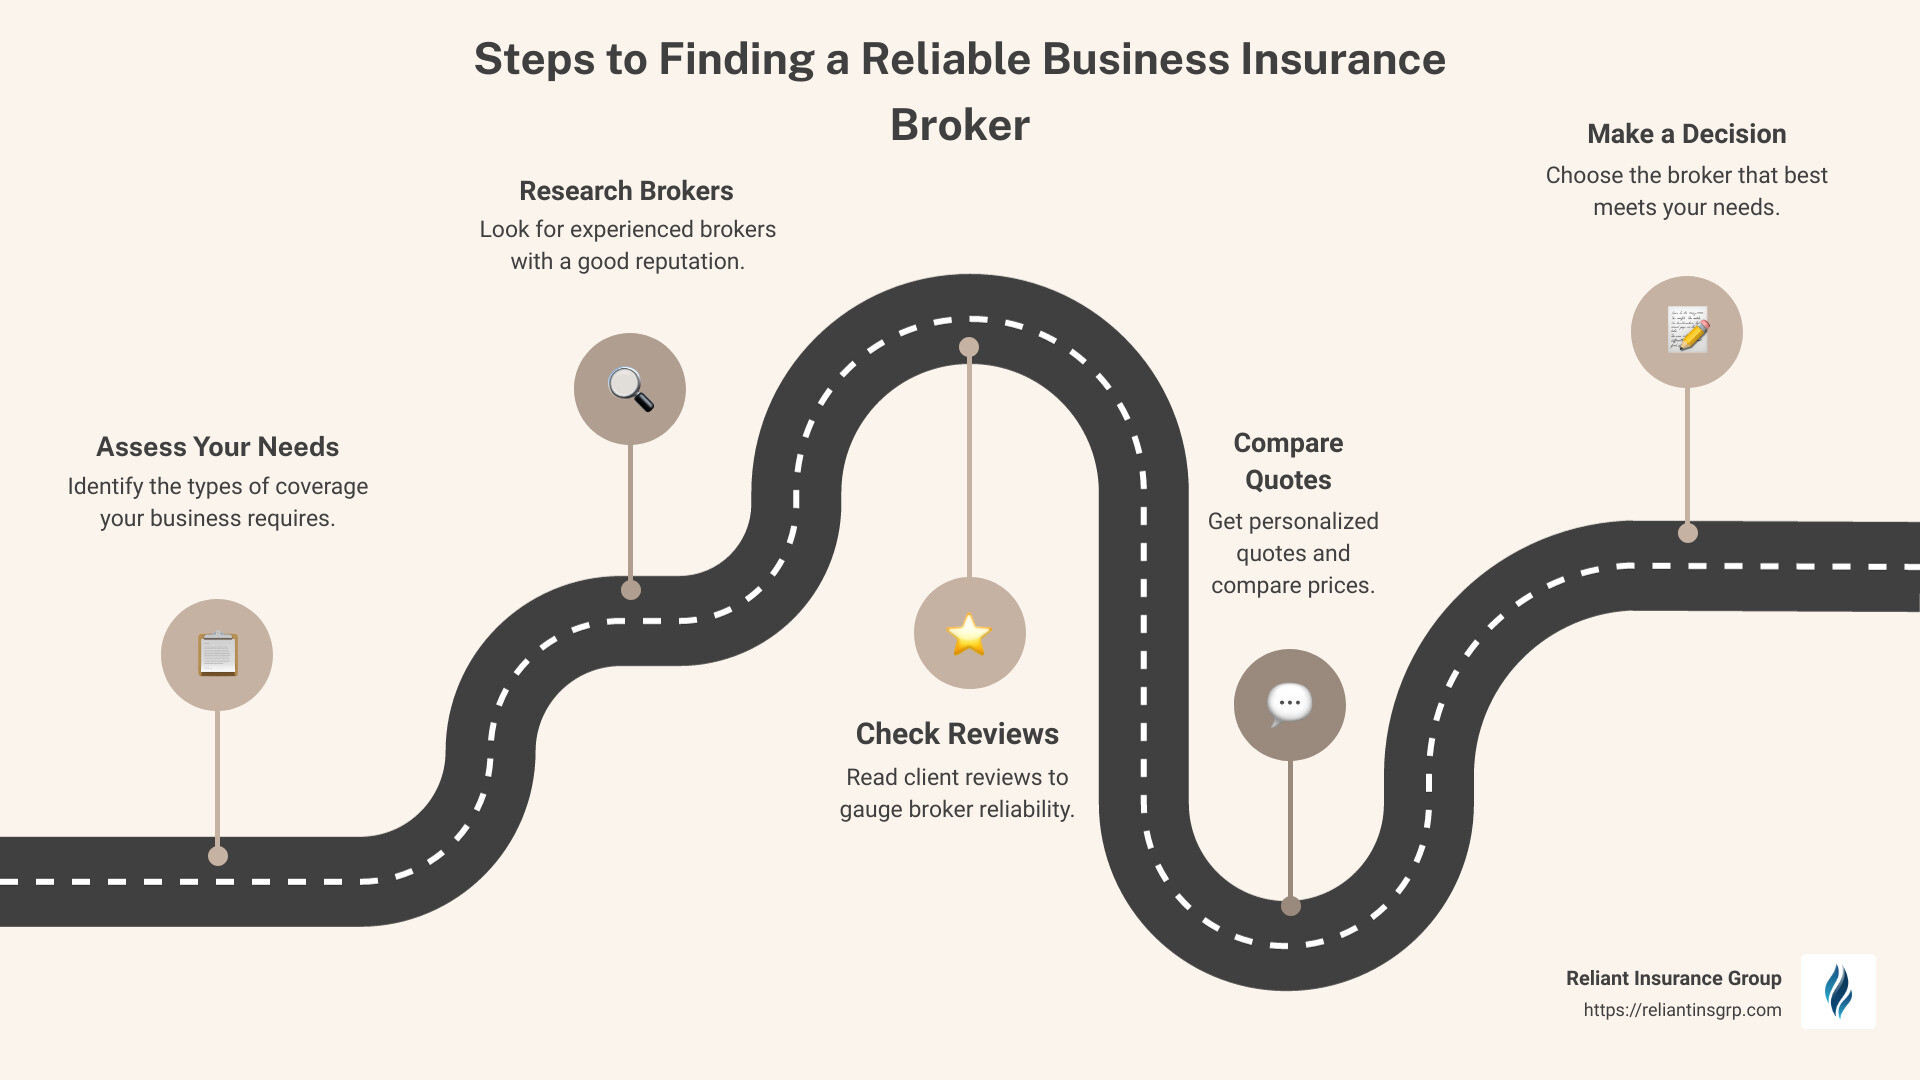
Finding a reliable auto insurance broker near you involves vetting professional credentials, understanding the distinction between independent and captive agents, and utilizing state-regulated resources to ensure you receive impartial coverage advice. By working with a local professional, you gain an advocate who can navigate complex policy language and adjust your coverage based on regional driving risks and state-specific insurance mandates.
The Role of an Auto Insurance Broker
When you search for an "auto insurance broker," you are looking for an intermediary who works on your behalf, rather than for a single insurance company. Unlike "captive agents"—who are employed by one specific carrier and can only sell that company’s products—an insurance broker typically maintains contracts with multiple insurers.
Their primary function is to shop the market, compare quotes from several providers, and present you with a tailored policy that balances cost with necessary coverage limits. In many jurisdictions, brokers are legally required to act as fiduciaries or maintain a high standard of professional care, ensuring that the recommendations provided align with your financial goals and risk profile.
Understanding the Difference Between Brokers and Agents
It is common for the terms "agent" and "broker" to be used interchangeably, but there are distinct legal and operational differences that impact your experience.
- Insurance Brokers: These professionals represent you, the consumer. They must be licensed by the state department of insurance and are often compensated through a combination of flat fees or commissions paid by the insurance carriers they represent. Because they have access to a broader market, they are often better equipped to place high-risk or specialized insurance needs.
- Captive Insurance Agents: These individuals are representatives of a single insurance brand. They possess deep knowledge of that specific company’s product line, discounts, and internal claims processes. They are often the best choice if you are seeking a long-term relationship with one specific national carrier.
- Independent Agents: Similar to brokers, these individuals represent multiple carriers. They often have access to a suite of regional and national insurance companies, allowing them to perform a "blind" comparison of rates to find the lowest premium for the coverage level you desire.
How to Find and Verify a Local Broker
Locating a reputable broker requires more than a simple online search. To ensure you are working with a qualified professional, follow a structured verification process.
- Use Official State Databases: Every state in the U.S. has a Department of Insurance (DOI). These departments maintain public registries of all licensed individuals and firms. Search the DOI website for your state to verify that the broker holds an active license and has no record of disciplinary actions.
- Seek Professional Designations: Look for brokers who hold credentials such as the Chartered Property Casualty Underwriter (CPCU) or Certified Insurance Counselor (CIC). These designations indicate a higher level of professional training and a commitment to ongoing education.
- Evaluate Local Presence: A physical office in your community can be a significant advantage. It ensures that you have a point of contact for complex issues, such as policy endorsements, local garage facility recommendations, or assistance during a high-stakes claim settlement process.
- Review Fee Structures: Before engaging a broker, ask explicitly how they are compensated. Some brokers charge a "broker fee" in addition to the premium you pay to the insurance company. While this is legal in most jurisdictions, it must be disclosed upfront.
Comparison of Insurance Shopping Channels
| Feature | Independent Broker | Captive Agent | Online Aggregator |
|---|---|---|---|
| Market Access | High (Multiple carriers) | Low (Single carrier) | High (Data-based) |
| Personalized Advice | Extensive | Brand-specific | Minimal/Algorithm |
| Advocacy Level | High (Represents you) | Moderate (Represents company) | None |
| Ongoing Support | Direct and personal | Direct and personal | Automated/Call center |
| Fee Transparency | High | Hidden in premiums | Hidden/None |
Prerequisites for Your First Consultation
When you finally meet with an auto insurance broker, being prepared will significantly accelerate the quote process. Brokers rely on precise data to provide accurate premiums; providing incomplete or incorrect information can lead to significant discrepancies between the quote and the final policy price.
Ensure you have the following information readily available:
- Vehicle Information: The Vehicle Identification Number (VIN), current mileage, and primary garaging address.
- Driving History: A record of any accidents, moving violations, or insurance claims within the past five years. Be honest, as the broker will verify this through the Comprehensive Loss Underwriting Exchange (CLUE) report.
- Coverage Goals: Determine your risk tolerance. Do you need high liability limits to protect your assets, or are you prioritizing the minimum requirements mandated by your state?
- Existing Policy Details: If you are switching providers, bring your "Declarations Page" (the summary page of your current policy). This allows the broker to see your current coverage levels and identify potential gaps.
Managing Expectations: The Quote vs. The Reality
One of the most common frustrations for consumers is the discrepancy between an initial "estimated quote" and the "bindable premium." It is important to understand why this happens.
When you first ask for a quote, the broker may provide an estimate based on the information you provide. Once you decide to move forward, the broker submits your data to the insurance carrier's underwriting system. This system performs automated checks against credit-based insurance scores, driving history databases, and vehicle loss history. If these databases return results that differ from what was initially disclosed, the final premium offered by the carrier may be higher.
A competent broker will explain this process and help you contest any inaccuracies in the underlying data, such as a misreported accident or an incorrect credit score entry.
Navigating State-Specific Regulations
Auto insurance is highly regulated at the state level. Each state dictates the minimum liability limits, the requirements for Uninsured/Underinsured Motorist (UM/UIM) coverage, and the "no-fault" vs. "tort" status of insurance laws.
For instance, if you live in a "no-fault" state, your policy must include Personal Injury Protection (PIP) to cover your medical expenses regardless of who caused the accident. A local broker understands these nuances intimately. They can prevent you from purchasing "too little" insurance—which leaves you financially exposed—or "too much" coverage that provides no real benefit under your state's specific liability laws.
Frequently Asked Questions
1. Does using an insurance broker cost more than buying directly from an insurer? Not necessarily. In most cases, the insurance company pays the broker a commission that is already built into the premium. While some brokers charge a service fee, they often save you money by identifying discounts or finding a lower-cost carrier that you would not have found on your own.
2. Can an insurance broker help me if I have a "bad" driving record? Yes. Brokers are particularly valuable for high-risk drivers. Because they have access to "non-standard" insurance carriers that specialize in high-risk coverage, they can often find options for drivers who have been declined or heavily surcharged by the mainstream national carriers.
3. How often should I ask my broker to re-shop my policy? It is generally considered best practice to have your broker review your policy at every renewal period, or at least every 12 to 24 months. Changes in your personal life—such as adding a teenage driver, moving to a new ZIP code, or installing safety equipment—can significantly impact your rates.
4. What happens if my broker closes their office? If a broker closes their office or retires, your policy remains in force with the insurance carrier. You should be notified in writing regarding who will be managing your account. If you are unsatisfied, you generally have the right to request that your policy be transferred to a different agent or broker.
5. Are online quotes as reliable as quotes from a broker? Online quotes are excellent for getting a baseline idea of market pricing, but they are often based on "best-case scenario" inputs. A broker’s quote is usually more accurate because they verify your information and look for eligible discounts that an online form might overlook.
Final Next Steps
To begin your search, identify three independent brokers in your local area by searching your state’s DOI portal. Once you have a shortlist, schedule a brief introductory phone call. Ask them about the variety of carriers they represent and their experience with clients who share your specific driving profile. By prioritizing transparency and professional verification, you can establish a long-term relationship with a partner who will protect your financial interests on the road.

Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
