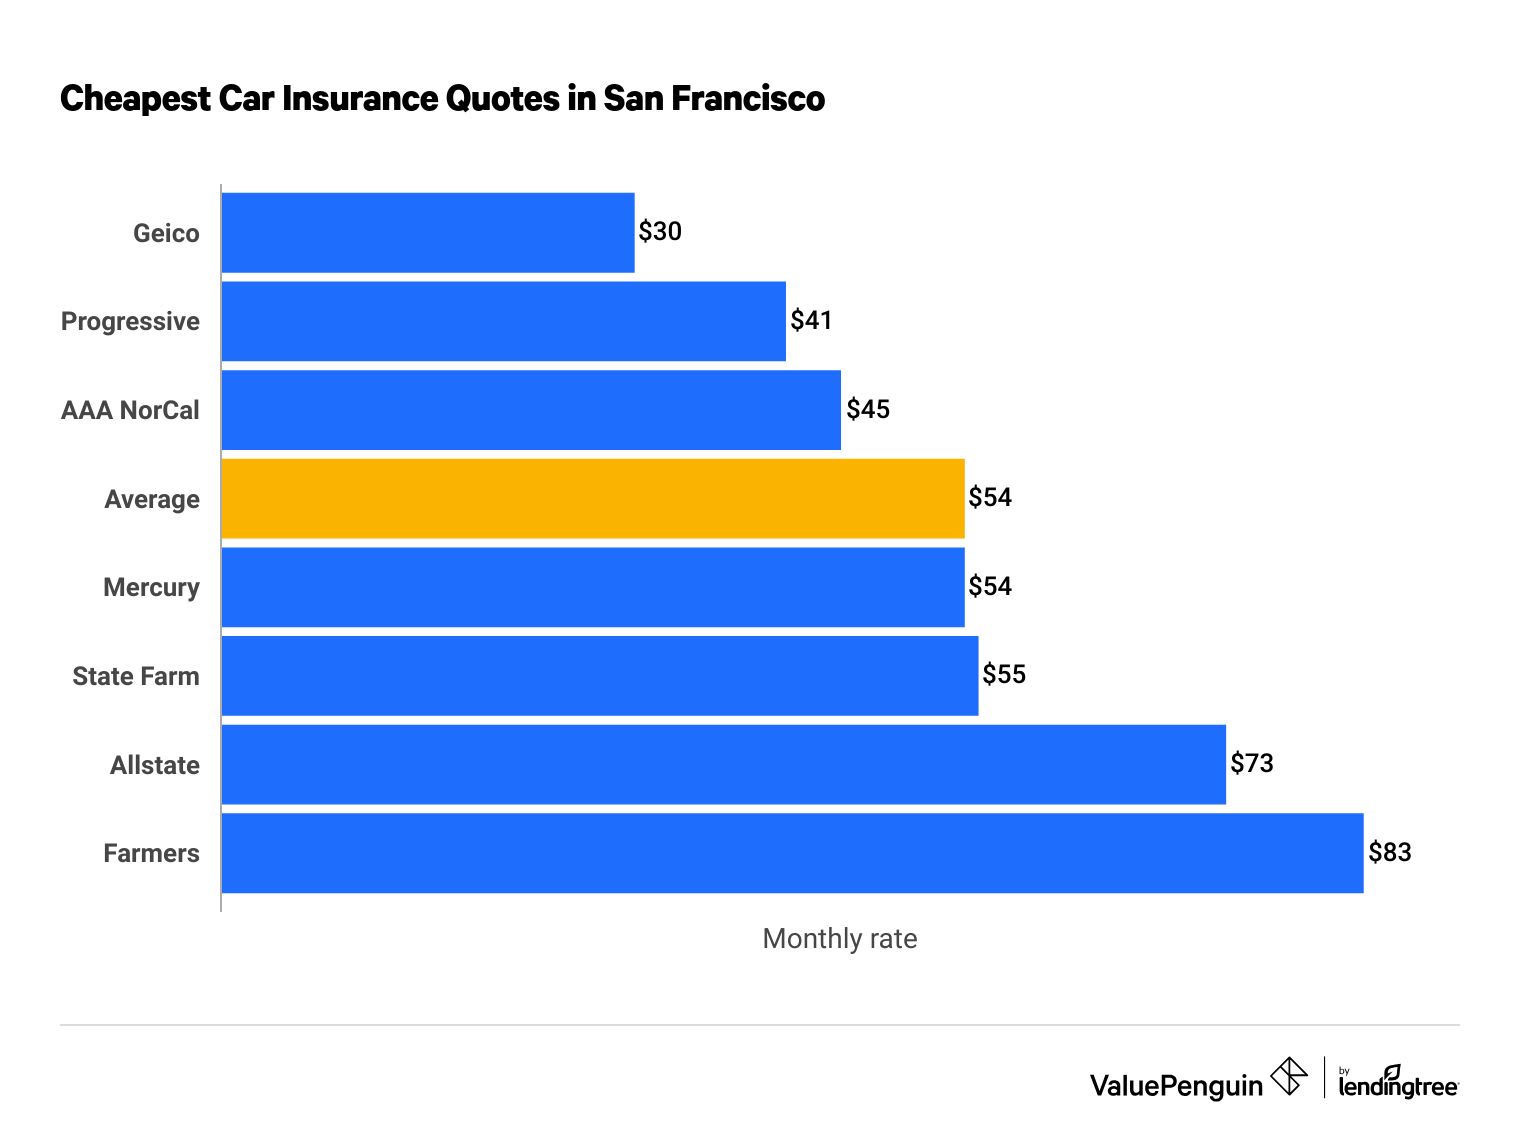
In 2026, drivers in San Francisco’s 94131 zip code face an average annual premium ranging from $1,850 to $3,100, influenced by California’s updated liability requirements and local density. Securing affordable coverage in neighborhoods like Diamond Heights and Glen Park requires navigating the state's revised minimum limits of 30/60/15 and accounting for specific urban risks like vehicle theft and steep-terrain accidents.
The 94131 Risk Profile: Geography and Infrastructure
The 94131 zip code is one of San Francisco's most geographically diverse areas, encompassing Diamond Heights, Twin Peaks, Glen Park, and portions of Noe Valley. From an actuarial perspective, this area presents a unique set of risks that differ significantly from the flat terrain of the Richmond District or the high-traffic density of SoMa.
Terrain and Weather Factors
The steep grades of Twin Peaks and the winding curves of O'Shaughnessy Boulevard contribute to a higher frequency of single-vehicle incidents and parking-related claims. In 2026, insurers continue to weigh the "hill factor" heavily; vehicles parked on the extreme inclines common in 94131 are statistically more prone to transmission strain and parking brake failures, which can lead to roll-away accidents. Furthermore, the persistent fog (famously known as "Karl") that blankets Twin Peaks often reduces visibility to near-zero levels, increasing the likelihood of rear-end collisions during morning and evening commutes.
Crime and Comprehensive Risk
While 94131 is generally more residential and less prone to the "smash-and-grab" epidemics seen in the city’s commercial cores, it is not immune. Rates for Comprehensive Coverage in this zip code are influenced by the city-wide trend of catalytic converter thefts and "bipping" (window smashing). However, because many homes in Glen Park and Diamond Heights offer off-street parking or private garages, residents who can verify secure parking often see a marginal reduction in their comprehensive premiums compared to those relying on street parking near the Glen Park BART station.
California’s Regulatory Landscape in 2026
The insurance market in California underwent a significant transformation between 2024 and 2026. Following the California Department of Insurance’s (CDI) "Sustainable Insurance Strategy," many providers that previously restricted new policies have returned to the market, albeit with higher rate structures.
The Impact of SB 1107
Drivers must be aware that as of 2026, the old California minimums of 15/30/5 are obsolete. Following the implementation of Senate Bill 1107, the mandatory minimum liability limits have increased to:
- $30,000 for bodily injury or death to one person.
- $60,000 for bodily injury or death to multiple people.
- $15,000 for property damage.
For drivers in 94131, where the average vehicle value is often higher than the state average, these minimums are frequently insufficient. A collision involving a high-end electric vehicle (EV) or a multi-car pile-up on Portola Drive can easily exceed $15,000 in property damage, leaving the driver personally liable for the deficit.
Prop 103 and the Good Driver Discount
California remains a "prior approval" state under Proposition 103, meaning the Insurance Commissioner must approve rate hikes. Crucially for 94131 residents, the Good Driver Discount is a mandatory 20% reduction for those who meet specific safety criteria over a three-year period. In 2026, maintaining a clean record is the most effective way to combat the rising cost of living in San Francisco.

Essential Coverage Types for 94131 Residents
Navigating the fog-slicked streets of San Francisco requires more than just the legal minimum. A robust policy for a 94131 driver should ideally include several specific protections.
Collision and Comprehensive Coverage
Due to the high cost of auto body labor in the Bay Area, which has seen nearly a 25% increase since 2023, collision coverage is essential for any vehicle valued over $5,000. Comprehensive coverage is equally vital for protecting against non-collision events such as falling trees (a risk in the eucalyptus-heavy areas of Glen Canyon Park) and theft.
Uninsured/Underinsured Motorist (UM/UIM)
Despite strict laws, a segment of the San Francisco driving population remains underinsured. If you are hit by a driver carrying only the 30/60/15 minimums, and your medical bills exceed those limits, UIM coverage bridges the gap. In a city with high medical costs like San Francisco, this is often considered the most critical "add-on" for personal financial protection.
MedPay vs. Personal Injury Protection
While California is not a "no-fault" state, Medical Payments (MedPay) coverage is highly recommended. It covers immediate medical expenses for you and your passengers regardless of fault, which is particularly useful for resolving small-scale injury claims quickly without waiting for lengthy liability investigations.
2026 Insurance Comparison for Zip Code 94131
The following table provides an estimate of coverage levels and costs for a standard driver (35 years old, clean record, commuting 10,000 miles/year) in the 94131 area.
| Coverage Level | Liability Limits (BI/PD) | Deductibles (Coll/Comp) | Estimated Annual Premium | Best For |
|---|---|---|---|---|
| State Minimum | $30k / $60k / $15k | N/A | $1,100 – $1,400 | Owners of older vehicles (>15 years) |
| Standard Policy | $50k / $100k / $50k | $1,000 / $1,000 | $1,900 – $2,300 | Average commuters, mid-range sedans |
| Executive/High Limit | $250k / $500k / $100k | $500 / $500 | $2,800 – $3,600 | Homeowners, EV owners, high-asset individuals |
| California Low Cost | $10k / $20k / $3k | N/A | $450 – $600 | Low-income drivers meeting strict eligibility |
Note: The California Low Cost Auto (CLCA) program provides an exception to standard minimums for income-eligible residents. Details can be found at the California Department of Insurance.
Factors Influencing Premiums in the 94131 Area
When an underwriter evaluates a 94131 application, they look beyond the zip code to specific micro-variables.
Annual Mileage and Commute Patterns
With many 94131 residents working in the Financial District or Silicon Valley, commute mileage is a primary rating factor. Drivers who utilize the Glen Park BART or the J-Church MUNI line and qualify for "pleasure use" rates (typically under 5,000 miles per year) can see premiums drop by as much as 15%. In 2026, verified mileage via telematics (tracking apps or OBD-II devices) has become a standard requirement for accessing the lowest tiers of pricing.
Vehicle Type: The EV Surge
San Francisco has one of the highest rates of electric vehicle adoption in the world. While EVs offer fuel savings, they are currently more expensive to insure in 2026 due to specialized repair requirements and high battery replacement costs. Tesla owners in 94131, for instance, often face higher premiums unless they utilize proprietary insurance products that track real-time driving behavior.
Claims History and Frequency
The frequency of "nuisance claims"—small claims for cracked windshields or minor bumper scrapes—can lead to non-renewal in the current market. Carriers in 2026 are increasingly selective. Residents of 94131 are advised to choose higher deductibles ($1,000 or $1,500) to lower their monthly costs and reserve insurance for significant, catastrophic losses rather than minor repairs.
How to Lower Your Rates in San Francisco
Despite the high-cost environment, there are several strategic ways to reduce auto insurance expenses in the 94131 zip code.
- Bundle Home and Auto: This remains the single most effective discount. With 94131 having high property values, placing your homeowners and auto insurance with the same carrier can result in a 10% to 25% discount across both policies.
- Affinity Group Discounts: Check for discounts related to your profession or education. Many insurers offer lower rates for engineers, educators, scientists, and members of the California State Bar.
- Defensive Driving Courses: Drivers over the age of 55 can complete a CDI-approved defensive driving course to receive a mandatory discount that lasts for three years.
- Telematics Participation: If you are a safe driver who avoids hard braking and late-night driving, opting into a "Pay-How-You-Drive" program can lead to significant savings. However, be aware that in 2026, some programs may also increase rates for "risky" behaviors.
- Secure Parking Verification: If you live in a newer development in Diamond Heights with a gated garage, ensure your agent has recorded this. It directly impacts the "comprehensive" portion of your premium by reducing the risk of theft.
The Role of Assigned Risk and Last-Resort Options
If you have a history of multiple at-fault accidents or a DUI, you may find it difficult to secure coverage in the private market. California provides a safety net through the California Automobile Assigned Risk Plan (CAARP).
CAARP is designed for drivers who have been turned down by private carriers. While the premiums are higher and the service is less personalized, it ensures that every driver in 94131 can meet the legal requirements to operate a vehicle. For more information on eligibility, drivers should consult the CAARP official portal.
Frequently Asked Questions (FAQ)
Why is my insurance higher in 94131 than in the Sunset District?
Insurance rates are calculated based on specific "territory" data. While 94131 is residential, its proximity to major transit arteries like I-280 and the high density of hills leads to a different claim frequency than the flatter, more grid-like Sunset District. Additionally, repair costs in the specialized shops serving the Glen Park and Noe Valley areas tend to be higher.
Do I need GAP insurance for my new car in San Francisco?
If you are financing or leasing a new vehicle in 2026, GAP insurance is highly recommended. Because vehicles depreciate the moment they are driven off the lot, and San Francisco has a high rate of total-loss accidents (often involving multi-car collisions or theft), GAP insurance covers the difference between the car's actual cash value and what you owe the lender.
Does my policy cover damage from "Karl the Fog" or fallen trees?
Damage from falling trees or branches (common during the winter atmospheric river storms in 94131) is covered under the Comprehensive portion of your policy, not Collision. Similarly, if moisture from persistent fog causes electrical issues (though rare), it would fall under comprehensive. Note that "wear and tear" from salt air or fog is generally not covered.
Can I get a discount for driving an electric vehicle?
Many insurers offer an "Alternative Fuel" discount, typically around 5%. However, this discount is often offset by the higher base cost of insuring EVs due to their expensive components. In 2026, the best way to save on EV insurance in San Francisco is to look for carriers that offer specialized "green" vehicle packages.
What should I do if my insurer non-renews my policy in 2026?
If you receive a non-renewal notice, do not panic. Under California law, insurers must provide at least 30 days' notice. Immediately begin shopping for quotes, as many carriers have reopened their "books" in 2026. If you cannot find coverage, contact the California Department of Insurance for assistance or look into the CAARP program.
Practical Next Action for 94131 Drivers
To ensure you are receiving the most competitive rate for 2026, perform a coverage audit of your current policy. Verify that your annual mileage is accurately reported—especially if your work-from-home status has changed—and ensure you are carrying the new SB 1107 mandated limits of 30/60/15. Contact an independent agent who specializes in the San Francisco market to compare at least three highly-rated California carriers, focusing on those with high "claims satisfaction" ratings from JD Power.
Image Gallery
Select an image to open it in a new tab.


Celine Dubois
Contemporary Living and Global Arts Columnist
