Understanding VA Home Loans in Maine: A Comprehensive Guide for Veterans and Service Members

Securing a VA home loan in Maine offers eligible service members, veterans, and surviving spouses a powerful pathway to homeownership with zero down payment requirements, competitive interest rates, and relaxed credit standards. Navigating this process in the Pine Tree State involves understanding both federal Department of Veterans Affairs guidelines and regional real estate nuances, from historic coastal properties to rural inland acreage.
Introduction to VA Home Loans in Maine
A VA home loan is a mortgage loan guaranteed by the United States Department of Veterans Affairs, issued by qualified private lenders such as banks, credit unions, and specialized mortgage companies. In Maine, these loans help eligible borrowers bypass traditional mortgage hurdles, most notably the requirement for a massive 20 percent down payment.
For home buyers looking at Maine's distinct housing landscape—ranging from Portland's competitive urban market to rural communities across Aroostook or Washington counties—the VA loan program eliminates major financial barriers. Because the federal government guarantees a portion of the loan, lenders can offer more favorable terms, including the absence of private mortgage insurance (PMI). However, prospective buyers must navigate specific certificate requirements, local property condition evaluations, and unique regional factors like well-and-septic inspections common in Maine.
Eligibility Requirements and Certificate of Eligibility (COE)
Before shopping for homes in Maine, applicants must confirm their eligibility and obtain a Certificate of Eligibility (COE) from the VA. Eligibility is generally determined by length of service, duty status, and the nature of discharge.
Minimum Service Requirements
- Wartime Veterans: Generally require 90 consecutive days of active duty service.
- Peacetime Veterans: Generally require 181 continuous days of active duty service.
- National Guard and Reserve Members: Generally require 6 years of service, or 90 days of active service under specific Title 10 or Title 32 orders.
- Surviving Spouses: Unremarried surviving spouses of veterans who died while on active duty or as a result of a service-connected disability may also qualify.
How to Obtain Your COE
Borrowers can obtain a COE online through the official U.S. Department of Veterans Affairs eBenefits portal, via mail using VA Form 26-1880, or often instantaneously through their chosen lender using the VA's automated web-based interface. Having this document ready is a mandatory prerequisite for formal loan pre-approval.
Financial and Credit Qualifications
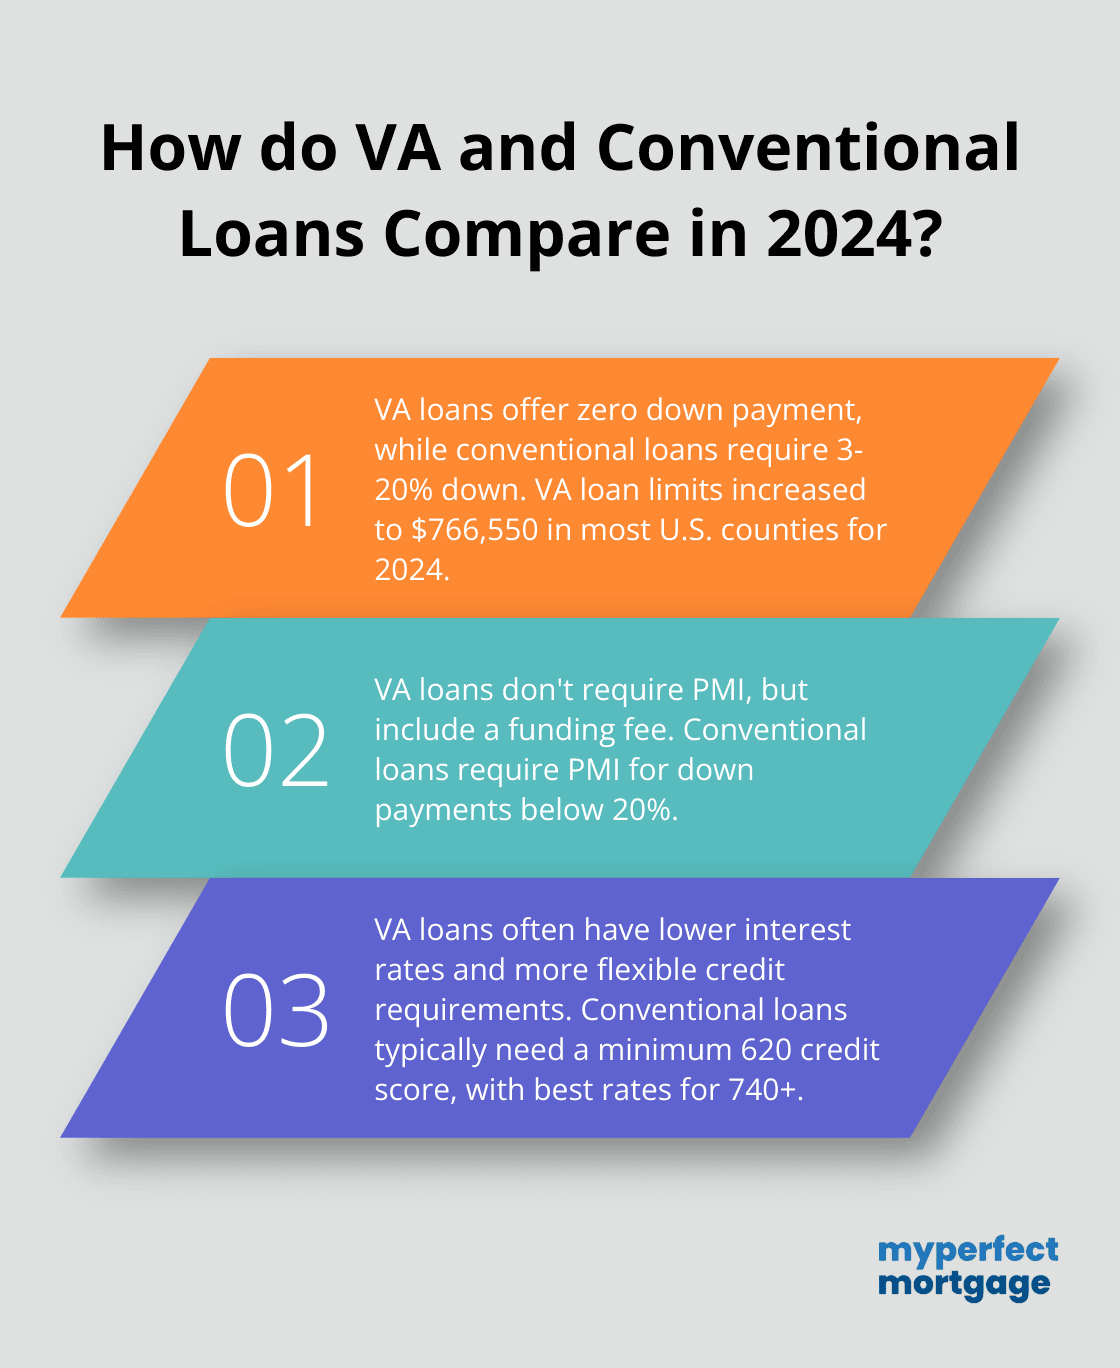
While the VA does not set a minimum credit score requirement, individual lenders participating in the program usually establish their own baseline criteria, known as "overlays." Most Maine lenders look for a credit score of 620 or higher, though some flexible portfolio lenders accommodate lower scores with compensating factors.
Key Financial Parameters
- Debt-to-Income (DTI) Ratio: The VA prefers a DTI ratio of 41 percent or lower. However, this is flexible if the borrower demonstrates residual income—the cash remaining each month after paying major living expenses, taxes, and debt.
- Residual Income Requirements: Maine falls under the Northeast region guidelines for residual income calculations, which vary based on family size and loan amounts. Lenders carefully verify these figures to ensure long-term affordability.
- No Private Mortgage Insurance (PMI): Unlike conventional loans that penalize down payments under 20 percent with monthly PMI fees, VA loans completely exempt borrowers from this expense, lowering monthly housing costs significantly.
The VA Funding Fee Explained
Although VA loans do not require a down payment, most borrowers must pay a one-time VA funding fee. This fee directly supports the sustainability of the loan program for future generations of service members.
- First-Time Use: For zero-down-payment purchases, the standard funding fee is 2.15 percent of the total loan amount. If a down payment of 5 percent or more is made, the fee percentage drops.
- Subsequent Use: For buyers using their VA loan benefit a second or subsequent time with zero down, the funding fee increases to 3.3 percent.
- Exemptions: Veterans receiving VA disability compensation are completely exempt from paying the funding fee. This exemption represents a substantial upfront savings during closing.
The funding fee does not need to be paid in cash at closing; most borrowers choose to finance it by rolling the fee directly into their total loan amount.
Property Types and Maine-Specific Appraisal Standards
Not every property qualifies for a VA loan. The home must serve as the borrower's primary residence; investment properties, vacation homes, and purely commercial real estate are ineligible.
Eligible Property Categories
- Single-family detached homes.
- Condominiums approved by the VA.
- Manufactured homes on permanent foundations.
- Multi-unit properties (up to four units, provided the veteran occupies one unit).
Minimum Property Requirements (MPRs) in Maine
The VA requires an independent appraisal to ensure the home is safe, structurally sound, and sanitary. In Maine, these Minimum Property Requirements (MPRs) frequently intersect with regional housing characteristics:
| Property Inspection Element | Maine-Specific Consideration | VA Requirement Impact |
|---|---|---|
| Water Source | Many rural Maine homes rely on private wells. | Water potability tests are routinely required by the appraiser. |
| Wastewater Disposal | Septic systems are standard outside urban municipal sewers. | Systems must function properly; failed or failing leach fields will halt loan approval until repaired. |
| Heating Systems | Maine winters demand reliable, permanent heat sources. | Wood stoves alone are rarely sufficient; properties must feature a central or permanently installed heating system capable of maintaining a baseline temperature of 50°F. |
| Lead Paint | Historic New England homes often contain lead-based paint. | Peeling or chipping paint on homes built prior to 1978 must be scraped and repainted before closing. |
Step-by-Step Purchasing Process in Maine
Navigating the real estate market in Maine with a VA loan follows a structured sequence from initial preparation to the closing table.
- Check Eligibility & Secure COE: Gather service documents and secure your Certificate of Eligibility.
- Obtain VA Pre-Approval: Work with a loan officer experienced in VA transactions to establish your maximum purchasing budget.
- Partner with a Real Estate Agent: Choose an agent familiar with VA financing and local Maine micro-markets.
- House Hunting: Tour eligible primary residences, keeping VA property standards in mind.
- Make an Offer: Submit a purchase and sale agreement that includes a VA Amendatory Clause, protecting your earnest money if the property appraises below the purchase price.
- Underwriting and VA Appraisal: The lender orders a specialized VA appraisal. If repairs are mandated by the appraiser, negotiations determine who completes them prior to final sign-off.
- Closing: Sign final loan documents, pay closing costs (which are strictly limited by the VA), and receive the keys to your new Maine home.
Frequently Asked Questions
Can I use a VA loan more than once?
Yes, the VA loan benefit is a lifetime benefit that can be reused multiple times. If you sell your previous home and pay off the prior VA loan, your full entitlement is restored. It is also possible to have two active VA loans simultaneously under specific "bonus entitlement" rules, provided you meet income and residual requirements.
Are closing costs lower with a VA loan?
Yes and no. While lender fees are capped by the VA (lenders cannot charge arbitrary administrative fees), borrowers still pay standard third-party closing costs such as title insurance, municipal recording fees, and prepaid property taxes. Furthermore, sellers in Maine are permitted to pay up to 4 percent of the purchase price in "concessions" to help cover these buyer closing costs.
What happens if the home appraises for less than the purchase price?
If the official VA appraisal comes in lower than the agreed purchase price, the buyer has several options. They can renegotiate the purchase price down with the seller, bring cash to the table to cover the difference between the appraisal and the sale price, or walk away from the deal without penalty thanks to the mandatory VA Amendatory Clause.
Can I buy a fixer-upper in Maine using a VA loan?
Standard VA purchase loans require the home to meet MPRs on day one. However, borrowers can utilize a VA Renovation Loan (or a VA Energy Efficient Mortgage) to finance both the purchase of a home and the cost of necessary repairs or energy upgrades—such as modern insulation or upgraded heating systems—into a single monthly mortgage payment.
Next Actions for Prospective Maine Homebuyers
Begin your journey by logging into the VA eBenefits portal to download your Certificate of Eligibility. Simultaneously, interview multiple mortgage lenders—including local Maine credit unions and national institutions—to compare interest rates, origination fees, and customer service records. Partnering with professionals who deeply understand both the intricacies of the VA loan program and the unique demands of the Maine real estate market will ensure a smooth, successful transition into your new home.
Image Gallery
Select an image to open it in a new tab.
Celine Dubois
Contemporary Living and Global Arts Columnist
