
QBE North America provides specialized workers’ compensation insurance designed to protect US-based businesses from the financial impact of workplace injuries. By 2026, QBE has further integrated predictive analytics and high-touch claims management into its offerings, focusing on reducing long-term loss costs through aggressive risk control and structured return-to-work programs for middle-market and large enterprises.
Understanding QBE’s Position in the US Workers' Compensation Market
QBE Insurance Group is a top-tier global insurer, and its North American division operates as a significant player in the United States commercial insurance landscape. Unlike carriers that focus on high-volume, small-business "BOP" (Business Owner Policy) products, QBE focuses on specialized markets and mid-to-large-sized corporations. In 2026, QBE remains a preferred choice for businesses with complex risk profiles that require more than just a basic insurance certificate.
Workers' compensation is a statutory requirement in nearly every US state, mandating that employers provide benefits to employees who suffer job-related injuries or illnesses. QBE fulfills this requirement by offering a combination of financial indemnity and medical care management. The QBE approach is built on the philosophy of "Outcome-Based" management, which prioritizes the health of the worker to ensure a faster, safer return to productivity, thereby lowering the total cost of risk for the employer.
The company’s US operations are characterized by a decentralized underwriting model that allows for localized expertise. This is critical in workers' compensation because regulations, benefit levels, and legal environments vary significantly from New York to California. By maintaining regional specialists, QBE can tailor policies that comply with specific state mandates while addressing the unique industrial risks of a specific geography.
Core Coverage Components and Policy Structure
A standard QBE workers’ compensation policy in the USA is divided into two primary sections, as dictated by the National Council on Compensation Insurance (NCCI) or individual state bureaus.
Part One: Workers' Compensation (Statutory)
This section has no dollar limit. It covers all medical expenses, rehabilitation costs, and lost wages as defined by the state's labor laws. If an employee is injured on the job in 2026, QBE pays the medical providers directly and issues disability payments to the employee based on the state’s calculated average weekly wage (AWW). There are no deductibles for the employee, and the "no-fault" nature of the system means the employee receives benefits regardless of who caused the accident, in exchange for relinquishing the right to sue the employer for negligence.
Part Two: Employers’ Liability
While Part One covers statutory benefits, Part Two protects the business against lawsuits that fall outside the "exclusive remedy" of workers' compensation. This includes "dual capacity" suits, "consequential bodily injury" to family members, or "third-party over" actions where an equipment manufacturer blames the employer for a machine-related injury. QBE typically offers limits such as $500,000 or $1,000,000 for these occurrences, though higher limits can often be negotiated through excess layers.
Specialized Industry Vertical Focus
QBE does not attempt to be everything to everyone. Instead, they focus on industry verticals where their risk control expertise provides a competitive advantage. In 2026, their primary targets include:
- Manufacturing: From precision machining to food processing, QBE addresses the risks of repetitive motion injuries, machine guarding, and hazardous material exposure.
- Construction: Focusing on mid-market contractors, QBE provides coverage for trade-specific risks, including fall protection and heavy equipment operation.
- Healthcare and Social Services: This includes hospitals, nursing homes, and outpatient facilities. QBE emphasizes ergonomics and "safe patient handling" to reduce back and shoulder injuries, which are the most common claims in this sector.
- Professional Services and Wholesale: Even for low-hazard industries, QBE provides robust coverage for multi-state operations, ensuring that remote workers in 2026 are covered under the appropriate state jurisdiction.
The QBE Risk Control Advantage
One of the primary reasons businesses choose QBE is for their Loss Control and Risk Management services. Rather than simply acting as a financial backstop, QBE partners with businesses to prevent injuries from occurring.
On-Site Safety Consultations
QBE risk professionals conduct physical surveys of work sites to identify latent hazards. In 2026, this includes the use of wearable technology data and AI-driven site analysis to predict where accidents are most likely to occur. They provide actionable reports that help safety managers improve compliance with OSHA standards.
Ergonomic Assessments
Musculoskeletal disorders (MSDs) represent a significant portion of workers' compensation costs. QBE offers specialized ergonomic assessments for both industrial and office environments. By optimizing workstations and tool usage, companies can significantly reduce the frequency of "wear and tear" injuries that often lead to expensive, long-term claims.
Safety Training Resources
Policyholders gain access to the QBE "Loss Control Platform," a digital library of training modules, safety posters, and toolbox talk outlines. This helps businesses maintain a "culture of safety," which is often a prerequisite for favorable underwriting terms and lower premiums during renewal periods.
Claims Management and Medical Excellence
When an injury occurs, the efficiency of the claims process determines the final cost of the claim. QBE utilizes a "Three-Point Contact" system, ensuring that within 24 hours of a claim being filed, the adjuster speaks with the employer, the injured worker, and the medical provider.
Medical Provider Networks (MPN)
QBE has established a nationwide network of preferred medical providers who specialize in occupational medicine. These doctors understand the goal of returning a worker to "modified duty" rather than keeping them off the clock indefinitely. In 2026, QBE's network includes integrated tele-health options, allowing injured workers in rural areas or those with minor injuries to consult with specialists via mobile devices immediately.
Pharmacy Benefit Management (PBM)
To combat the rising cost of medications and the risks associated with opioid use, QBE employs a strict PBM. This system flags high-cost drugs or potentially dangerous drug combinations at the point of sale. Adjusters and nurse case managers work closely with physicians to ensure that prescriptions are necessary, safe, and cost-effective.
Early Intervention and Nurse Case Management
For complex or catastrophic injuries, QBE assigns a Field Nurse Case Manager (FNCM). These professionals attend doctor appointments with the injured worker to ensure the treatment plan is progressing and that there are no barriers to recovery. This high-touch approach prevents claims from "languishing" in the system, which is where the most significant financial losses usually occur.
Digital Tools and Policyholder Portals in 2026
The QBE Customer Portal has evolved into a comprehensive management suite for 2026 policyholders. Through this interface, business owners and HR managers can perform several critical tasks:
- Real-Time Claims Reporting: Employers can file a First Report of Injury (FROI) digitally, which immediately triggers the claims assignment process.
- Loss Run Analysis: Users can generate reports showing their claims history, identifying trends in injury types or specific departments that may need additional safety training.
- Certificate of Insurance (COI) Management: For contractors and service providers, the ability to generate and send COIs to clients instantly is a vital operational feature.
- Premium Audit Support: The portal allows for the digital submission of payroll records, making the annual premium audit process faster and less intrusive.
Premium Determination and Cost Factors
The cost of QBE workers' compensation insurance is not a flat fee; it is a calculated rate based on several variables. Understanding these can help a business lower its annual spend.
| Factor | Description | Impact on Premium |
|---|---|---|
| Classification Codes | Categories assigned by NCCI based on job duties (e.g., 8810 for Clerical vs. 5022 for Masonry). | Higher risk codes carry significantly higher rates per $100 of payroll. |
| Experience Rating (Mod) | A multiplier based on the company's past 3 years of claims history compared to the industry average. | A "Mod" below 1.00 provides a discount; above 1.00 results in a surcharge. |
| Payroll (Exposure) | The total remuneration paid to employees. | Premiums are calculated as (Rate x Payroll / 100) x Mod. |
| Schedule Rating | Credits or debits applied by the underwriter based on specific safety programs or management quality. | Can lead to up to 25% variations in final pricing. |
| State Mandated Surcharges | Taxes or assessments applied by individual states to fund second-injury funds or administrative costs. | Generally non-negotiable and vary by state. |
Loss-Sensitive vs. Guaranteed Cost Programs
For larger organizations in 2026, QBE offers alternatives to the traditional "Guaranteed Cost" model.
Guaranteed Cost
This is the standard insurance model where the employer pays a set premium regardless of the number of claims. It provides budget certainty but offers no immediate financial reward for a safe year, other than a future improvement in the Experience Modifier.
Large Deductible Programs
Under this structure, the employer agrees to pay the first $100,000 or $250,000 of every claim. In exchange, QBE significantly reduces the upfront premium. This is ideal for companies with strong balance sheets and high confidence in their safety programs. QBE still handles the claims administration, but the employer reimburses QBE for the losses within the deductible layer.
Retrospective Rating (Retro)
A "Retro" plan adjusts the premium after the policy period based on actual losses. If claims are low, the employer receives a refund. If claims are high, the employer pays an additional premium up to a pre-set maximum. This aligns the interests of QBE and the employer perfectly toward safety.
Frequently Asked Questions
How do I report a new claim to QBE?
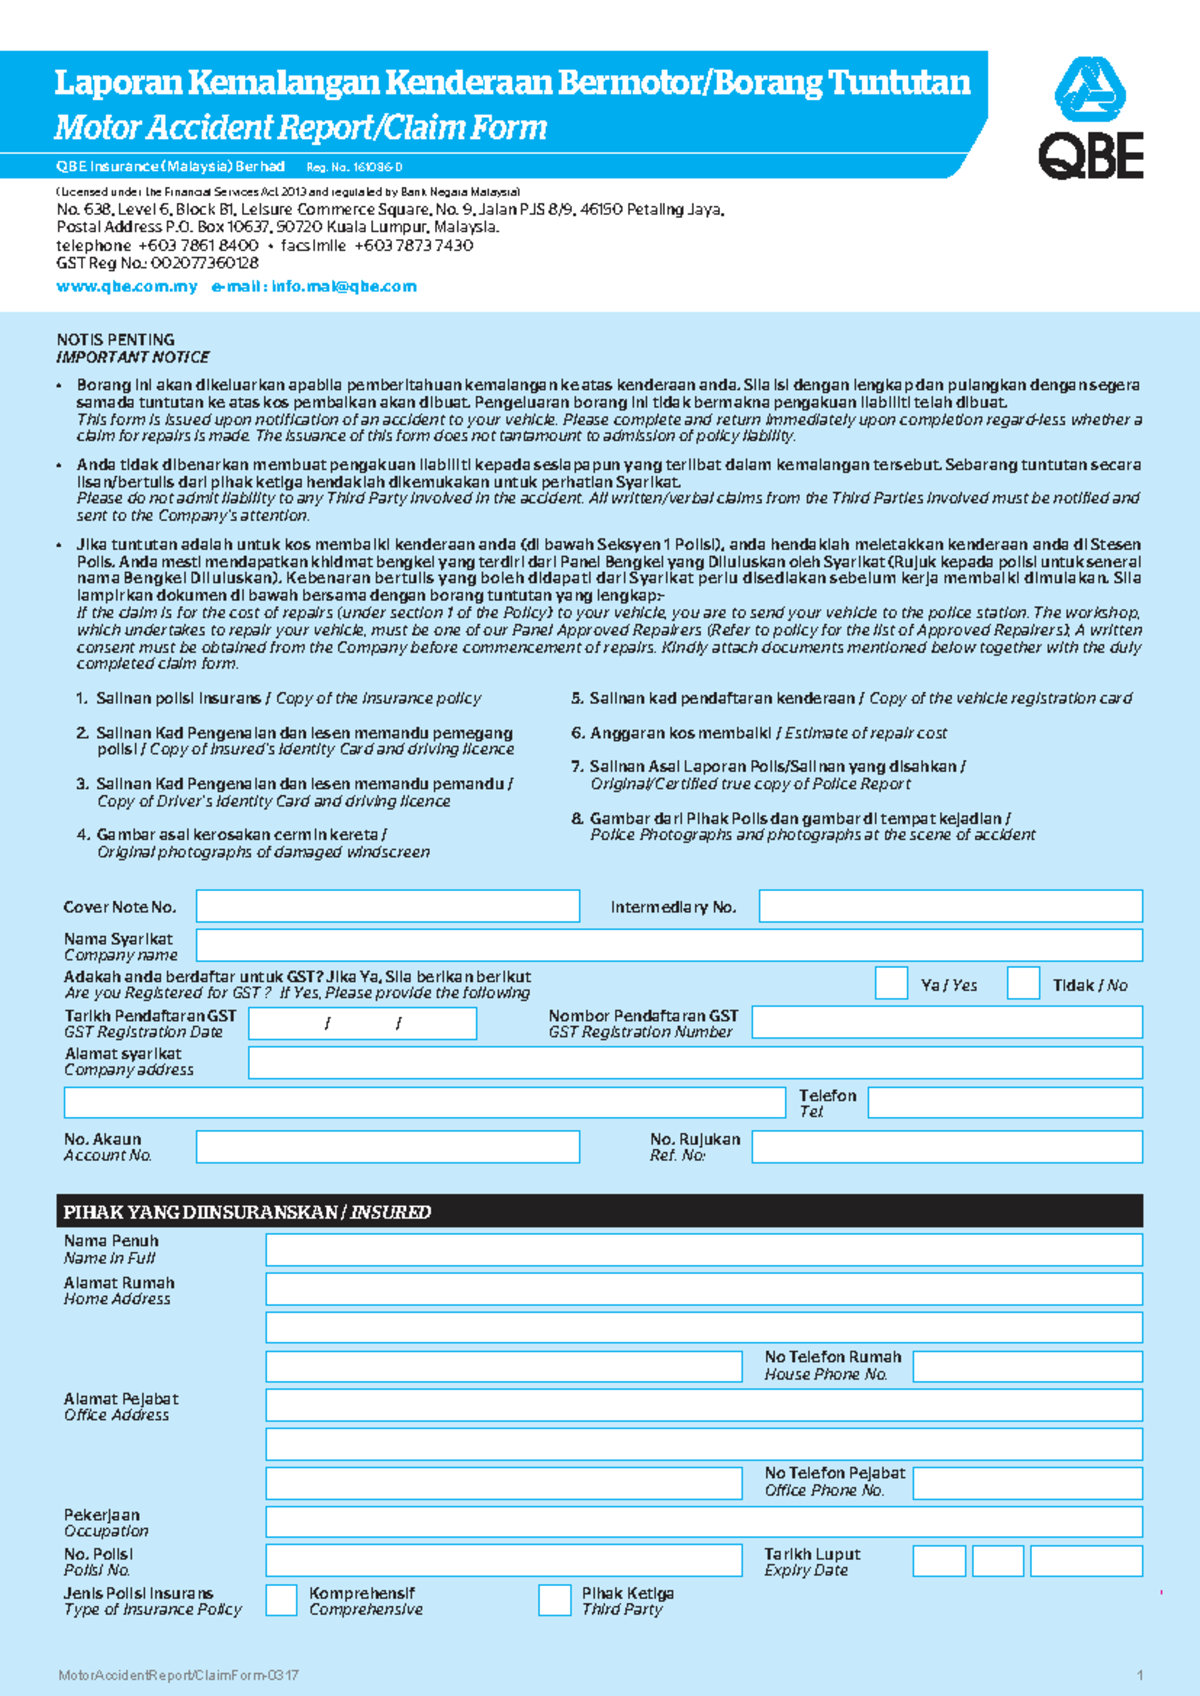
In 2026, QBE encourages reporting through their online portal or mobile app for the fastest response. However, you can also report via their 24/7 claims hotline. You should have the employee’s social security number, date of injury, and a description of the incident ready. Early reporting (within 24 hours) is statistically linked to lower claim costs.
Does QBE provide coverage for remote workers in different states?
Yes. QBE specializes in multi-state policies. If your business is headquartered in Texas but has remote employees in Florida and New York, QBE can include all states on a single policy (excluding "monopolistic" states like Ohio or Washington, where you must buy from the state fund). It is vital to notify your broker of all states where work is performed to ensure valid coverage.
What should I expect during a QBE premium audit?
At the end of the policy term, QBE will conduct an audit to verify that the estimated payroll used to set the premium matches actual records. You will need to provide 941s, payroll journals, and proof of insurance for any subcontractors you hired. Using the QBE digital audit portal in 2026 can often complete this process in a few days without an on-site visit.
What is the "QBE Choice" provider network?
The QBE Choice network is a curated group of medical facilities and physicians who have demonstrated superior clinical outcomes in treating occupational injuries. Using these providers ensures that injured workers receive evidence-based care and that employers receive timely updates on work status and restrictions.
Can QBE help with OSHA compliance?
While QBE is not a regulatory body, their risk control team provides "mock OSHA audits" and compliance checklists. They help you identify gaps in your safety programs that could lead to government fines, though the ultimate responsibility for OSHA compliance remains with the employer.
How does QBE handle fraudulent claims?
QBE utilizes a dedicated Special Investigations Unit (SIU) that employs data mining and surveillance to identify suspicious patterns. In 2026, their AI systems can flag "red-flag" claims (such as injuries reported on a Monday morning or claims from employees in the midst of disciplinary action) for immediate investigation, protecting the employer’s Experience Modifier from illegitimate costs.
Practical Recommendations for Employers
To maximize the value of a QBE workers' compensation policy in 2026, businesses should move beyond treating insurance as a passive expense. The most successful organizations are those that actively engage with QBE’s risk control department. Start by requesting a "Loss Trend Analysis" to see where your money is actually going. If the data shows a spike in slip-and-fall injuries, use QBE's resources to implement a floor-safety program.
Furthermore, establish a "Return to Work" (RTW) policy before an injury occurs. QBE provides templates for this. Having a plan to bring an injured worker back in a "light duty" capacity—such as performing administrative tasks or safety monitoring—can save thousands of dollars in "temporary total disability" payments and keep your Experience Modifier low. Finally, work with an independent broker who has a direct appointment with QBE to ensure your business is classified correctly, as a single misclassification code can result in thousands of dollars in unnecessary premium.
Image Gallery
Select an image to open it in a new tab.

Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
