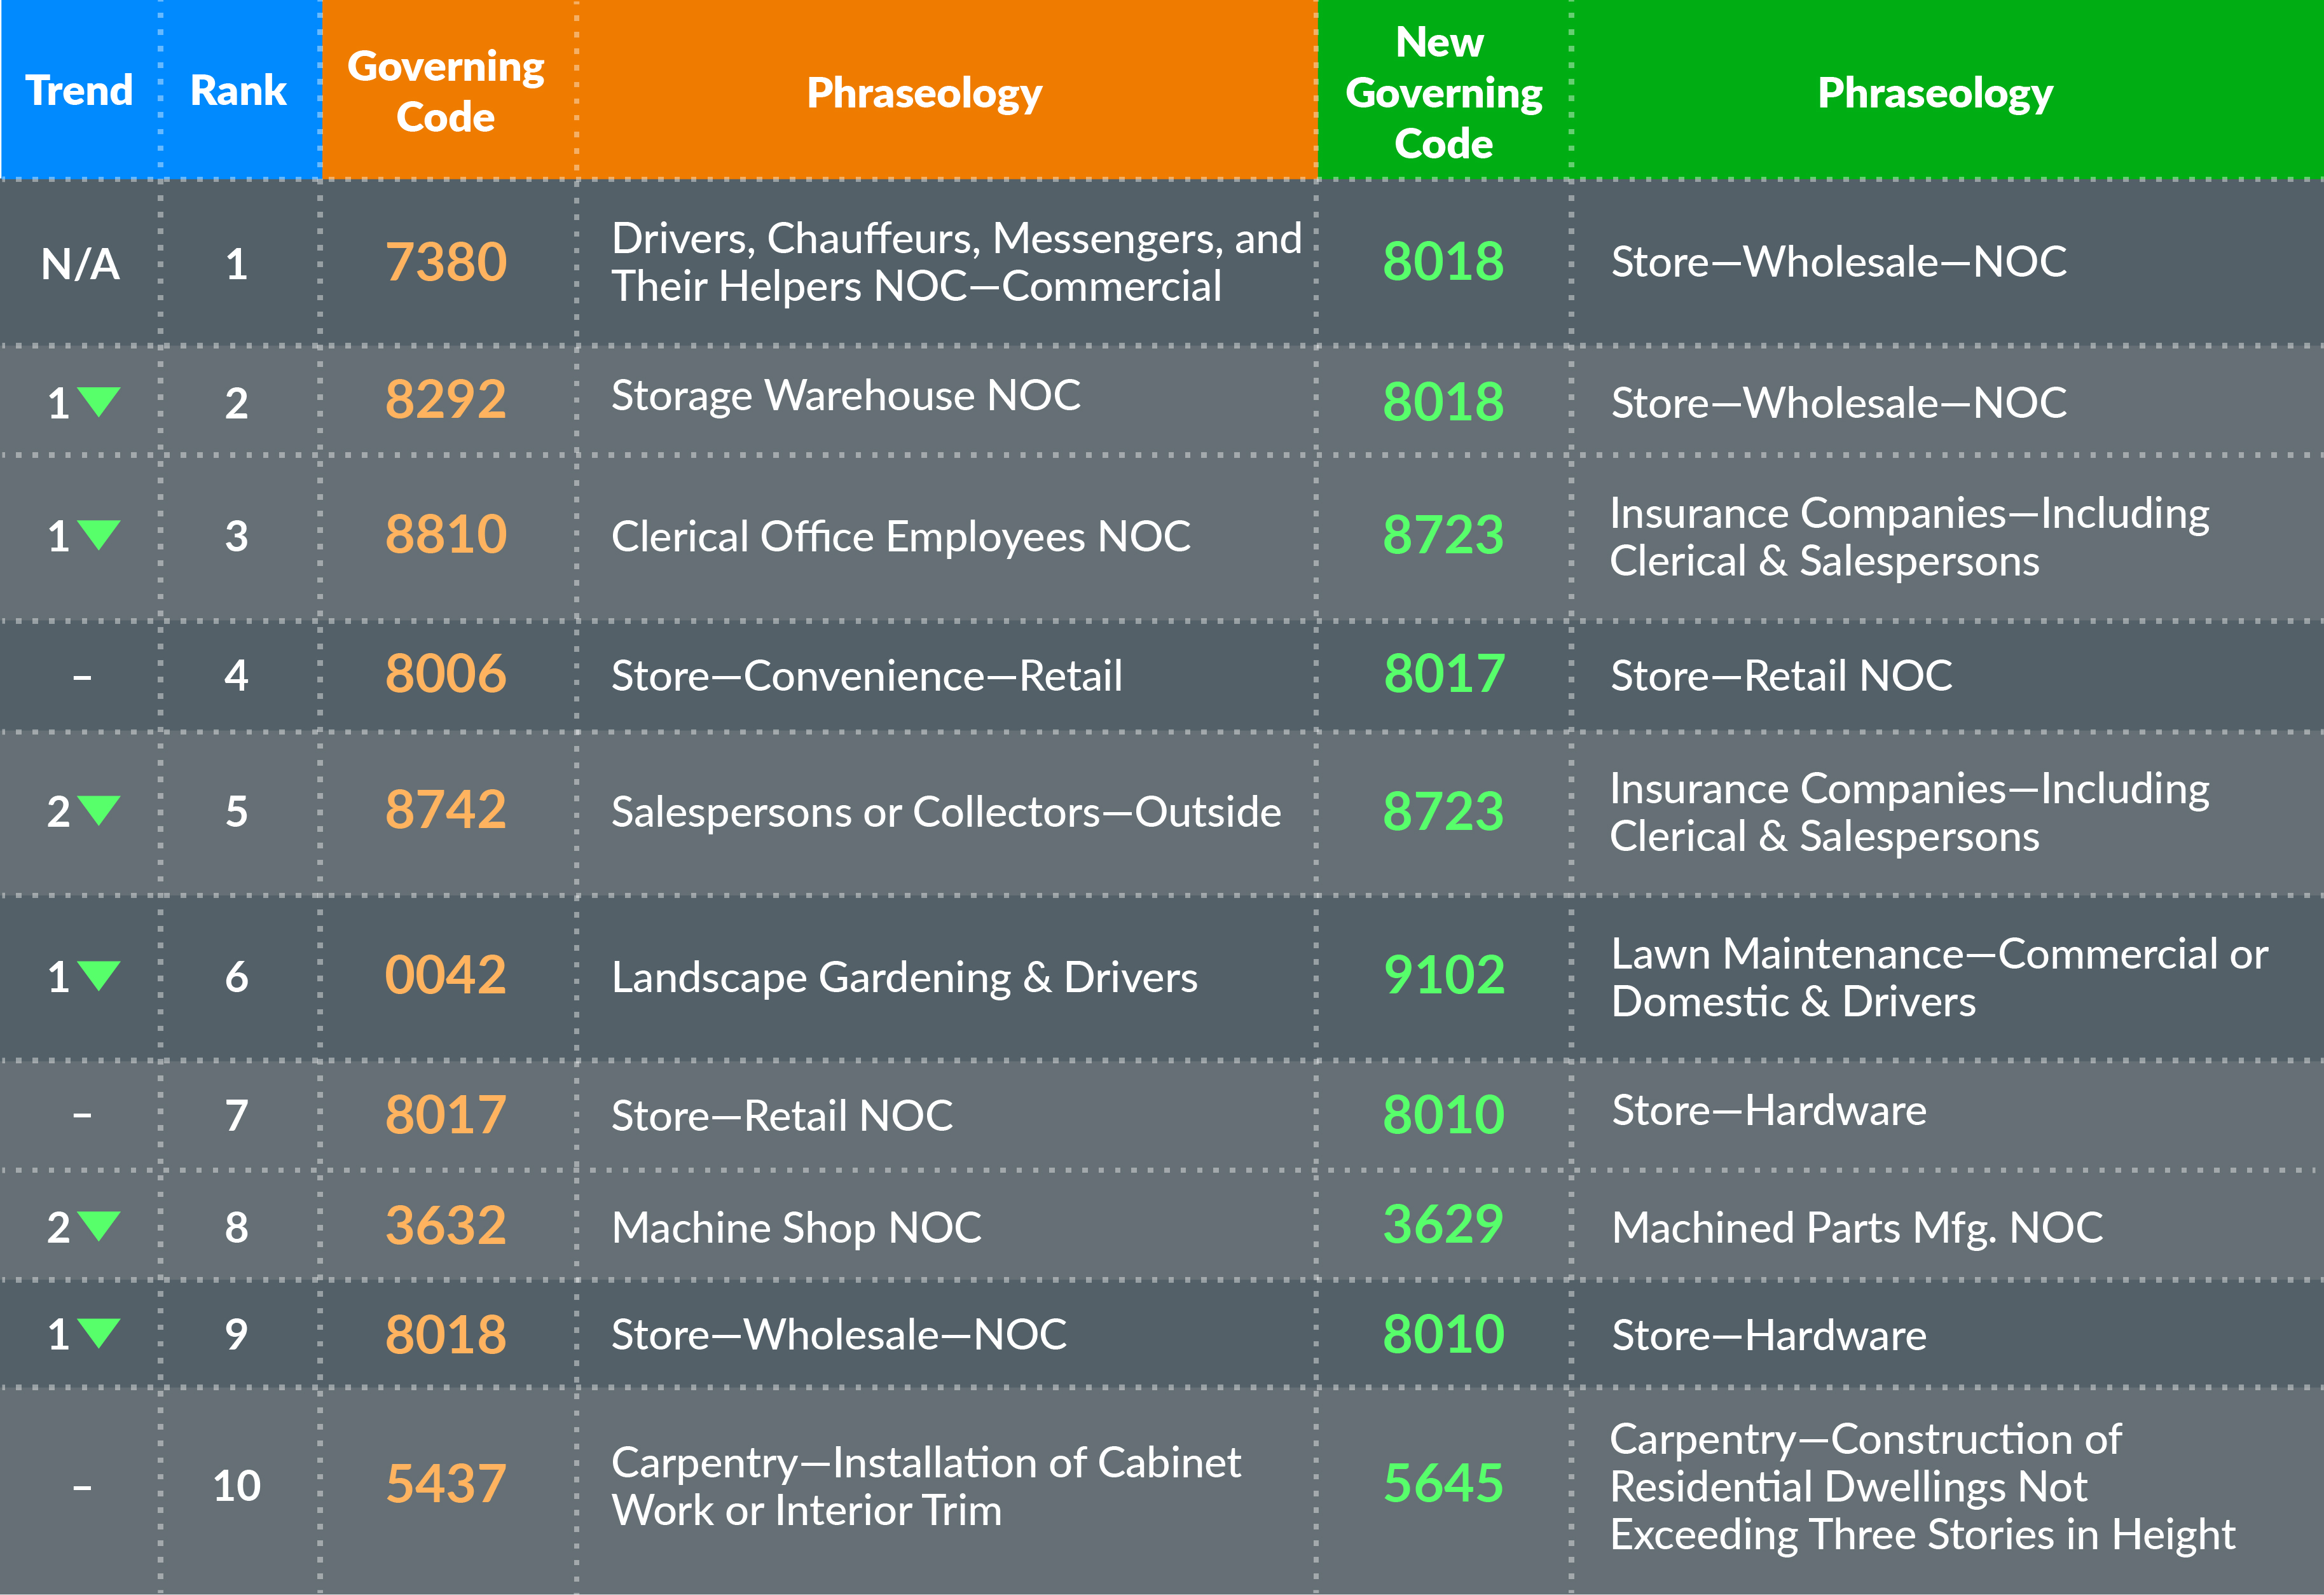
Pennsylvania workers' compensation class codes are four-digit numeric identifiers assigned by the Pennsylvania Compensation Rating Bureau (PCRB) to categorize business operations based on risk levels. These codes directly determine the premium rates employers pay for workers' compensation insurance, reflecting the statistical likelihood of occupational injuries within specific industry sectors or job roles.
The Role of the PCRB in Pennsylvania
The Pennsylvania Compensation Rating Bureau (PCRB) is the licensed rating organization responsible for the development and administration of workers' compensation insurance rules and classifications in the Commonwealth. Unlike some states that adopt the National Council on Compensation Insurance (NCCI) system, Pennsylvania maintains its own specific classification system tailored to the unique economic and industrial landscape of the state.
The PCRB operates under the authority of the Pennsylvania Insurance Department. Its primary mandate is to ensure that insurance premiums are equitable, non-discriminatory, and sufficient to cover the costs of anticipated claims. By utilizing class codes, the Bureau creates a standardized language that insurers use to calculate risk. When you purchase a policy, your insurer applies the PCRB-approved rate for your specific class code to your total payroll, which serves as the fundamental basis for your annual premium.
How Class Codes Are Determined
Classification is not an arbitrary process. It is governed by the Pennsylvania Workers' Compensation Insurance Manual, which outlines the scope of various business activities. Determining the correct class code depends on the "governing classification" of your business.
The governing classification is the code that describes the business's primary operation. For example, if a business manufactures machinery, the employees involved in the assembly, packaging, and shipping are generally included under one primary manufacturing code. However, the system is designed to capture risk accurately; if a company maintains a distinct, secondary operation that is not normally incidental to the primary business (such as a large construction firm running a retail storefront), those employees may be eligible for a separate class code that better reflects their actual job duties.
The Mechanism of Premium Calculation
Workers' compensation insurance is essentially a payroll tax based on risk. The calculation follows a standard formula:
(Payroll ÷ 100) × Classification Rate × Experience Modifier = Manual Premium
- Payroll: This is the total remuneration paid to employees.
- Classification Rate: This is the rate assigned by the PCRB for your specific four-digit code.
- Experience Modifier (E-Mod): This is a multiplier based on your company’s individual claims history compared to the industry average. A business with a high number of claims will have an E-Mod higher than 1.0, effectively increasing their premium, while a business with fewer claims may see a reduction.
Because the class code rate is the core of this equation, an incorrect classification can lead to thousands of dollars in overpayment or, conversely, an audit that results in significant back-premiums and penalties.
Common Classification Scenarios and Examples
To understand the breadth of the system, it is helpful to look at how different risk profiles are treated. The PCRB maintains hundreds of codes, ranging from low-risk office work to high-risk structural steel erection.
| Industry Segment | Representative Code | Typical Risk Profile |
|---|---|---|
| Clerical Office | 953 | Low; primarily sedentary work, minimal physical hazard. |
| Restaurant/Dining | 917 | Moderate; risks involving kitchen equipment, slips, and burns. |
| Carpentry (Interior) | 651 | High; use of power tools, risk of falls, material handling. |
| Software Development | 951 | Low; intellectual property focus, minimal physical site hazards. |
| Trucking/Logistics | 811 | High; transportation risks, cargo loading, road hazards. |
It is important to note that even within a single company, there may be "standard exceptions." Employees who work exclusively in clerical, drafting, or outside sales roles often qualify for specific "exception" codes (such as Code 953 for clerical), regardless of what the rest of the business does. This is a critical nuance that business owners often overlook, leading to unnecessary insurance costs.
Prerequisites for Proper Classification
Before applying for or renewing a policy, business owners must gather specific documentation to ensure they are assigned the correct codes. Proper classification is a prerequisite for financial stability in the state's regulatory environment.
- Detailed Job Descriptions: You must be able to prove what your employees do. If your insurer asks for a breakdown of payroll by task, having written job descriptions that match the PCRB manual definitions is essential.
- Payroll Segregation: To benefit from using multiple class codes, your payroll records must explicitly separate the time and wages of employees performing different tasks. If your accounting system lumps everyone together, insurers will often default to the highest-rated code for the entire payroll, which usually results in a higher premium.
- Site Inspection Reports: In some instances, the insurer or the PCRB may conduct a physical audit or inspection of your facility to confirm that the activities performed on-site align with your declared class codes.
Avoiding Common Mistakes in Classification
The most frequent mistake businesses make is "code inertia"—renewing a policy for years without reviewing if the operations have shifted. If your business has pivoted from manufacturing to distribution, your risk profile has changed, and your insurance costs should be adjusted accordingly.
Another common pitfall is the misclassification of subcontractors. In Pennsylvania, if you hire an independent contractor who does not carry their own workers' compensation insurance, you may be held responsible for their injuries under your own policy. In such cases, these individuals must be included in your payroll audits, and they must be assigned the class code appropriate for the work they perform. Failing to classify these payments correctly can lead to massive premium adjustments during the final audit period.
Handling Disagreements and Audits
If you believe your business has been assigned an incorrect class code, you have the right to request a formal classification review. The process typically involves submitting a formal request to the PCRB or your insurance carrier, backed by evidence such as duty logs, photographs of the work environment, and payroll records.
Audits are a standard part of the workers' compensation system in Pennsylvania. At the end of each policy term, an auditor will review your payroll records. They are looking for two things:
- Did you pay the correct amount of premium based on the actual payroll vs. the estimated payroll?
- Did you assign the correct class codes to each employee category?
If the auditor finds a discrepancy, they will issue a "premium audit adjustment." If you believe the auditor has misapplied the manual, do not simply accept the bill. Request a written explanation of the findings and compare them against the current Pennsylvania Workers' Compensation Insurance Manual.
Next Actions for Employers
If you are a business owner in Pennsylvania, your first step is to request a breakdown of your current payroll by class code from your insurance agent. Compare these to the duties your employees actually perform. If you find a mismatch—for example, if you are paying for an expensive "construction" rate for a staff member who spends 100% of their time performing bookkeeping in a separate office—contact your insurance agent immediately to request a reclassification.
Keep in mind that insurance rules and the Pennsylvania Workers' Compensation Insurance Manual are updated annually. Staying informed about these changes is not just about compliance; it is a vital part of managing your operational overhead. Always verify that your documentation is up to date before each annual audit to ensure that your premiums accurately reflect the current risk level of your workforce.
Note: This information is for educational purposes. Workers' compensation laws are subject to specific legislative changes and administrative rulings. Employers should consult with a licensed insurance broker or legal counsel to address specific coverage or classification concerns.
Frequently Asked Questions
1. Can I use multiple class codes for one employee? Generally, no. You cannot split a single employee's payroll between two different class codes unless they are performing distinct duties that are separately documented and the employee spends a significant, verifiable amount of time in each category. Usually, the entire payroll of an employee is assigned to the class code that represents their primary duty.
2. What is an Experience Modifier, and how does it affect my class code? The Experience Modifier (E-Mod) is a statistical tool that adjusts your premium based on your company's safety record. It does not change your class code, but it acts as a multiplier on top of the rate assigned to that code. If you have fewer or less expensive claims than the industry average, your E-Mod will be less than 1.0, effectively lowering the cost of your assigned class codes.
3. Are there codes for remote employees? Remote or work-from-home employees are typically classified under the clerical code (Code 953), provided their job duties are purely clerical. However, you must be able to substantiate their location and activities. If a remote employee performs manual labor or other specialized tasks, the clerical classification may not apply.
4. What happens if I get audited and disagree with the findings? You have the right to appeal audit findings. You should gather all supporting documentation, including payroll registers, job descriptions, and organization charts. Submit a written dispute to your insurance carrier first, and if the issue remains unresolved, you can reach out to the Pennsylvania Compensation Rating Bureau (PCRB) for a formal classification appeal.
5. Do the class codes change every year? The definitions and the rates associated with those codes can and often do change annually. The PCRB releases updated manual rates and rule changes that reflect the evolving safety data for different industries. It is best practice to review your assigned codes with your broker at least 60 days before your policy renewal date.

Image Gallery
Select an image to open it in a new tab.




Simon Caldwell
Enterprise Technology and Systems Editor
