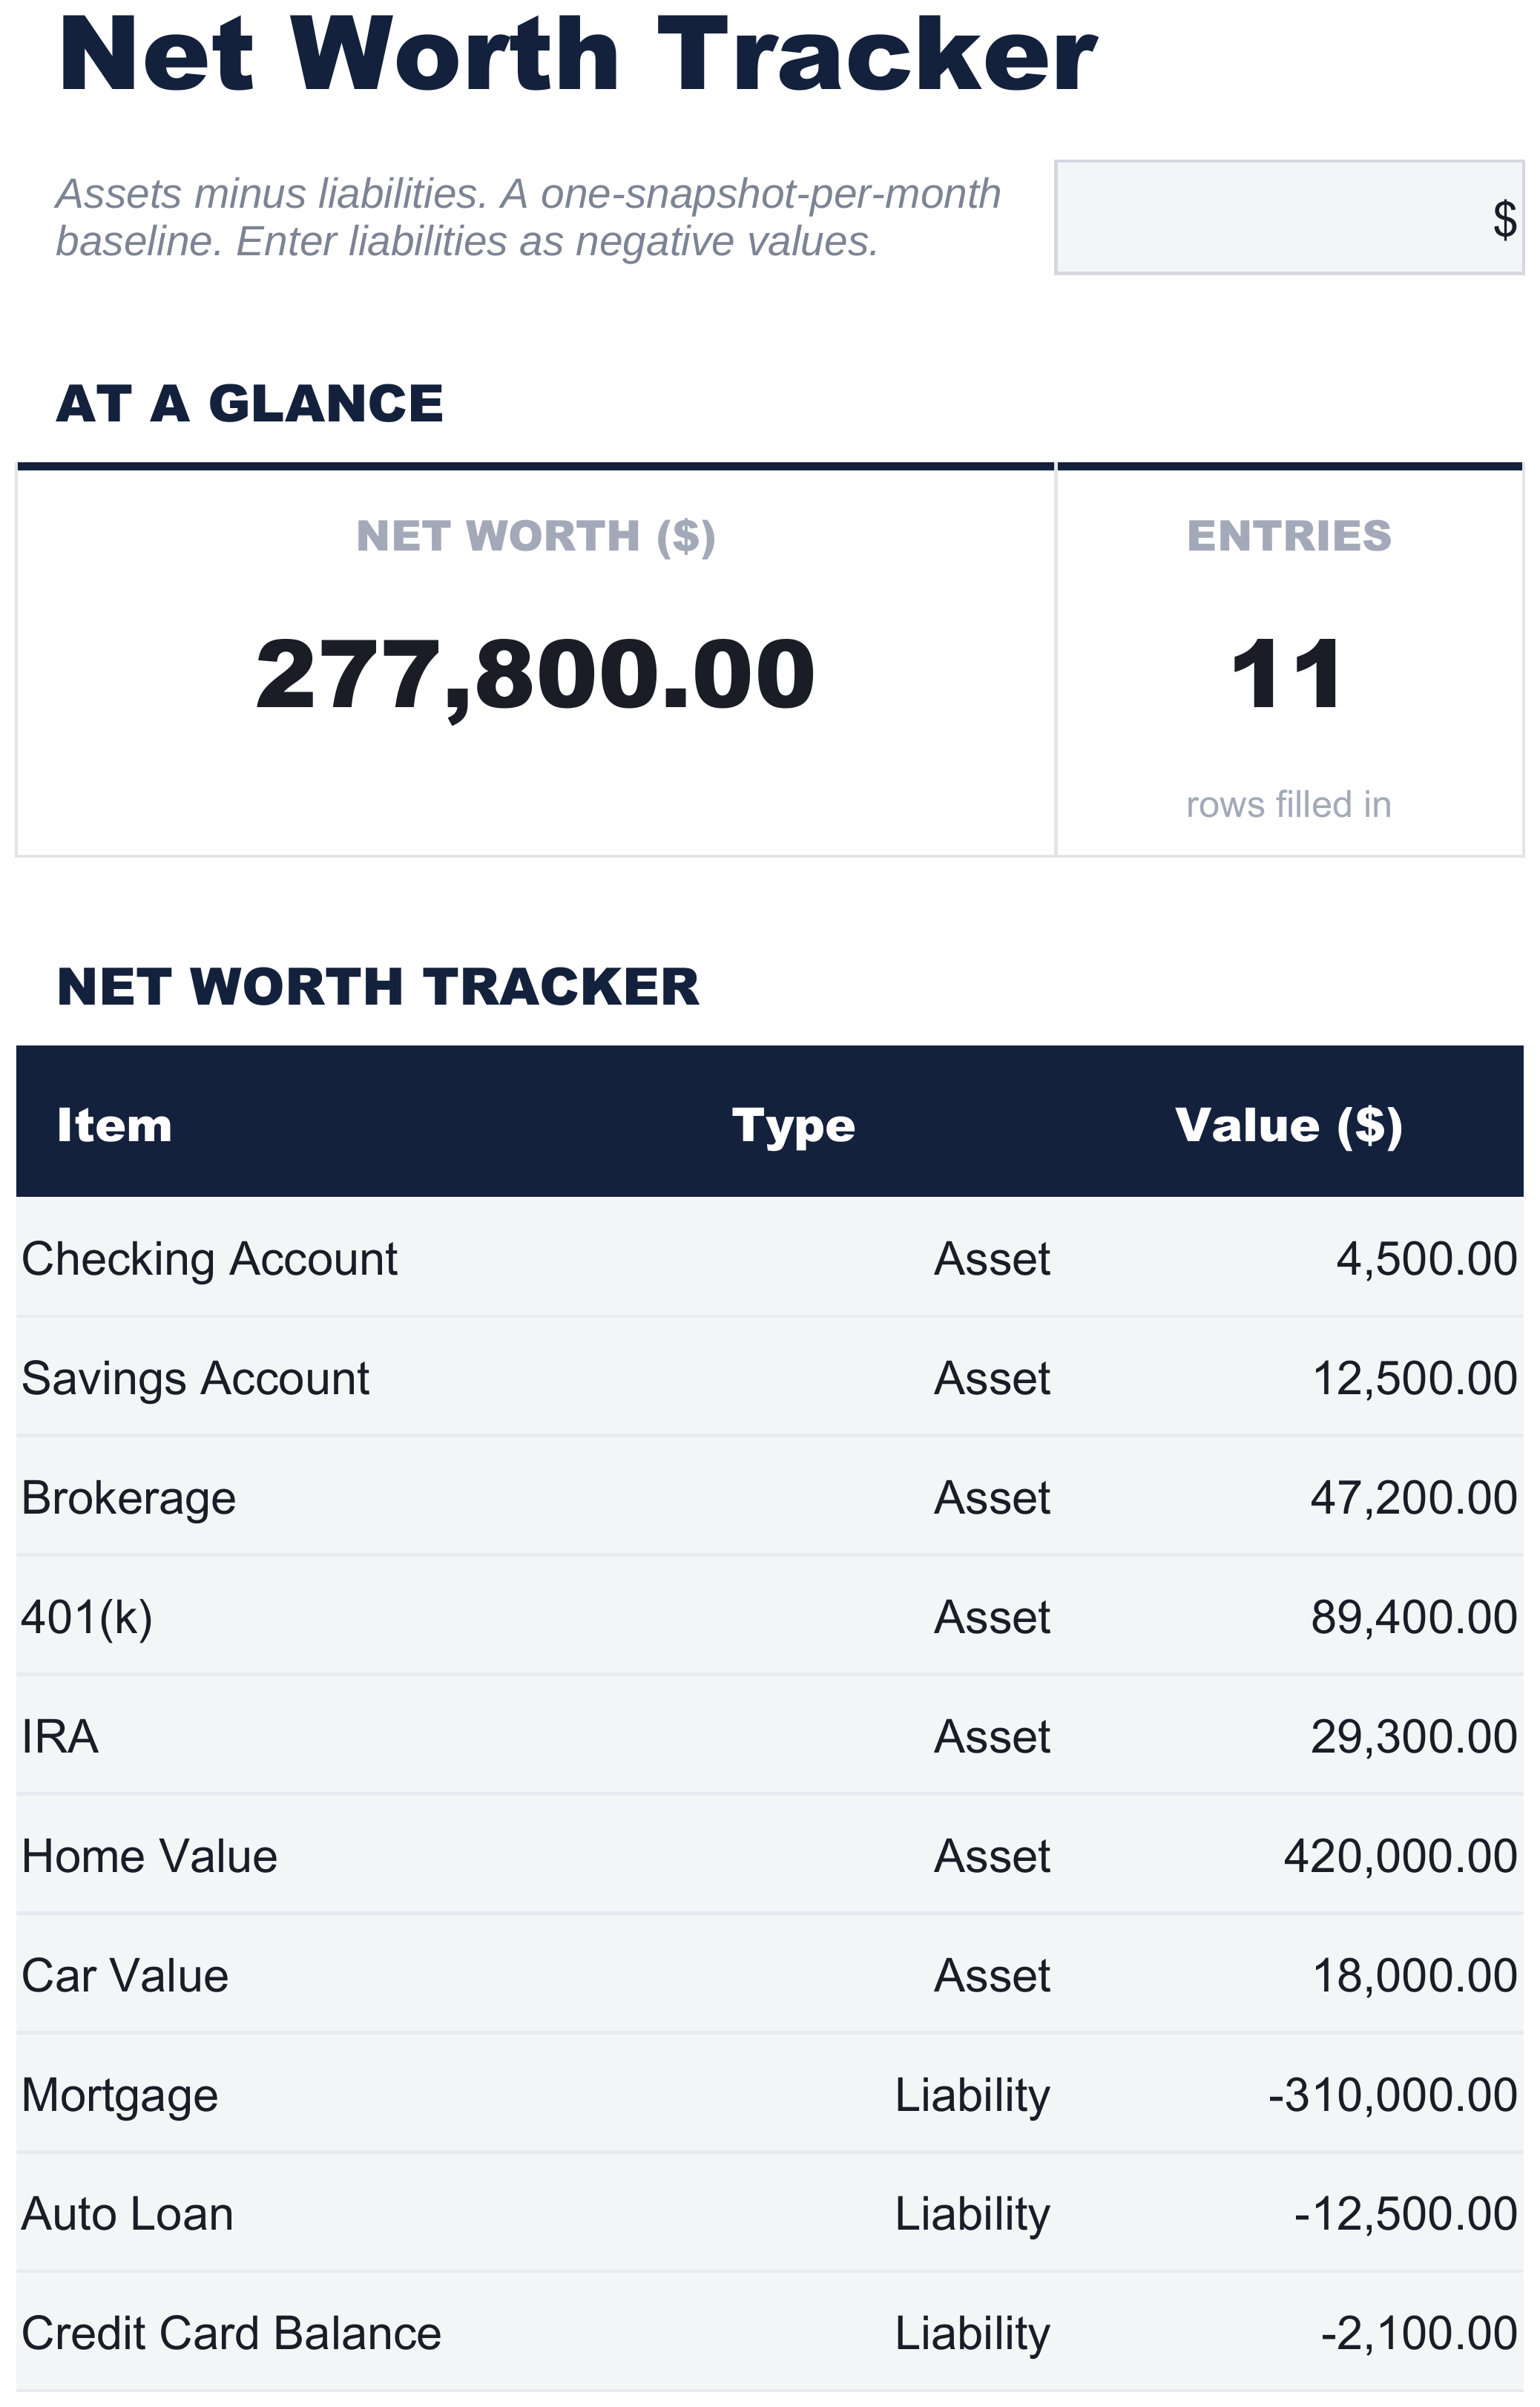
A decrease in net worth on a client's balance sheet occurs when the total value of their liabilities grows faster than their assets, or when the market value of their assets undergoes a significant decline. Mathematically, net worth is the residual value after subtracting all liabilities from total assets; therefore, any negative variance in this figure signals that the client's "equity" in their own financial life has eroded over the reporting period.
In the professional financial planning landscape of 2026, a declining net worth is not always a sign of financial failure, but it is always a signal that requires rigorous diagnostic analysis. Whether the cause is market volatility, aggressive spending, or strategic wealth transfer, understanding the "why" behind the numbers is essential for maintaining long-term solvency and meeting fiduciary obligations.
The Mathematical Mechanics of Net Worth Depreciation
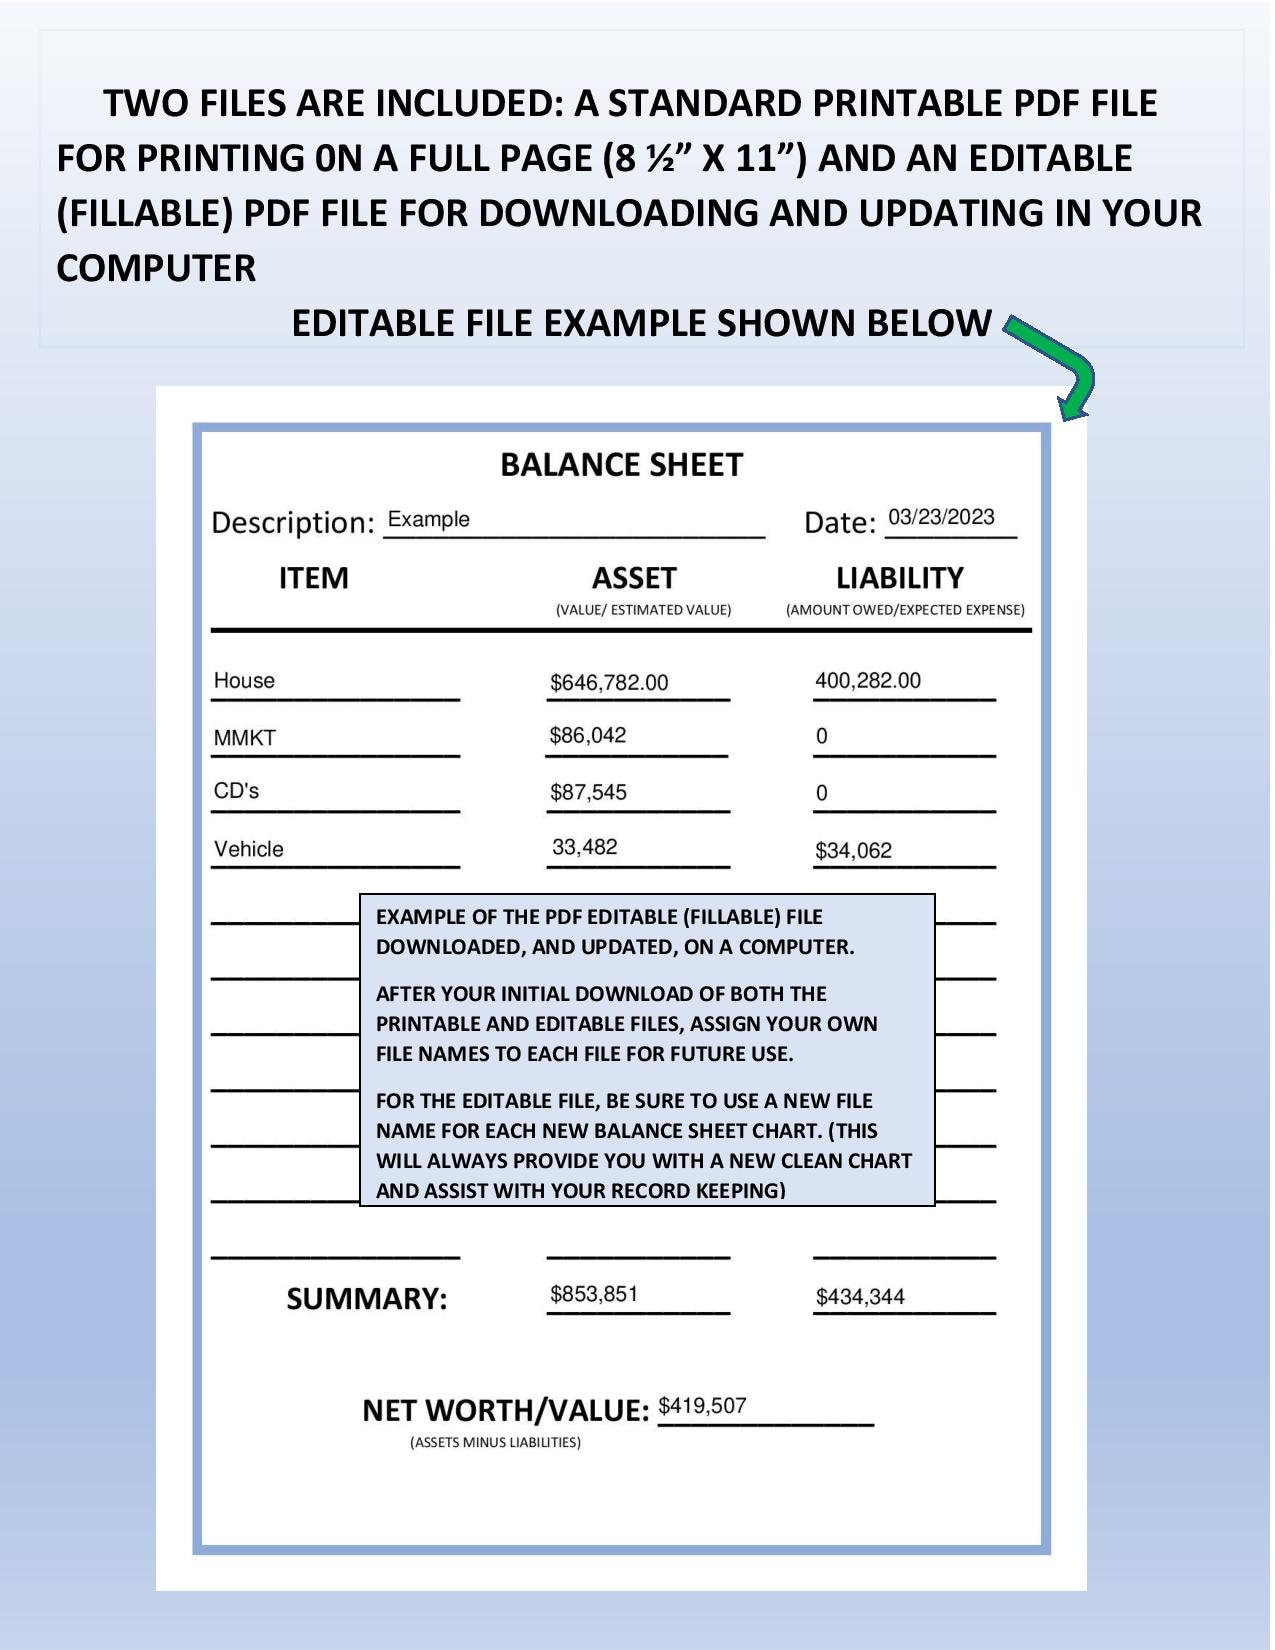
To understand why net worth decreases, one must first look at the fundamental balance sheet equation: Assets - Liabilities = Net Worth (Owner’s Equity). In a personal financial context, the balance sheet provides a snapshot in time. When comparing a current balance sheet to a previous one, a decrease in the bottom line can only be triggered by a specific set of movements within these two primary columns.
Asset Contraction
The most common cause of a decrease in net worth is a reduction in the "Asset" column. This can happen through the sale of assets to fund lifestyle expenses, where the cash is consumed rather than reinvested. It also occurs through the "unrealized" devaluation of holdings, such as a downturn in the stock market or a softening of the real estate market. In 2026, with diverse asset classes ranging from traditional equities to digital intangibles, tracking these fluctuations requires real-time data integration to ensure the balance sheet reflects fair market value (FMV) rather than historical cost.
Liability Expansion
Conversely, net worth decreases if a client’s liabilities increase while their assets remain stagnant or grow at a slower pace. This is often seen when a client takes on new debt—such as a mortgage, a business loan, or high-interest consumer credit—without a corresponding increase in a productive asset. For example, using a credit card to fund a vacation increases liabilities without adding a tangible asset to the balance sheet, resulting in an immediate and direct hit to net worth.
Primary Drivers of Net Worth Decline in 2026
Analyzing a decrease in net worth requires a deep dive into the specific economic and personal factors at play. In the current economic cycle, several distinct drivers frequently appear on client statements.
1. Market Volatility and Systematic Risk
For many high-net-worth individuals, the largest portion of their balance sheet is tied to brokerage accounts and retirement funds. When the broader markets experience a correction, the "paper value" of these assets drops. While these are often unrealized losses (meaning the client hasn't sold the assets and "locked in" the loss), the balance sheet must reflect the current market price. Financial advisors in 2026 utilize sophisticated risk-tolerance modeling to explain that while the net worth has decreased, the "share count" or "quantity" of the assets may remain unchanged, positioning the client for a recovery when market conditions improve.
2. Lifestyle Inflation and Cash Flow Deficits
A decrease in net worth is frequently a "cash flow" problem in disguise. If a client’s annual expenditures exceed their after-tax income, they must pull from their assets to bridge the gap. This "burn rate" is a primary culprit for steady, month-over-month declines in net worth. Over time, the liquidation of savings to support an unsustainable lifestyle erodes the principal of the investment portfolio, leading to a compounding negative effect on the balance sheet.
3. Planned Wealth Transfers and Gifting
It is vital to distinguish between a "bad" decrease and a "planned" decrease. Many clients in the later stages of their financial lifecycle intentionally decrease their net worth through strategic gifting to heirs or charitable organizations. These actions reduce the total asset column but serve a specific purpose in estate planning and tax mitigation. In these instances, the decrease in net worth is a metric of success in executing a legacy plan, rather than a sign of financial distress.
4. Depreciation of Tangible Assets
Physical assets such as vehicles, specialized machinery, or even high-end electronics are subject to depreciation. On a professional balance sheet, these should be adjusted periodically. If a client has a significant portion of their wealth tied up in "use assets" rather than "investment assets," their net worth will naturally trend downward as those items lose value over time.

Analyzing "Good" vs. "Bad" Decreases
Not all balance sheet contractions are created equal. A senior technical editor or financial analyst must be able to categorize the nature of the decline to provide actionable advice.
| Scenario | Impact on Net Worth | Strategic Context |
|---|---|---|
| Market Correction | Temporary Decrease | Often a "paper loss" that recovers with the market cycle; requires patience. |
| New Mortgage (Primary Residence) | Neutral to Slight Decrease | Assets increase (home) and Liabilities increase (loan), but closing costs may cause a small dip. |
| Consumer Debt Accumulation | Direct Decrease | Funding non-appreciating assets with debt is the most dangerous form of decline. |
| Business Investment (Seed Capital) | Decrease in Liquid Assets | High-risk move where cash is replaced by a "private equity" asset of uncertain value. |
| Tax Liabilities | Direct Decrease | Settling large tax bills or audit adjustments reduces cash without lowering other liabilities. |
The Role of Leverage
Leverage is a double-edged sword that can cause rapid shifts in net worth. If a client uses margin to trade or takes out a HELOC (Home Equity Line of Credit) to invest in a business, they are increasing their liabilities. If the underlying investment fails or underperforms the interest rate on the debt, the net worth will plummet. In the 2026 interest rate environment, the "cost of carry" for debt is a significant factor in whether a liability is helping or hurting the client's overall financial health.
Professional Diagnostic Steps for Financial Advisors
When a client presents a balance sheet showing a decrease in net worth, a systematic "audit" of their financial life is required. This process ensures that no underlying issues are missed and that the client receives a clear explanation of their status.
Step 1: Verify Asset Valuations
Ensure that the decrease isn't simply an accounting error or a stale valuation. Check the most recent statements for all accounts. For private business interests or real estate, determine if the "current value" used on the balance sheet is based on a recent appraisal or a conservative estimate.
Step 2: Review the Income Statement (Cash Flow)
A balance sheet is a snapshot; the income statement is the "movie" that shows how the client got there. Compare total inflows (salary, dividends, interest) against total outflows (mortgage, lifestyle, taxes). If the outflows are higher, you have found the primary driver of the net worth decline.
Step 3: Identify Debt Structure Changes
Examine the liability section for any new entries. Did the client co-sign a loan? Did a variable interest rate cause a balance to increase despite regular payments? Understanding the terms of the debt is crucial for determining how to stop the "leak" in net worth.
Step 4: Tax and Regulatory Impact
In 2026, changes in tax laws or capital gains treatments can impact net worth. If a client had to pay a significant amount in capital gains taxes due to a rebalancing of their portfolio, their net worth would decrease in the short term, even if the rebalancing was a sound long-term strategy. According to the Internal Revenue Service (IRS), capital losses can sometimes offset these hits, but the immediate impact on the balance sheet remains negative.
Strategies to Reverse a Declining Net Worth
Once the cause is identified, the focus must shift to remediation. The goal is to return the balance sheet to a state of growth, or at least stability.
Debt Restructuring and Acceleration
If the decrease is driven by high-interest liabilities, the most effective "win" is a debt paydown strategy. Every dollar used to pay down a liability is a dollar added back to the net worth. Advisors may recommend the "snowball" or "avalanche" method, or even debt consolidation if interest rates allow for a lower weighted average cost of debt.
Portfolio Rebalancing
If market volatility is the culprit, the client's asset allocation may be out of alignment with their risk tolerance. Shifting from high-volatility equities to more stable, income-producing assets (like bonds or high-yield money market accounts) can help preserve the remaining net worth and provide a floor for future declines.
Expense Management
For clients suffering from cash flow deficits, a "lifestyle audit" is mandatory. This involves categorizing expenses into "Essential" and "Discretionary." By cutting discretionary spending, the client can stop the liquidation of assets, allowing their remaining investments to begin compounding again.
Communicating the Decline to the Client
Discussing a decrease in net worth requires a balance of transparency and professional reassurance. It is one of the most difficult conversations for a wealth manager or accountant.
- Use Visual Aids: Charts showing the historical trend of net worth can help put a recent dip into perspective. If the net worth has grown 50% over five years, a 5% drop this year feels less catastrophic.
- Focus on the "Controllables": The client cannot control the stock market or the national interest rate, but they can control their spending and their debt levels. Focus the conversation on the actions they can take today.
- Benchmark Against Peer Groups: Sometimes, a client's net worth may be down 10%, but the broader market is down 20%. In this context, the client has actually outperformed the market through defensive positioning.
- Revisit the Financial Plan: Remind the client of their "Why." If the net worth decreased because they bought a vacation home they have wanted for a decade, the decrease is a planned trade-off for lifestyle enjoyment.
FAQ: Frequently Asked Questions
Can net worth decrease if I am still saving money every month?
Yes. Net worth can decrease even with consistent savings if your existing investments lose more value than the amount you are contributing. For example, if you save $1,000 a month but your $500,000 stock portfolio drops by 5% ($25,000), your net worth will still show a net decrease for that month.
Is a decrease in net worth always a sign of a bad financial situation?
Not necessarily. As discussed, planned wealth transfers, major life purchases (like a home or education), and market-driven "paper losses" can all cause a decrease. The key is whether the decrease is part of a long-term plan or an unintended result of poor financial management.
How often should a client's balance sheet be updated?
For most individuals, a quarterly update is sufficient to track trends without becoming overwhelmed by daily market fluctuations. However, for business owners or those with high-leverage portfolios, a monthly review may be necessary to catch negative trends early.
What is the difference between a "realized" and "unrealized" decrease in net worth?
An unrealized decrease occurs when an asset you still own drops in value (like a stock you haven't sold). A realized decrease occurs when you actually sell an asset for less than you paid for it or when you spend cash on a non-asset (like a bill or a dinner). Unrealized decreases can reverse if the asset value goes back up; realized decreases are permanent.
How do interest rates in 2026 affect my net worth?
Higher interest rates can decrease net worth in two ways: by increasing the cost of variable-rate debt (liabilities) and by potentially lowering the market value of existing bonds and real estate (assets). Conversely, if you hold significant cash in high-yield accounts, higher rates could help increase your net worth through interest income.
Final Recommendation
When facing a decrease in net worth on a client's balance sheet, the first action should always be a comprehensive categorization of the loss. Identify which portion of the decline is attributable to market forces, which to spending habits, and which to strategic debt. Once the diagnosis is clear, prioritize the elimination of high-interest consumer debt and the stabilization of cash flow. A declining net worth is a lagging indicator; by the time it shows up on the balance sheet, the underlying behavior or market event has already occurred. Therefore, proactive monitoring and a flexible financial plan are the best defenses against long-term wealth erosion.
Image Gallery
Select an image to open it in a new tab.




Lars Thomsen
Global Labor Markets and Economic Strategy Editor
