
Navigating the complexities of auto insurance claims requires a methodical approach, beginning with immediate documentation of the incident and clear communication with your insurer. By securing professional repair estimates, maintaining rigorous records of all correspondence, and understanding your specific policy coverage, you can effectively advocate for a fair repair assessment and timely claim resolution.
Understanding the Auto Repair Claims Process
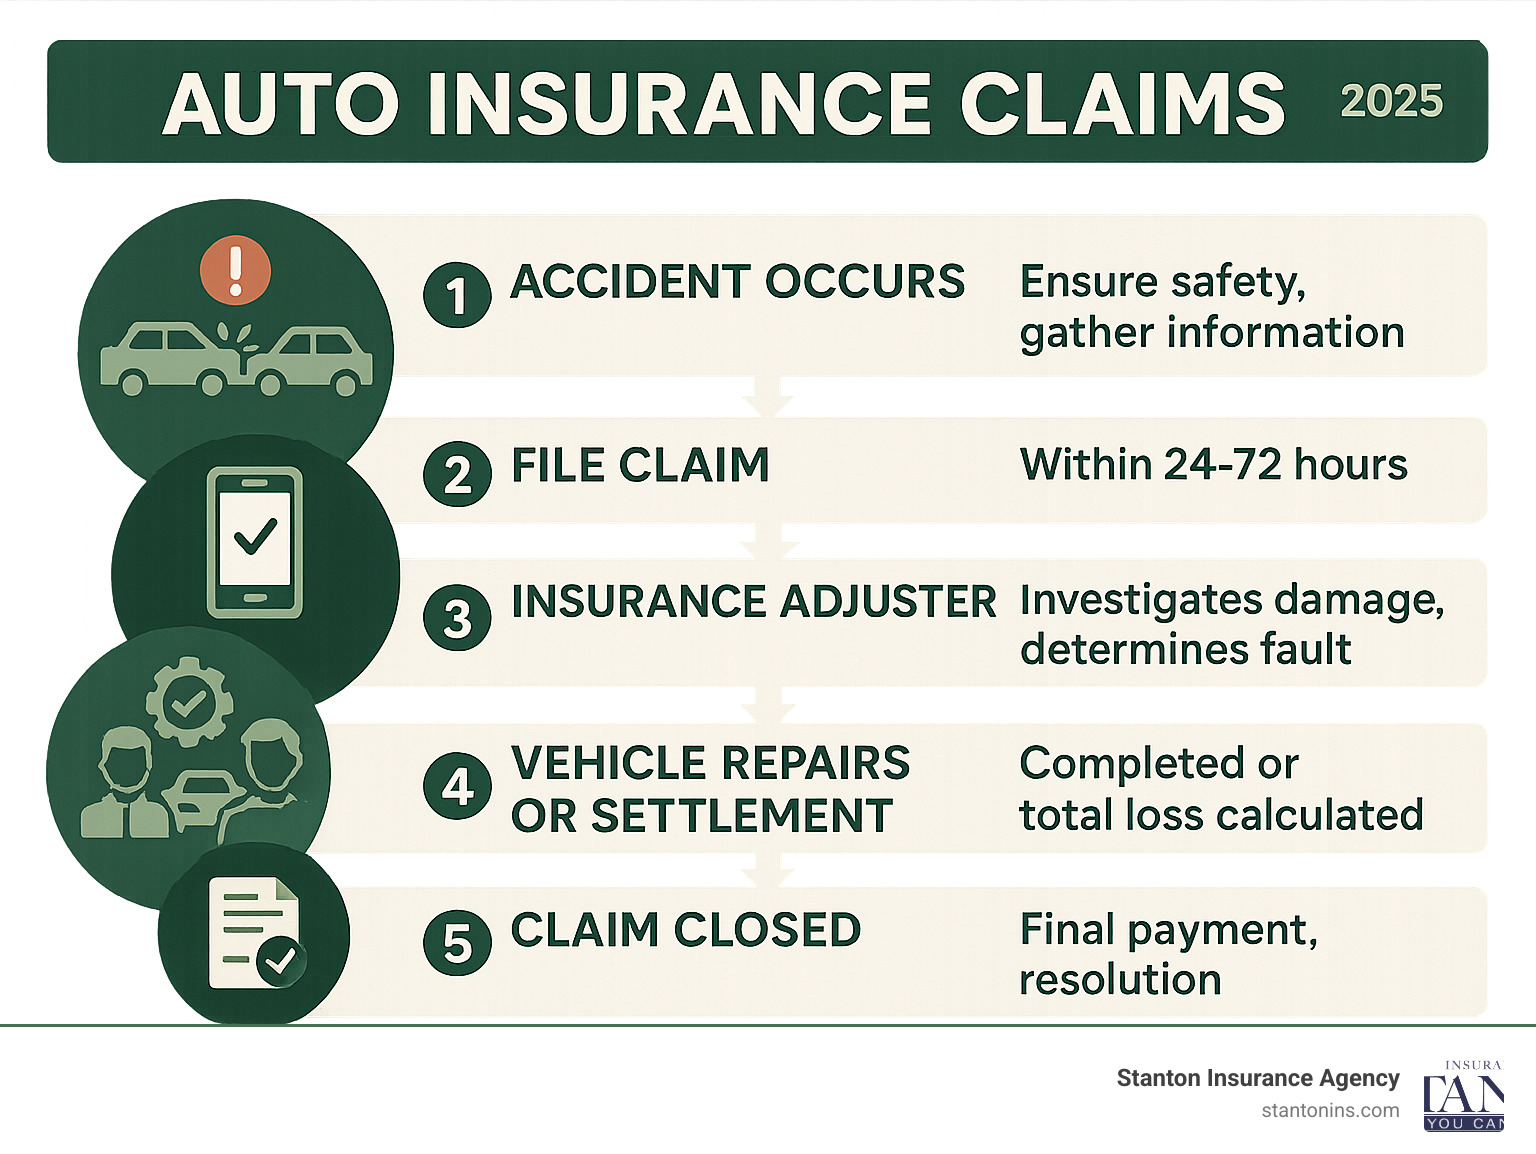
The auto repair insurance claims process is a structured sequence of events designed to restore a vehicle to its pre-loss condition or provide financial compensation for the value lost. When an accident occurs, the primary goal of the insurer is to verify that the damage is covered under your policy terms, assess the extent of the repairs, and negotiate the cost with repair facilities.
The process typically begins with the "First Notice of Loss" (FNOL), where you report the accident to your provider. From this moment forward, every interaction you have with the claims adjuster—the professional assigned to investigate your claim—becomes part of your official record. It is vital to recognize that the adjuster’s role is to minimize the insurer's liability while fulfilling the contractual obligations defined in your policy. Understanding this dynamic is the first step toward getting the help you need.
Immediate Actions Following an Accident
To ensure you have the best possible foundation for an insurance claim, your actions immediately following an accident are critical. The quality of your claim will be directly proportional to the quality of the evidence you gather.
- Safety and Documentation: Before moving vehicles, ensure everyone is safe. Once secure, photograph the damage to all involved vehicles from multiple angles, the surrounding environment, road conditions, and any traffic signs or signals.
- Police Reports: Even for minor accidents, filing a police report provides an objective, third-party account of the event. This document is often the most heavily weighted piece of evidence by insurance adjusters during the liability determination phase.
- Exchange of Information: Collect the other driver’s name, contact information, insurance policy number, and driver’s license details. If there are witnesses, secure their contact information as well.
- Avoid Immediate Admissions of Fault: When speaking to the other driver or law enforcement, stick strictly to the facts of the event. Do not speculate on who was at fault or apologize, as these statements can be used against you during the adjudication of the claim.
Engaging with Your Insurance Adjuster
Once the claim is filed, you will be assigned an adjuster. This individual acts as the primary point of contact for the duration of the repair process. Effective communication with the adjuster is not about being adversarial, but about being persistent and informed.
Maintain a "claims diary." Every time you speak to your adjuster, record the date, the time, the name of the person you spoke with, and a summary of what was discussed. If the adjuster makes a promise regarding a timeline or a specific coverage approval, send a brief follow-up email confirming the conversation. This documentation creates a paper trail that is difficult for an insurance company to ignore if a dispute arises later.
Obtaining Independent Repair Estimates
Insurance companies often prefer that you use a "preferred" or "network" repair shop. While these shops are vetted by the insurer, you are generally not legally obligated to use them. You have the right to choose your own repair facility.
If you are concerned that the insurance company’s initial damage assessment is too low, seek at least one—and preferably two—independent quotes from reputable, ASE-certified (National Institute for Automotive Service Excellence) repair shops. If the independent estimate is significantly higher than the adjuster's, present both documents to the insurance company. This creates a data-backed negotiation point that forces the insurer to justify their lower assessment.
Common Disputes and How to Resolve Them
Disputes in the auto repair claims process most frequently revolve around three issues: the cost of parts (OEM vs. aftermarket), the extent of the damage covered, and the estimation of labor hours.
- Parts Disputes: Insurers may insist on using aftermarket (non-OEM) parts to save costs. Check your policy to see if you have "Original Equipment Manufacturer" (OEM) parts coverage. If your policy is silent on this, you may have to negotiate or pay the difference yourself.
- Supplementals: Often, hidden damage is discovered only after the vehicle is partially disassembled. This is known as a "supplemental claim." Ensure your repair shop is prepared to communicate directly with the insurance company to justify these additional costs with photos and diagnostic data.
- Total Loss Determination: If the cost to repair the vehicle exceeds a certain percentage of its actual cash value (ACV), the insurance company will declare the car a "total loss." If you disagree with their valuation of your vehicle, you must conduct your own market research, finding comparable listings for your vehicle’s make, model, mileage, and condition in your local area to challenge their offer.
Summary of Claim Elements
| Claim Stage | Key Objective | Documentation Required |
|---|---|---|
| Initial Filing | Establish incident facts | Police report, photos, driver details |
| Adjustment | Confirm damage scope | Official repair estimates, injury records |
| Repair Phase | Address hidden damage | Supplemental estimates, shop logs |
| Negotiation | Ensure fair payout/repair | Independent quotes, ACV research |
Leveraging Your State Insurance Department
If you find yourself at an impasse with your insurer, and all internal appeals have been exhausted, you may file a complaint with your state’s Department of Insurance (DOI). Every state maintains a regulatory body designed to oversee insurance practices and protect consumers from bad-faith conduct.
Before contacting the DOI, ensure you have a complete file ready. This should include copies of your policy, the claim number, all correspondence with the adjuster, and the specific reasons you believe the insurance company is acting in violation of their policy terms. The DOI cannot act as a legal representative in court, but they can exert significant pressure on an insurance company to comply with state regulations and contractual obligations.
Frequently Asked Questions
Can I choose any repair shop I want? Yes. While insurance companies will recommend their network of preferred shops because they have pre-negotiated rates and warranties, you have the right to choose the shop that performs your repairs. If the repair shop’s rates are higher than the insurance company’s "market rate," you may be responsible for the difference.
What is an OEM part and why does it matter? An OEM (Original Equipment Manufacturer) part is produced by the car manufacturer. Aftermarket parts are produced by third parties. OEM parts are generally preferred for maintaining a vehicle's safety standards and long-term value, but insurers often prefer cheaper aftermarket alternatives.
What should I do if the insurance company denies my claim? Request a formal written explanation for the denial. Review your policy’s "Exclusions" section to see if the reason for the denial is contractually valid. If you believe the denial is incorrect, you may request an internal appeal or escalate the matter to your state’s insurance department.
How is the value of my car determined if it is a total loss? Insurers look at the "Actual Cash Value" (ACV), which is the market value of your car immediately before the accident. They typically use specialized software that aggregates data from local sales listings, adjusting for mileage, condition, and vehicle history. You can challenge this by presenting your own research on comparable vehicles for sale in your area.
Is it worth hiring a public adjuster? A public adjuster is a professional who represents your interests rather than the insurance company's. They typically charge a percentage of the final claim settlement. This can be beneficial for complex or high-value claims, but for standard auto repairs, the cost may not be justified unless the dispute is significant.
Next Steps for Claim Success
To move forward effectively, conduct an immediate audit of your existing communications. If your claim is currently stalled, gather all evidence, including your independent repair estimates and your claims diary, and prepare a concise, written request for an explanation from the claims manager. If the insurer remains unresponsive or continues to provide inadequate compensation, reference your policy’s specific clauses regarding the appraisal process or your right to file an inquiry with your state’s insurance regulator. Professional persistence, backed by objective documentation, remains your most powerful tool in securing the repair assistance to which you are entitled.

Image Gallery
Select an image to open it in a new tab.

Akira Tanaka
International Academic Trends Correspondent
