Average Salary of Life Insurance Agent in California: Comprehensive 2026 Compensation Guide

The average salary of a life insurance agent in California generally ranges between $65,000 and $115,000 per year, heavily dependent on production, commission structures, and whether the agent operates as an independent producer or a captive employee. Because the insurance industry relies primarily on performance-based compensation rather than a fixed hourly or salaried model, total earnings can vary significantly across different regions of the state and levels of experience.
Navigating the financial landscape of the California insurance market requires an understanding of how commission structures, state licensing prerequisites, and local economic factors shape producer earnings. For individuals evaluating a career in the financial services sector or those looking to benchmark compensation against current industry standards, a granular look at base pay, commissions, bonuses, and operational overhead provides a realistic picture of what a life insurance agent can expect to earn.
Understanding the California Insurance Compensation Model
Insurance compensation diverges sharply from traditional corporate structures. While some entry-level agency positions or corporate carrier roles offer a modest base salary, the vast majority of life insurance agents in California operate on a 100% commission basis or a draw-against-commission system.
When evaluating the average salary of a life insurance agent in California, labor statistics and industry reports often capture base wages or reported W-2 earnings, which can misrepresent total take-home pay. Many successful agents supplement their income through renewal commissions—recurring payments generated each year a policy remains active—as well as overrides from building a team of agents in a hierarchical agency structure.
Furthermore, California's vast and economically diverse landscape creates regional disparities. Agents practicing in high-net-worth metropolitan areas such as San Francisco, Los Angeles, or San Diego frequently secure larger average face amounts per policy, translating into higher upfront commissions compared to agents in rural agricultural counties.
Captive Agents vs. Independent Producers
The choice of business model dictates how much a life insurance agent earns, how expenses are covered, and what products can be offered to consumers. California features a robust mix of both agency structures.
Captive Agents
A captive agent works exclusively for a single insurance carrier, such as New York Life, Northwestern Mutual, or State Farm.
- Compensation Structure: Typically lower initial commission rates, but often include a temporary base salary during the first one to three years to help new agents establish a book of business.
- Benefits: Access to corporate health insurance, 401(k) matching programs, and paid training.
- Support: The carrier often provides office space, centralized marketing leads, and administrative support staff.
Independent Producers
An independent agent or broker contracts with a Field Marketing Organization (FMO) or Directly with multiple insurance carriers, allowing them to shop the market for clients.
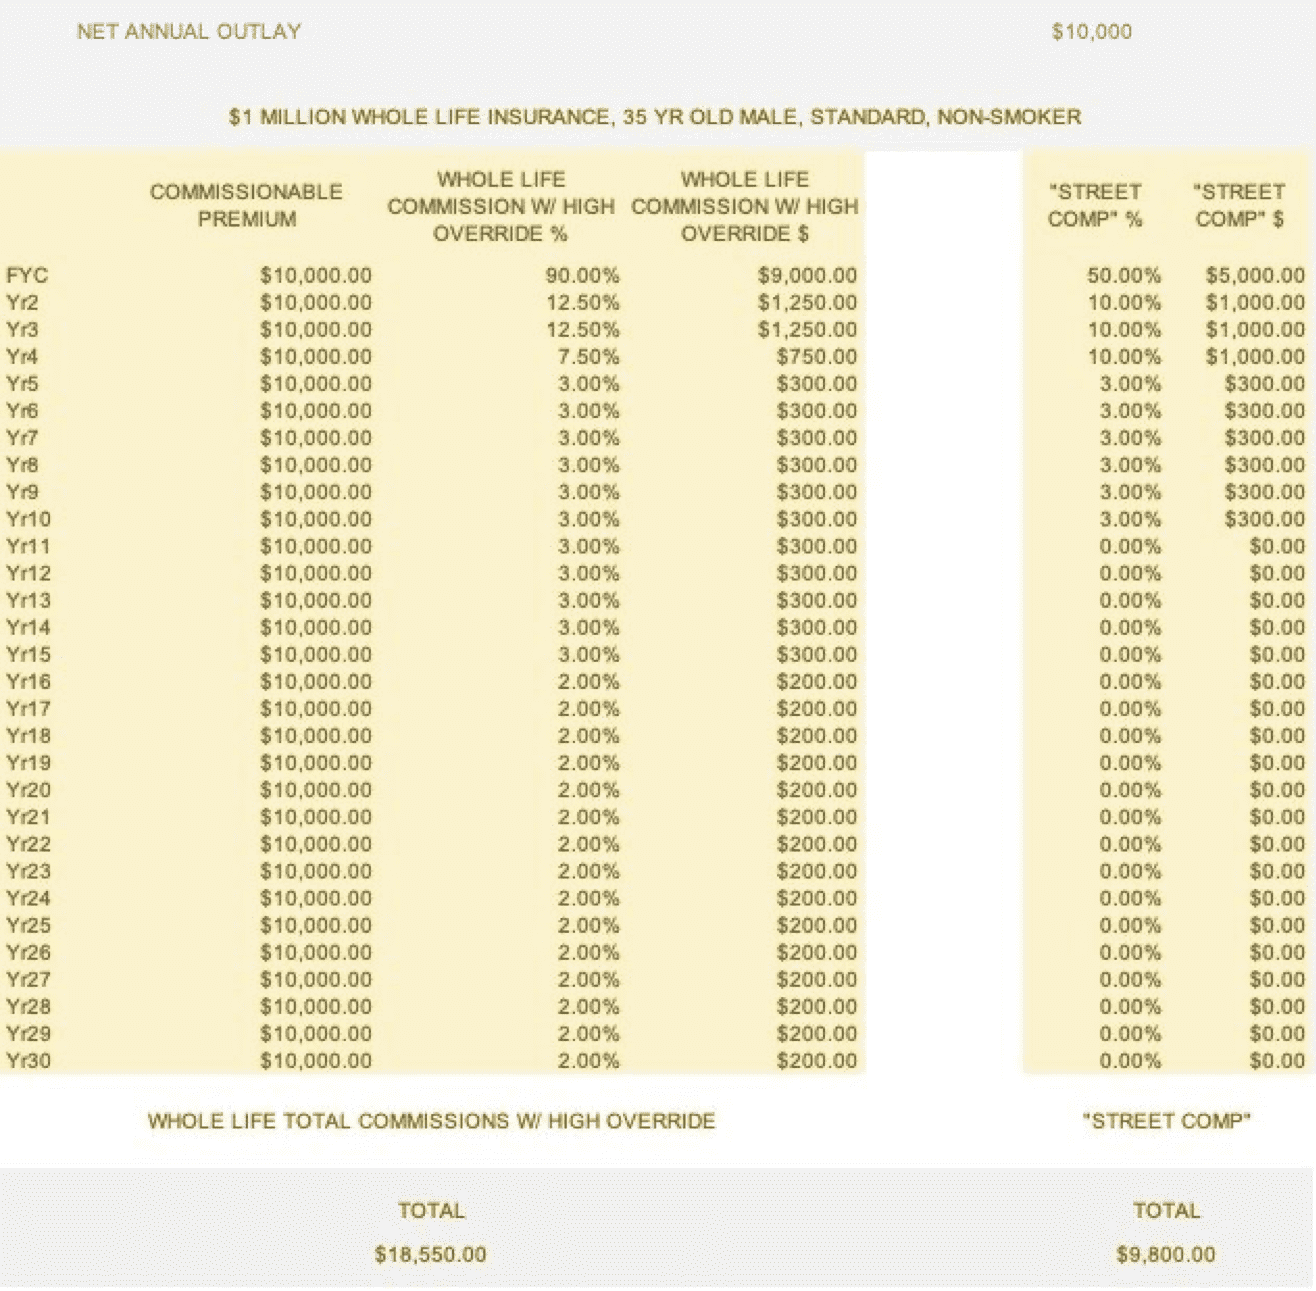
- Compensation Structure: Significantly higher commission percentages (often starting between 70% and 100% of the first year's premium), with no base salary safety net.
- Benefits: Complete self-employment status, requiring agents to purchase private health insurance and manage their own retirement savings.
- Support: Complete operational autonomy, meaning the agent bears 100% of marketing, licensing, errors and omissions (E&O) insurance, and office overhead costs.
Breakdown of Earnings by Experience and Tier
Income progression in the life insurance sector typically follows a non-linear trajectory. First-year agents often face a steep learning curve and lower earnings while building their prospecting funnel, whereas tenured agents benefit from a compounding book of renewal business.
| Career Stage | Estimated Annual Compensation Range | Primary Revenue Sources |
|---|---|---|
| Entry-Level (Year 1–2) | $40,000 – $65,000 | Small base salaries (if captive), initial term life sales, warm market prospecting. |
| Mid-Level (Year 3–5) | $75,000 – $130,000 | Growing renewal stream, whole life and universal life sales, referrals, independent contracts. |
| Senior/Established (Year 5+) | $150,000 – $300,000+ | High-volume production, complex estate planning products, agency overrides, substantial renewals. |
Note: Exceptional producers specializing in high-net-worth wealth transfer, key-person insurance, or corporate executive benefits can exceed $500,000 annually, though this represents the top tier of the profession.
Licensing Prerequisites and Regulatory Costs in California
Before earning any income, a prospective agent must legally qualify to sell insurance products within the state. The California Department of Insurance (CDI) regulates licensing and enforces strict compliance standards.
- Pre-Licensing Education: Candidates must complete a state-approved 20-hour pre-licensing course covering life-only or life-and-disability insurance, plus a mandatory 12-hour course on California Insurance Code ethics and "Code and Ethics."
- Background Check and Fingerprinting: Submission of fingerprints via Live Scan for a Department of Justice (DOJ) and FBI criminal history review. Disqualifying offenses generally include recent felony convictions involving financial fraud or dishonesty.
- State Licensing Examination: Passing the California Life-Only Agent examination administered by PSI Services. The exam tests knowledge of policy types, legal provisions, underwriting principles, and state regulations.
- License Application: Submitting the application and fees through the CDI online portal. Initial licensing fees include fingerprinting fees, background checks, and the two-year license fee.
Operational Overhead and Net Income Considerations
Gross commission figures can be deceiving. Because many California life insurance agents operate as independent contractors (1099 status), gross earnings do not reflect net take-home pay. Agents must budget for several mandatory business expenses:
- Errors and Omissions (E&O) Insurance: Professional liability coverage is essential and typically costs between $500 and $1,500 annually.
- Lead Generation and Marketing: Purchasing qualified leads, maintaining a digital presence, hosting seminars, or paying for direct mail campaigns can consume 10% to 30% of an independent agent's gross revenue.
- Continuing Education (CE): California requires life agents to complete 24 hours of CE every two-year licensing term, including specific ethics requirements, incurring course and renewal fees.
- Self-Employment Taxes: Independent contractors must pay the self-employment tax rate, covering both the employer and employee portions of Social Security and Medicare taxes, alongside federal and state income taxes.
Frequently Asked Questions
Do life insurance agents in California get a base salary?
Most independent agents receive no base salary and operate entirely on commission. However, new captive agents working directly for major mutual life insurance companies may receive a temporary base salary or guaranteed training allowance for their first 12 to 36 months to help them transition into commission-based production.
How are life insurance commissions calculated?
Commissions are typically calculated as a percentage of the annualized first-year premium (FYP). For example, if a client purchases a policy with an annual premium of $2,000 and the agent's commission rate is 80%, the agent earns $1,600 for the initial sale. Subsequent years often pay a smaller renewal commission (e.g., 2% to 5%) for as long as the client continues paying premiums.
What is the highest-paying type of life insurance to sell?
Permanent life insurance products—such as whole life, universal life, and indexed universal life (IUL)—generally generate higher initial commissions than term life insurance because their annual premiums are substantially larger and require more complex financial structuring.
How long does it take to become a licensed life insurance agent in California?
The timeline varies by individual study pace, but most candidates complete the required 32 hours of pre-licensing education, pass the state exam, and clear the background check within four to eight weeks.
Is prior sales experience required to succeed as an insurance agent in California?
Prior sales experience is not legally required by the California Department of Insurance. Success depends heavily on networking discipline, resilience, financial literacy, and communication skills rather than formal background prerequisites.
Next Actions and Strategic Recommendations
For individuals considering a career in this field, the most practical first step is to research local general agencies and insurance brokerages across California to compare captive versus independent training programs. Prospective agents should carefully review contract splits, proprietary product availability, and lead support systems before committing to a firm. Working professionals transitioning into the industry should maintain an emergency financial reserve covering at least three to six months of living expenses, given the ramp-up period required to build a sustainable commission pipeline.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
