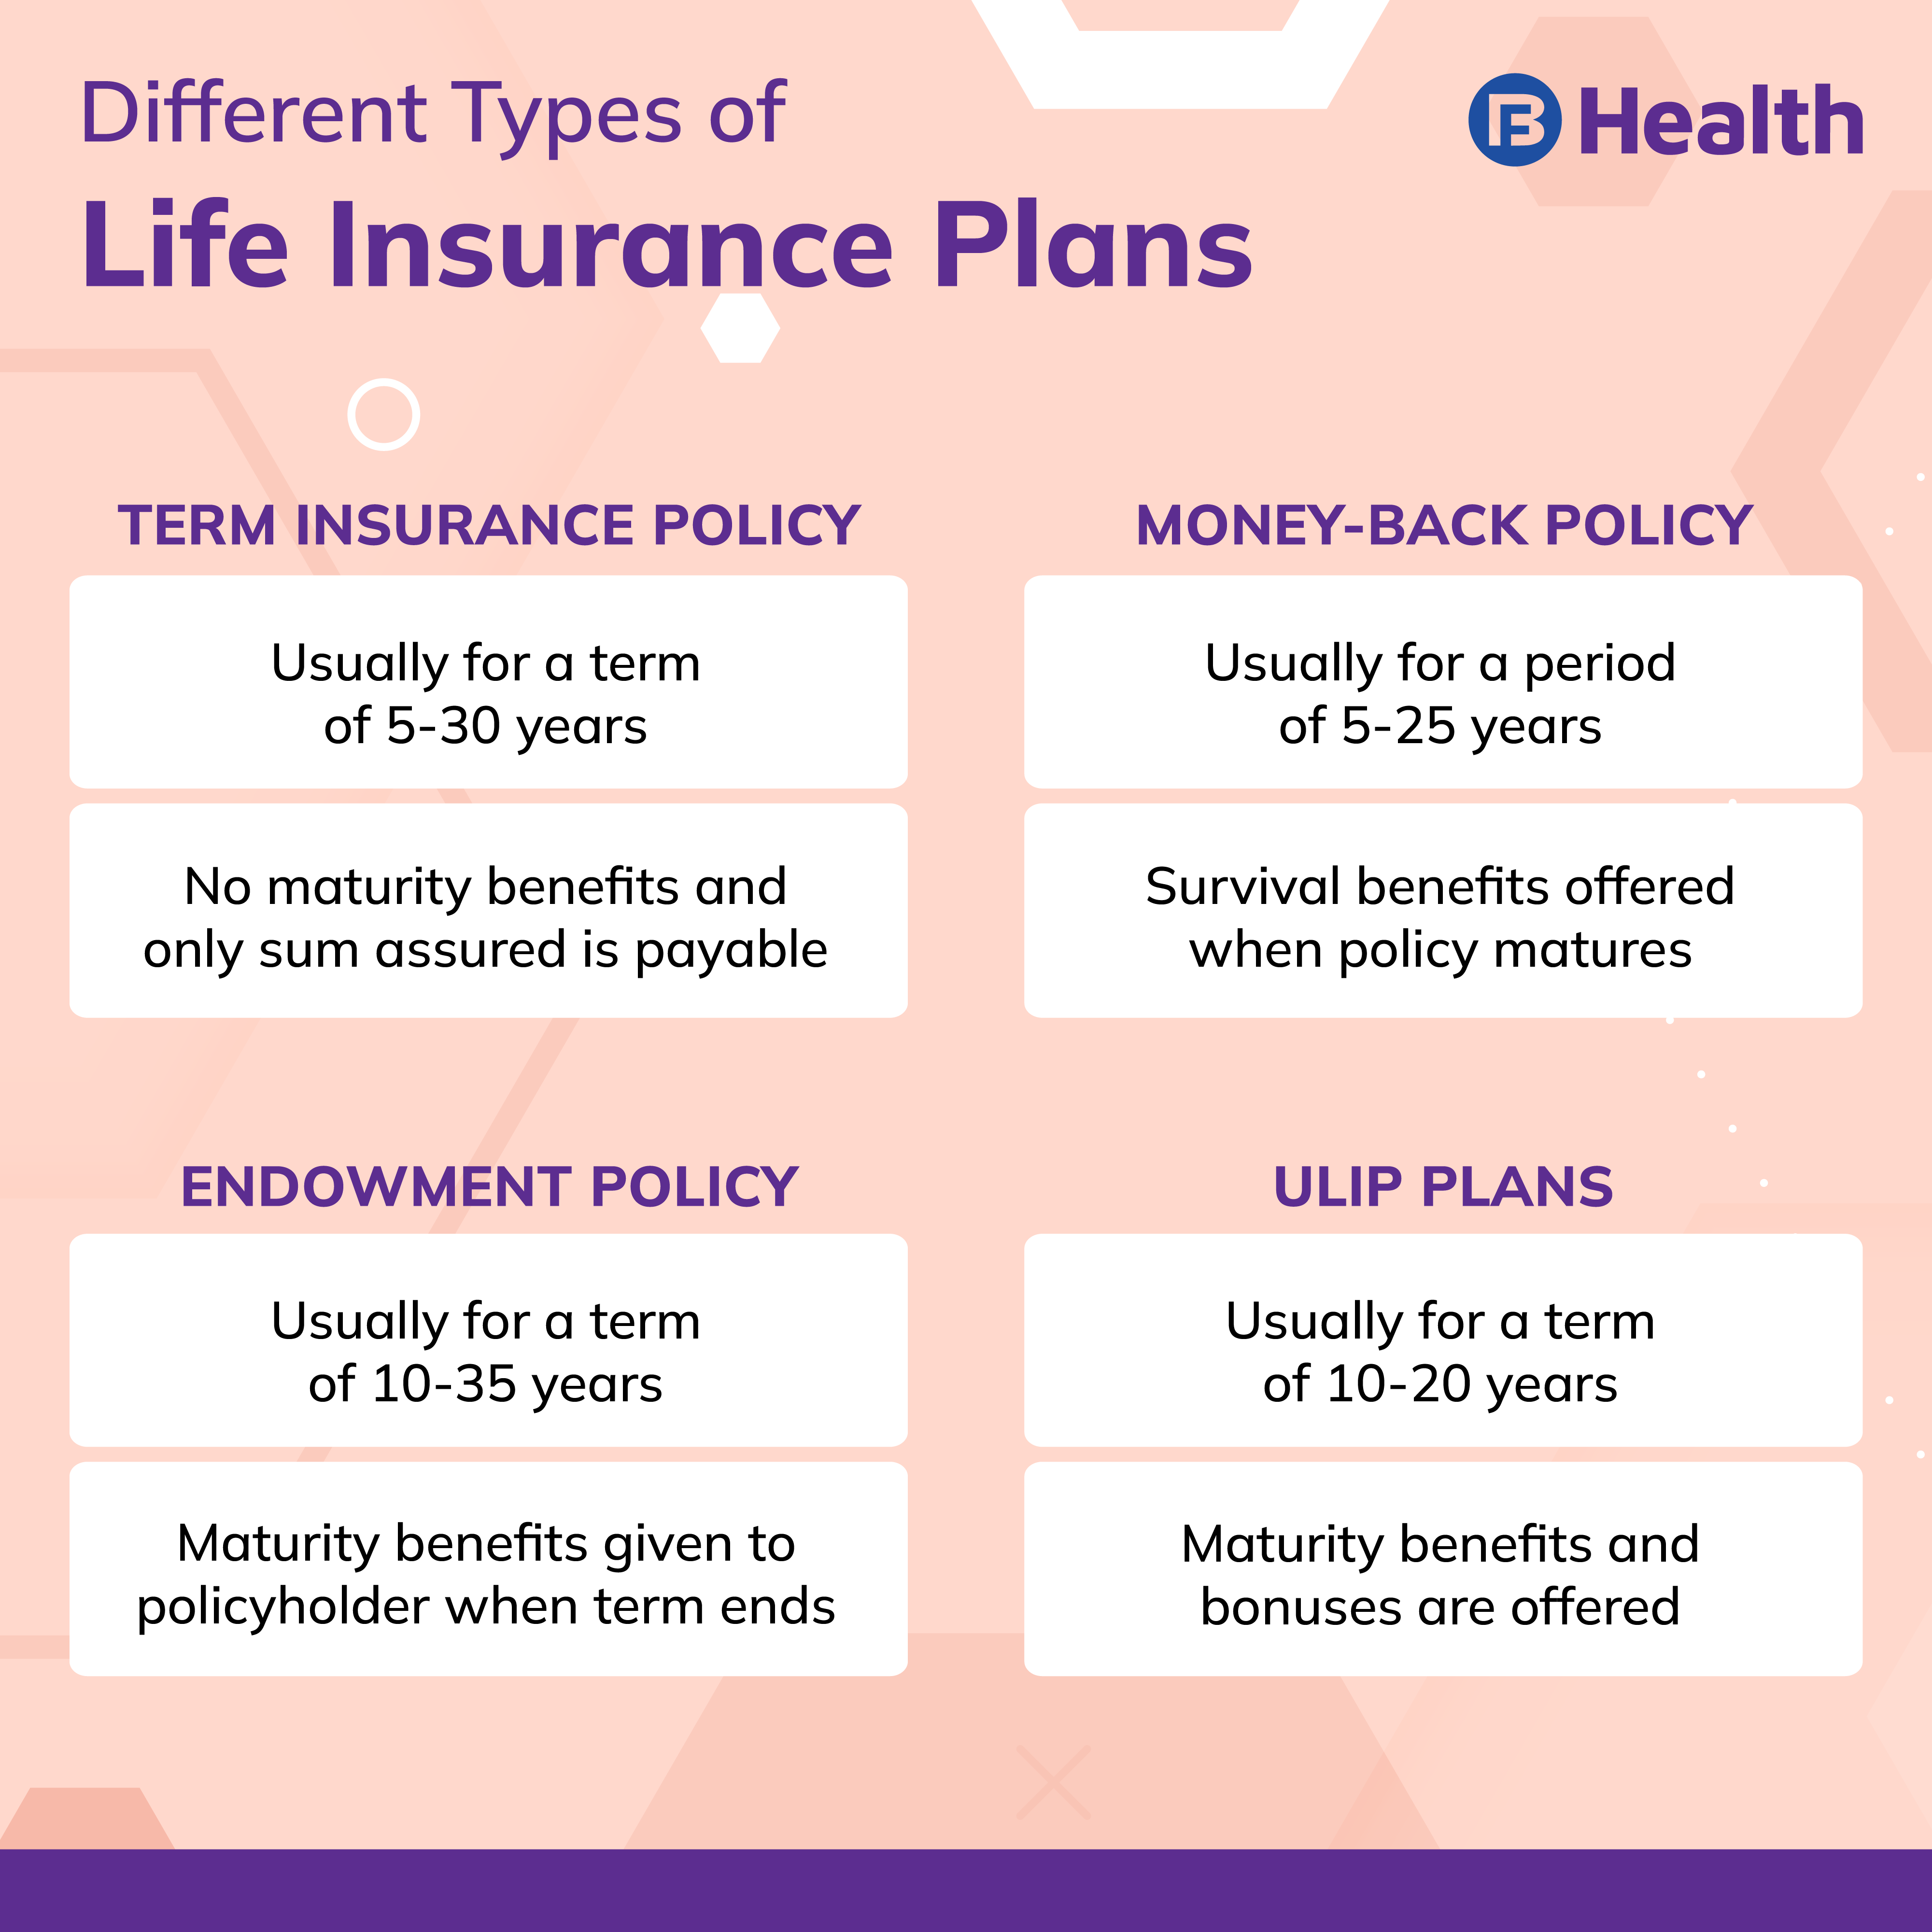
A participating (par) life insurance policy is a type of permanent life insurance—most commonly whole life—that allows the policyholder to share in the insurance company's surplus earnings through annual dividends. Unlike non-participating policies, "par" plans provide both a guaranteed death benefit and the potential for long-term wealth accumulation through these non-guaranteed but historically consistent dividend payments.
Understanding the Mechanics of Participating Life Insurance
To understand a participating life insurance policy, one must first understand the structure of the insurance companies that issue them. In 2026, the landscape of the insurance industry remains divided between stock companies and mutual companies. While stock companies are owned by shareholders, mutual companies are owned by their policyholders. When you purchase a participating policy from a mutual company, you are essentially becoming a partial "owner" with a right to participate in the financial success of the enterprise.
The "participation" aspect refers specifically to the distribution of dividends. These dividends are generated when the insurance company performs better than it initially projected in three specific areas:
- Mortality Gains: If fewer policyholders pass away than the actuarial tables predicted, the company keeps more of its death benefit reserves.
- Investment Returns: If the company’s general account—where premiums are invested—earns a higher return than the guaranteed minimum, the surplus is shared.
- Expense Management: If the company operates more efficiently and incurs lower administrative costs than budgeted, those savings contribute to the dividend pool.
While dividends are not legally guaranteed, many of the top-rated mutual insurers have paid them every single year for over 150 years, including through the Great Depression, both World Wars, and the economic fluctuations of the early 2020s.
The Core Components of a Par Policy
A participating life insurance policy is built on a foundation of "guarantees" and "non-guarantees." Navigating these components is essential for anyone using life insurance as a financial planning tool in 2026.
1. Guaranteed Death Benefit
The primary purpose of the policy is the death benefit. As long as premiums are paid, the face amount of the policy is guaranteed to be paid to beneficiaries tax-free. In a par policy, this death benefit often grows over time if dividends are used to purchase additional coverage.
2. Guaranteed Cash Value
A portion of every premium dollar is allocated to a cash value account. This account grows according to a schedule set at the time of policy issuance. By 2026 standards, these guarantees typically range between 2% and 3.5%, providing a "floor" that ensures the policy will never lose value, regardless of stock market volatility.
3. Level Premiums
Most participating whole life policies feature level premiums. This means the cost of the insurance is locked in at the age of purchase and will never increase. While this makes the policy more expensive than term insurance in the early years, it becomes significantly more cost-effective as the policyholder ages.
4. Policy Dividends (Non-Guaranteed)
Dividends are the engine that drives a par policy’s superior performance over non-par alternatives. Once declared, dividends are usually credited to the policy annually. Policyholders have several options for how to receive these funds, which we will explore in the next section.

Strategic Uses for Policy Dividends
The flexibility of a participating policy lies in the "Dividend Options." How a policyholder chooses to use their dividends in 2026 can fundamentally change the policy's purpose from simple protection to a robust retirement or estate planning vehicle.
- Paid-Up Additions (PUAs): This is arguably the most powerful option for long-term growth. Dividends are used to "buy" small, single-premium increments of additional whole life insurance. These additions have their own cash value and their own death benefit, and they also earn their own dividends. This creates a compounding effect where the policy grows exponentially over time.
- Accumulate at Interest: The dividends are left in a side account with the insurer to earn interest. While safe, the interest earned is generally taxable as ordinary income, making this less tax-efficient than other options.
- Reduce Premiums: The dividend is applied toward the annual premium, reducing the out-of-pocket cost for the policyholder. This is a popular option for retirees who want to maintain coverage but have a fixed income.
- Cash Payment: The insurer sends the policyholder a check. In many jurisdictions, including the United States, these dividends are considered a "return of premium" and are not taxable until the total dividends received exceed the total premiums paid into the policy.
- Repay Policy Loans: If the policyholder has borrowed against the cash value, dividends can be automatically directed to pay down the principal or interest of that loan.
Comparing Participating and Non-Participating Policies
When shopping for permanent coverage in 2026, the choice between participating and non-participating (non-par) policies is a matter of weighing current costs against future growth.
| Feature | Participating (Par) Policy | Non-Participating (Non-Par) Policy |
|---|---|---|
| Dividend Eligibility | Yes; eligible for annual surplus sharing. | No; no dividends are ever paid. |
| Premium Cost | Higher; includes a "safety margin" for the insurer. | Lower; priced exactly to the risk and expenses. |
| Cash Value Growth | Potentially high due to compounding dividends. | Fixed; limited to the original guarantee. |
| Death Benefit | Can increase over time via Paid-Up Additions. | Generally remains level (fixed). |
| Ownership Structure | Often issued by Mutual Companies. | Often issued by Stock Companies. |
| Best For | Wealth accumulation and inflation protection. | Pure permanent protection at the lowest cost. |
The Role of Cash Value and Policy Loans
A defining characteristic of the participating life insurance policy is the accessibility of its cash value. By 2026, many financial advisors treat the cash value of a par policy as a "Tier 1" asset—meaning it is highly liquid, safe, and uncorrelated with the equity markets.
Policyholders can access this cash through policy loans. When you take a loan from a par policy, you aren't actually withdrawing your money. Instead, the insurance company lends you money from its general fund, using your cash value as collateral.
This leads to a concept known as Direct vs. Non-Direct Recognition:
- Direct Recognition: The insurer reduces the dividend rate on the portion of the cash value used as collateral for a loan.
- Non-Direct Recognition: The insurer continues to pay the full dividend rate on the entire cash value, even the portion being used as collateral. In 2026, non-direct recognition remains a highly sought-after feature for those practicing "Infinite Banking" or "Privatized Banking" strategies.
Tax Advantages of Par Life Insurance
Participating life insurance enjoys a privileged tax status that remains a cornerstone of estate planning in 2026. These advantages are generally categorized into three "tax-free" buckets:
- Tax-Deferred Growth: The internal build-up of cash value is not taxed as it grows. This allows the compounding effect of dividends and interest to work much more efficiently than in a taxable brokerage account.
- Tax-Free Access: Through a combination of partial withdrawals (up to the "basis" or total premiums paid) and policy loans, policyholders can often access their cash value without triggering an income tax event.
- Tax-Free Death Benefit: Upon the death of the insured, the proceeds are paid to beneficiaries income-tax-free. If the policy is owned by an Irrevocable Life Insurance Trust (ILIT), the proceeds may also be exempt from federal estate taxes.
Note: Tax laws vary by jurisdiction. You should consult with a qualified tax professional regarding the specific regulations in your region as of 2026.
Is a Participating Policy Right for You?
Participating life insurance is not a "one-size-fits-all" solution. It requires a long-term commitment and a specific financial profile.
Who Should Consider It:
- High Net-Worth Individuals: Those looking for a tax-advantaged vehicle to move assets out of their taxable estate.
- Conservative Investors: Individuals who want a portion of their portfolio in a "safe bucket" that outperforms traditional savings accounts or CDs.
- Parents and Grandparents: Those looking to start a "Head Start" policy for children, where the long timeframe allows the compounding dividends to create a massive legacy.
- Business Owners: Par policies can be used for "Key Person" insurance or to fund buy-sell agreements, with the cash value serving as an emergency business reserve.
Who Should Avoid It:
- Those with Short-Term Needs: If you only need coverage for 10 or 20 years (e.g., until a mortgage is paid off), term insurance is significantly cheaper and more appropriate.
- Those with Tight Cash Flow: Par policies require substantial premiums. If there is a risk you cannot sustain the payments for the first 7–10 years, you risk "lapsing" the policy and losing the capital you invested.
Evaluating Dividend Scales in 2026
When reviewing a par policy illustration in 2026, it is vital to distinguish between the Dividend Scale Interest Rate (DSIR) and the Internal Rate of Return (IRR).
The DSIR is the gross rate the company uses to determine the dividend pool. It is not the net return a policyholder sees. The IRR accounts for the cost of insurance, administrative fees, and commissions. In the current 2026 market, a healthy par policy might show a DSIR of 5% to 6%, while the actual net IRR on the cash value over 20 years may hover between 3.5% and 4.5%. Always ask for an "Internal Rate of Return" report to see the true performance of the policy after all expenses.
Common Pitfalls and Misunderstandings
- Treating it as a Short-Term Investment: The high "front-end" costs of a par policy mean that the cash value in the first 2-3 years is often near zero. This is a 20-to-50-year financial instrument.
- Over-funding without PUA Riders: To maximize the "participating" aspect, savvy buyers use a "Paid-Up Additions Rider." This allows them to put more money into the policy than the base premium requires, accelerating cash value growth. Without this rider, the growth is much slower.
- Ignoring the "Modified Endowment Contract" (MEC) Limit: If you put too much money into a policy too quickly, the IRS (or relevant tax authority) may reclassify it as a MEC. This strips the policy of its tax-free loan benefits. Professional agents in 2026 use software to ensure policies stay just under this limit.
Frequently Asked Questions
Can the insurance company stop paying dividends?
Yes. Dividends are never guaranteed. However, many major mutual insurance companies have a track record of paying dividends every year for over a century. If a company stops paying dividends, the policy still maintains its guaranteed cash value and death benefit, but it will not grow beyond those minimums.
How do I know if my policy is participating?
Check your policy contract for terms like "Participating," "Right to Dividends," or "Dividend Options." If you see a dividend schedule in your annual statement, the policy is participating. Non-par policies, such as Universal Life or Term Life, will explicitly state that they do not pay dividends.
Is the cash value in a par policy protected from creditors?
In many states and countries, the cash value and death benefit of a life insurance policy are protected from creditors and lawsuits. This makes a par policy a popular asset protection tool for professionals in high-liability fields, such as medicine or law.
Can I change my dividend option after the policy is issued?
In most cases, yes. You can switch from "Paid-Up Additions" to "Reduce Premiums" or "Cash Payment" at any time. However, switching back to Paid-Up Additions may sometimes require simplified medical underwriting to ensure the increased death benefit doesn't pose an undue risk to the insurer.
What happens if I stop paying premiums on a par policy?
Par policies often have "Non-forfeiture Options." You can use the existing cash value to turn the policy into a "Reduced Paid-Up" policy (a smaller death benefit with no more premiums due) or "Extended Term" insurance. Alternatively, if the policy is mature enough, the dividends themselves might be large enough to cover the premiums automatically.
Final Recommendation: A Long-Term Perspective
A participating life insurance policy is one of the few financial products that has remained fundamentally unchanged for over a century, proving its resilience against economic cycles. In 2026, it remains a premier choice for individuals seeking a combination of permanent protection, tax-advantaged growth, and a "guaranteed" financial foundation.
To get the most out of a par policy, prioritize working with a highly-rated mutual insurance company with a Comdex score of 90 or higher. Ensure your agent structures the policy for "high cash value" by using a Paid-Up Additions rider, and view the premiums not as an expense, but as a transfer of wealth from a taxable environment to a tax-advantaged one. If you can commit to the first 10 years of premiums, the resulting "compounding machine" can provide a lifetime of financial security and a significant legacy for the next generation.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
