Navigating an Equity Loan on Rental Property: Options, Requirements, and Strategies

Accessing an equity loan on a rental property allows real estate investors to tap into their accumulated property value without selling their assets, providing capital for portfolio expansion, property renovations, or debt consolidation, though it generally requires substantial property equity, strong personal credit, and strict adherence to lender underwriting standards that differ significantly from primary residence mortgages.
Real estate investors continually seek efficient methods to grow their portfolios, manage liquidity, and maximize cash flow. One strategic financial instrument available to property owners is an equity loan on a rental property. Unlike a primary residence, where borrowing against home equity is a common and streamlined process, securing financing against an investment property involves a distinct set of regulatory guidelines, underwriting criteria, and financial risks. Understanding how these loans function, what lenders require, and how they compare to alternative financing methods is essential for any landlord or investor considering leveraging their real estate portfolio.
Understanding Equity on Investment Property
Equity represents the difference between the current market value of a rental property and the remaining balance of any mortgages or liens secured against it. As real estate markets appreciate over time and tenants pay down the principal balance of the mortgage, the equity in an investment property increases organically. Investors can also build equity through strategic property renovations that boost market value or by making accelerated mortgage payments.
When an investor applies for an equity loan on a rental property, they are essentially taking out a second mortgage or a lump-sum second lien against the property. The lender evaluates the property's appraised value, calculates the Loan-to-Value (LTV) ratio, and extends funds based on that verified financial cushion. Because rental properties carry inherently higher risk profiles for lenders compared to owner-occupied homes—tenants may vacate, rental income can fluctuate, and maintenance issues can arise unexpectedly—the terms, interest rates, and approval thresholds for investment property equity loans are more rigorous.
The Mechanism of Rental Property Equity Financing
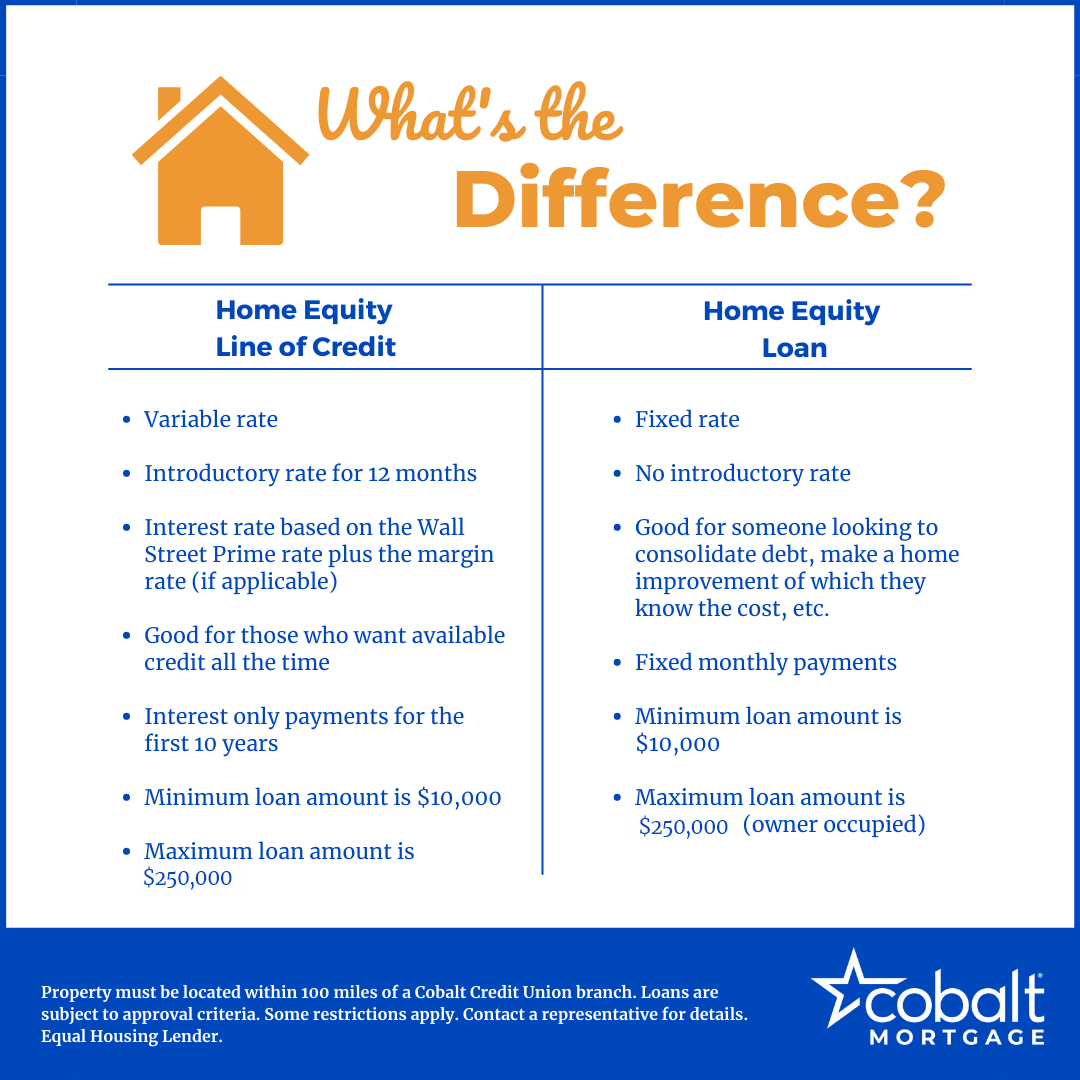
Unlike a home equity line of credit (HELOC), which provides a revolving line of credit that borrowers can draw from and repay dynamically, a traditional equity loan on a rental property delivers a single lump sum of cash at closing. This capital is repaid through fixed monthly payments over a predetermined amortization schedule, typically ranging from 5 to 30 years, carrying a fixed interest rate.
This predictability makes lump-sum equity loans attractive for investors who have a specific, one-time capital expense in mind, such as acquiring another property, executing a comprehensive multi-unit rehabilitation, or consolidating high-interest commercial debt. However, because the loan is secured directly by the rental property, defaulting on the loan payments puts the underlying real estate asset at risk of foreclosure.
Qualification Requirements and Underwriting Criteria
Qualifying for an equity loan on a rental property demands a higher level of financial documentation and stricter credit standards than a primary residence loan. Lenders want to ensure that the investor has both the personal financial stability to cover debt obligations during vacancy periods and the operational competence to manage the rental property successfully.
Credit Score and Debt-to-Income (DTI) Ratios
Lenders typically look for a minimum credit score of 700 to 740 for investment property financing, though some specialized portfolio lenders or credit unions may accept scores starting at 680 with compensating factors. A higher credit score directly correlates with more favorable interest rates.
In addition to credit scores, lenders examine the borrower's personal Debt-to-Income (DTI) ratio. Most conventional and portfolio lenders prefer a DTI ratio below 43%, though some institutional guidelines permit ratios up to 50% if the rental property generates significant positive cash flow and the borrower maintains substantial liquid reserves.
Loan-to-Value (LTV) Limitations
Because rental properties carry elevated risk, lenders rarely allow borrowers to tap 100% of their available equity. The maximum combined Loan-to-Value (CLTV) ratio for an equity loan on a rental property generally ranges from 70% to 75%, and occasionally caps at 65% depending on the lender and market conditions.
For example, if a rental property is appraised at $400,000 and the existing first mortgage balance is $200,000, the total equity is $200,000. If the lender enforces a maximum CLTV of 75%, the maximum total debt allowed against the property is $300,000 ($400,000 x 0.75). Subtracting the existing $200,000 mortgage leaves a maximum equity loan amount of $100,000.
Income Verification and Rental History
Underwriting an investment property equity loan involves evaluating both the borrower's personal income (W-2 earnings, self-employment income, or business revenue) and the income generated by the subject property. Lenders typically require:
- Two years of personal and business tax returns, including Schedule E (Supplemental Income and Loss) to verify rental income history.
- Current lease agreements for all units on the property.
- Profit and loss statements for the real estate portfolio.
- Proof of cash reserves (typically 3 to 6 months of mortgage payments for both the primary residence and all investment properties) to demonstrate liquidity.
Comparing Financing Options for Rental Property Equity
Investors have multiple avenues when accessing equity tied up in real estate. Choosing the right vehicle depends on the intended use of funds, the desired repayment structure, and current interest rate environments.
| Financing Option | Structure | Typical Interest Rate Type | Best Used For |
|---|---|---|---|
| Home Equity Loan | Lump-sum cash payout | Fixed | One-time capital needs, predictable long-term projects |
| HELOC | Revolving line of credit | Variable (occasional fixed options) | Phased renovations, ongoing capital expenditures, flexible reserves |
| Cash-Out Refinance | Replacing existing mortgage with a larger new loan | Fixed or Adjustable | Restructuring existing debt, locking in lower long-term rates |
Home Equity Loan vs. Cash-Out Refinance
When deciding between an equity loan (second mortgage) and a cash-out refinance, investors must analyze the interest rate on their existing primary mortgage. If an investor locked in a low mortgage rate during past economic cycles, executing a cash-out refinance would require replacing the entire existing loan at current, higher market rates. In this scenario, keeping the original low-rate first mortgage intact and adding a higher-rate second equity loan preserves the advantageous primary financing structure. Conversely, if current market interest rates are lower than or comparable to the existing mortgage rate, a cash-out refinance may provide a lower blended interest rate across the total borrowed amount.
Home Equity Loans vs. HELOCs on Investment Properties
While HELOCs offer flexibility by allowing borrowers to draw funds only as needed and pay interest solely on the drawn amount, they typically carry variable interest rates. In an inflationary or rising-rate environment, variable rates can increase monthly debt service obligations unpredictably. Equity loans provide absolute rate certainty through fixed monthly payments, shielding the investor from interest rate volatility. However, borrowers pay interest on the entire lump sum immediately upon closing, regardless of how quickly the capital is deployed.
Costs, Fees, and Tax Implications
Securing an equity loan on a rental property involves upfront transaction costs and complex tax considerations that must be factored into the investment's return metrics.
Closing Costs and Fees
Borrowers should anticipate paying between 2% and 5% of the loan amount in closing costs. These fees typically include:
- Appraisal Fees: Specialized investment property appraisals often cost more than standard residential appraisals due to the inclusion of local rental market comparable analyses.
- Title Search and Insurance: Ensures there are no secondary liens or encumbrances on the title prior to loan issuance.
- Origination and Underwriting Fees: Administrative charges levied by the lender to process the file.
- Recording Fees: Government fees associated with filing the new lien at the county recorder's office.
Tax Deductibility of Interest
Under United States federal tax law, interest paid on home equity loans is generally deductible only if the funds are used to buy, build, or substantially improve the taxpayer's primary or secondary residence. According to Internal Revenue Service (IRS) guidelines, interest on equity borrowed against an investment or rental property is typically treated as an ordinary and necessary business expense associated with managing the rental activity, rather than personal mortgage interest. Investors should consult a certified public accountant (CPA) or tax professional to determine how interest deductions apply to their specific corporate structure, LLC holdings, or personal tax returns.
Strategic Uses of Rental Property Equity
Deploying capital secured from a rental property requires disciplined capital allocation. Successful real estate investors utilize equity loans for value-add activities that generate a return exceeding the cost of borrowing.
Property Renovations and Value-Add Strategies
Using loan proceeds to upgrade kitchens, bathrooms, replace roofs, or improve energy efficiency can dramatically increase both the market value of the property and the achievable monthly rental income. This strategy aligns with the "BRRRR" (Buy, Rehab, Rent, Refinance, Repeat) methodology or general portfolio enhancement, allowing landlords to command higher rents in competitive housing markets.
Portfolio Expansion and Down Payments
Some investors utilize equity from an existing, paid-down rental property to fund the down payment on a new investment property acquisition. By leveraging existing assets rather than depleting liquid cash reserves, investors can scale their portfolios faster. However, this strategy increases total leverage across the portfolio, magnifying both potential returns and financial vulnerability if market values decline or vacancy rates rise.
Potential Risks and Mitigation Strategies
Leveraging rental property equity introduces significant financial exposure. Prudent investors implement risk mitigation strategies to protect their assets from unforeseen market downturns.
Over-leveraging and Cash Flow Compression
Adding a second monthly loan payment to a rental property reduces net operating income (NOI). If rental income drops due to extended tenant vacancies or local economic shifts, the combined mortgage and equity loan payments must still be met out of pocket. Investors should ensure that the property's debt service coverage ratio (DSCR)—calculated by dividing net operating income by total debt service—remains healthy, ideally staying well above 1.25.
Market Volatility and Declining Equity
Real estate markets are cyclical. If local property values decline sharply after securing an equity loan, the investor could find themselves in an "underwater" position where the total debt exceeds the property's market value. This restricts the ability to sell the property or refinance in the future without bringing cash to the closing table. To mitigate this risk, conservative investors maintain conservative LTV thresholds (e.g., keeping total debt below 60% of property value) and maintain robust cash reserves to absorb economic shocks.
Frequently Asked Questions
Can I get an equity loan on a rental property with bad credit?
Securing an equity loan with poor credit is exceptionally difficult through conventional lenders or major banks. Some private money lenders or portfolio lenders may approve loans for borrowers with lower credit scores, but they will charge significantly higher interest rates, demand lower LTV ratios, and require substantial compensating factors such as extensive liquid reserves or high property cash flow.
How long does it take to close an equity loan on an investment property?
The underwriting and closing timeline typically ranges from 30 to 45 days. The duration depends heavily on how quickly the investment property appraisal can be completed, the verification of rental income via tax returns and lease agreements, and the efficiency of the lender's underwriting department.
Are interest rates higher for investment property equity loans than primary residence loans?
Yes. Lenders view investment properties as higher-risk assets because borrowers are more likely to default on a rental property during financial distress than on their primary home. Consequently, interest rates on rental property equity loans generally carry a premium of 0.50% to 1.50% over owner-occupied home equity loans.
Can an LLC own the rental property and still qualify for an equity loan?
Yes, many rental properties are held within Limited Liability Companies (LLCs) for liability protection. However, finding a lender that offers equity loans to business entities can be more challenging than dealing with properties held in personal names. Borrowers may need to work with commercial lenders, portfolio lenders, or local credit unions, and personal guarantees from the LLC members are almost universally required.
What is the difference between a home equity loan and a cash-out refinance on a rental property?
A home equity loan creates a second lien against the property while leaving your existing first mortgage untouched, resulting in a second monthly payment. A cash-out refinance replaces your existing first mortgage entirely with a single, larger new loan, which pays off the old balance and provides the remaining difference in cash.
Conclusion and Next Actions
Accessing an equity loan on a rental property provides a viable path to liquidity, portfolio growth, and capital reinvestment without liquidating core real estate holdings. Because these financial products involve stricter underwriting standards, higher interest rates, and distinct tax considerations compared to primary residence loans, preparation is key. Investors should begin by verifying their personal credit health, calculating current property LTV ratios, gathering accurate lease agreements and tax documents, and consulting with qualified financial advisors or CPA professionals to evaluate how additional debt service will impact overall portfolio cash flow and risk exposure.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
