A term life insurance movie typically refers to cinematic thrillers, dramas, or neo-noirs where a life insurance policy—specifically a temporary, fixed-term death benefit—serves as a central plot device, motive for murder, or mechanism for financial deception. While "term life insurance" is a real-world financial product designed to protect dependents against financial loss for a set period, Hollywood often dramatizes its mechanics, underwriting, and payout conditions to create suspenseful narratives about fraud, betrayal, and high-stakes survival.
The Intersection of Cinema and Financial Protection
The motion picture industry has long turned to the financial services sector for narrative conflict. From corporate embezzlement to insurance fraud, the mundane realities of underwriting contracts become high-drama instruments when placed in the hands of screenwriters. Understanding how Hollywood portrays these contracts requires separating cinematic license from actual insurance principles.
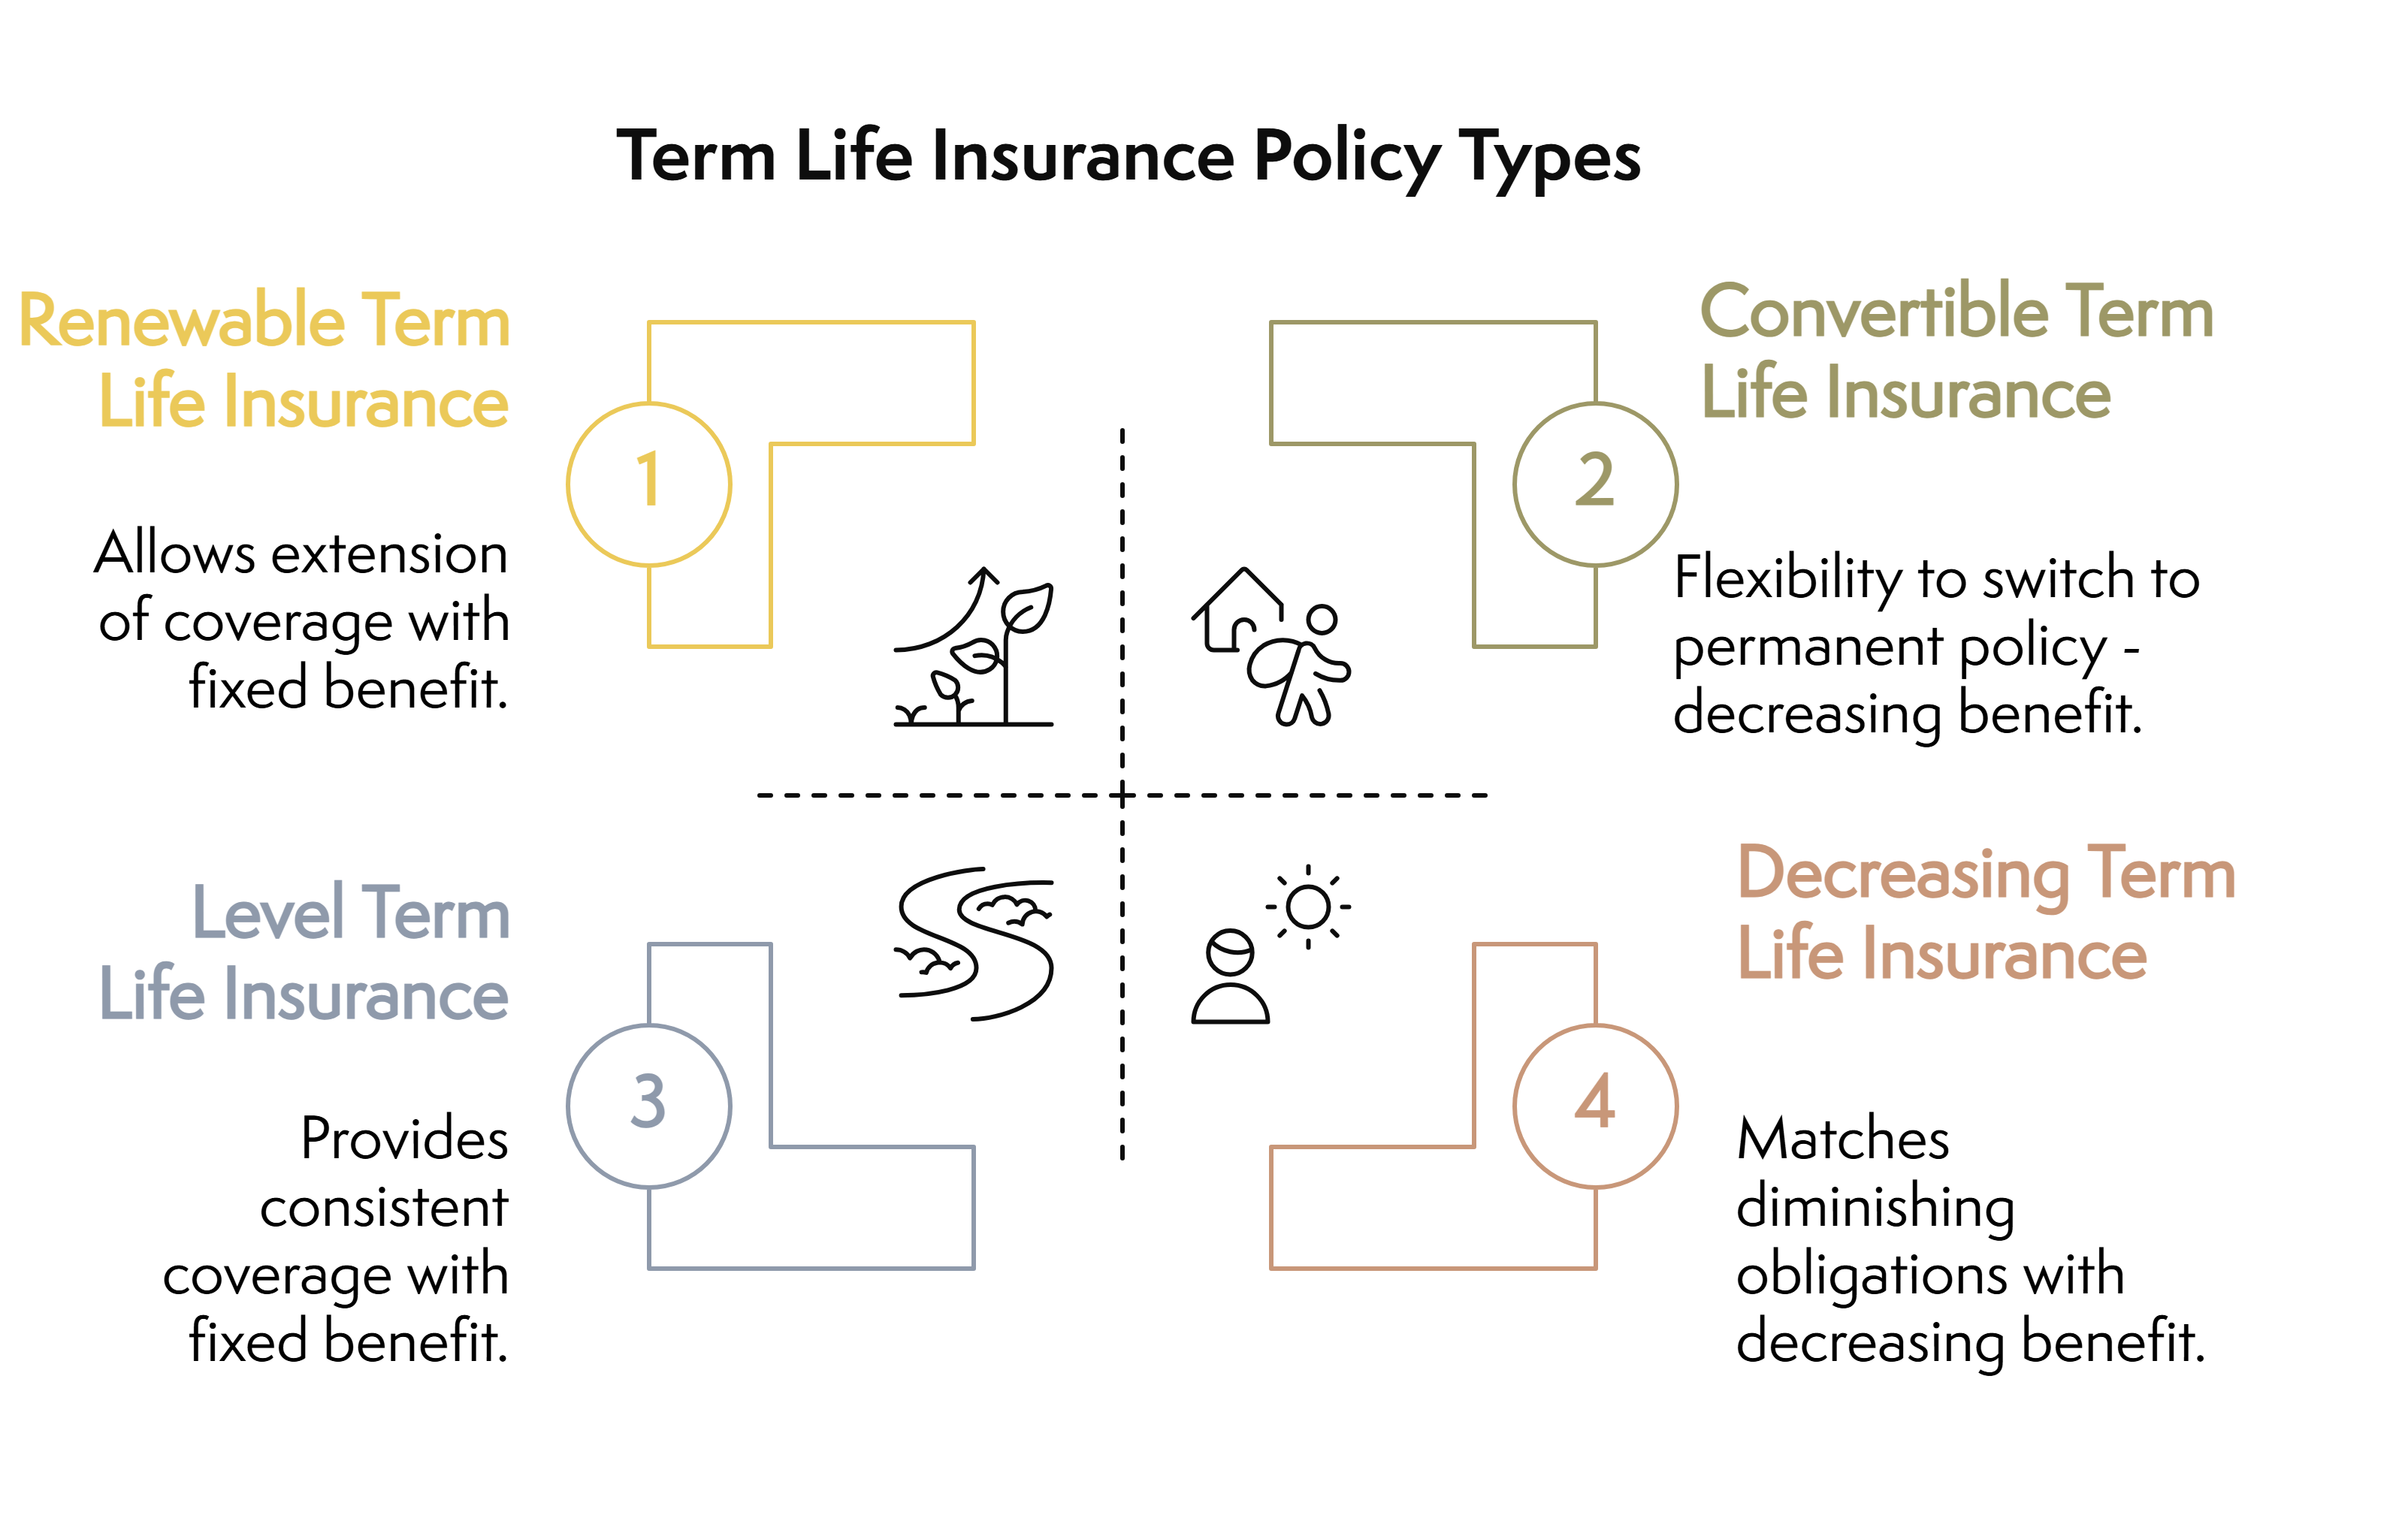
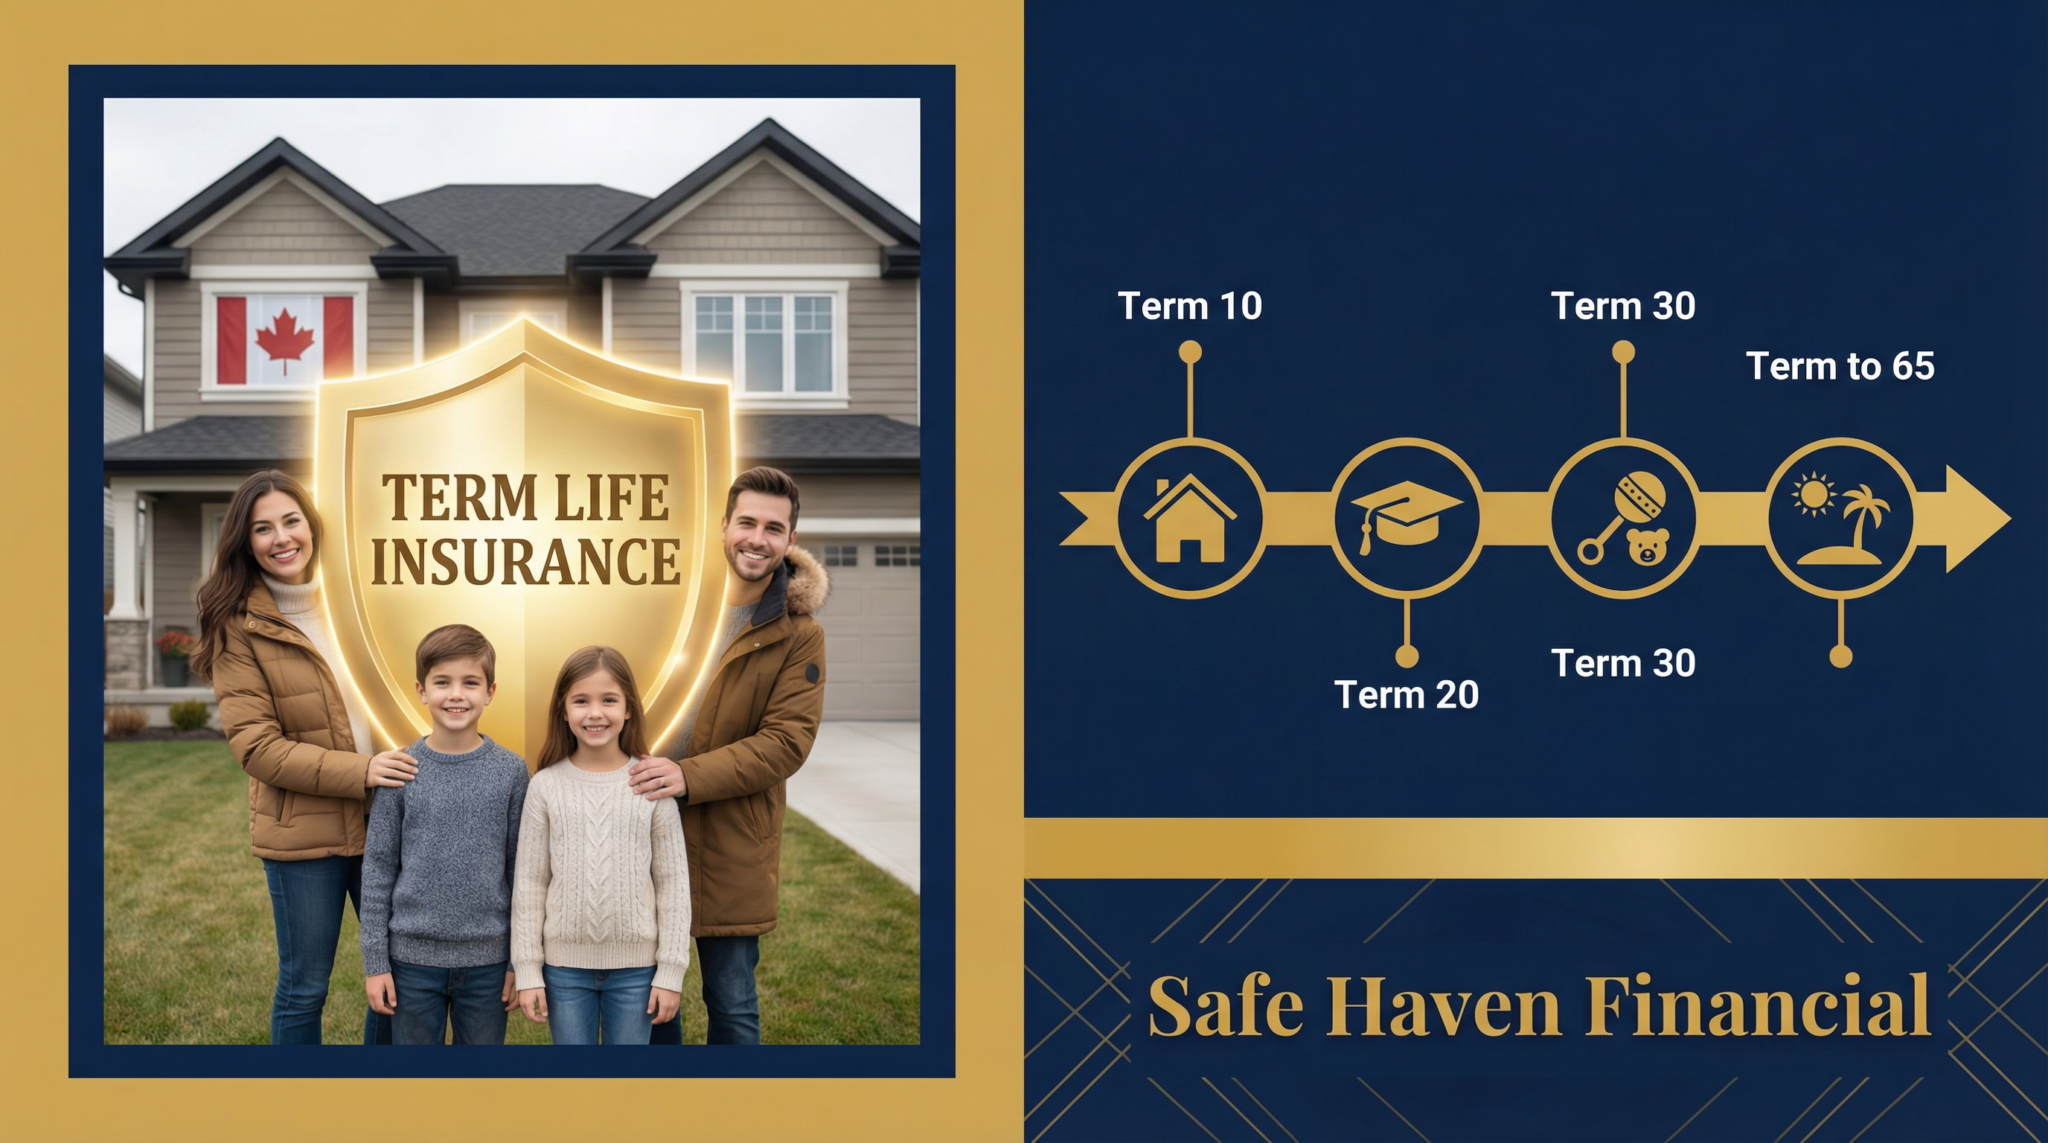
In reality, a term life insurance policy is a straightforward contract. A policyholder pays a fixed premium for a predetermined duration (such as 10, 20, or 30 years). If the insured individual passes away during that term, the designated beneficiaries receive a tax-free death benefit. If the term expires and the insured is still alive, the policy simply lapses with no payout unless it features a conversion option.
In film, however, this financial tool is frequently manipulated to serve specific narrative tropes. Screenwriters exploit the rigid timeline of term policies, the incontestability period, and the moral hazard inherent in naming beneficiaries to fuel suspense, psychological thrillers, and dark comedies.
Common Cinematic Tropes Involving Term Life Policies
When life insurance enters a movie script, it generally follows several well-established storytelling patterns. These tropes create dramatic tension, though they rarely reflect the strict legal and investigative realities of modern insurance claims.
1. The Pre-Meditated Murder Plot
Perhaps the most frequent trope features a character purchasing a hefty term life policy shortly before attempting to fake their own death or orchestrate their murder. The narrative tension relies on whether the beneficiary—often a spouse or business partner—can successfully execute the crime and collect the payout before insurance investigators uncover the plot.
2. The Accidental Discovery
A protagonist stumbles upon an unexpectedly large term life insurance policy taken out by a family member without their knowledge. This discovery transforms an ordinary domestic drama into a paranoid thriller, as the character begins to suspect that someone close to them is planning their demise or preparing for a catastrophic event.
3. The Terminal Diagnosis Race
In dramatic films, a character diagnosed with a terminal illness might attempt to secure a policy or manipulate an existing one to ensure financial security for their family. This often collides with strict underwriting rules regarding medical examinations and material misrepresentation, highlighting the desperation of the protagonist against corporate bureaucracy.
Realism vs. Hollywood Fiction: How Term Insurance Actually Works
To appreciate the plot mechanics of a life insurance movie, it helps to examine where Hollywood bends the rules of the financial industry. Real-world insurance companies employ sophisticated underwriting standards and anti-fraud protocols that would instantly short-circuit most movie plots.
| Feature / Scenario | Cinematic Portrayal | Real-World Reality |
|---|---|---|
| Issuance Speed | Policies are often secured in a single day with no questions asked to advance the plot quickly. | Comprehensive underwriting requires medical exams, laboratory tests, and background checks, often taking weeks. |
| Incontestability | Investigators struggle for years to find loopholes after a suspicious death. | Policies include a standard two-year contestability period where insurers can investigate material misrepresentation on the application. |
| Payout Investigation | Quick, easily manipulated payouts or instant denials based on flimsy hunches. | Rigorous claims investigations automatically trigger if a death occurs early in the policy term or under suspicious circumstances. |
| Insurable Interest | Characters can secretly insure anyone, including random acquaintances or enemies. | State laws strictly require an "insurable interest," meaning the beneficiary must suffer a genuine economic loss upon the insured's death. |
Notable Cinematic Examples and Plot Analysis
While there is rarely a mainstream blockbuster titled strictly Term Life Insurance, several notable films prominently feature life insurance fraud, policies, and investigations as their driving narrative force.
Double Indemnity (1944)
Directed by Billy Wilder, this quintessential film noir serves as the gold standard for insurance-themed cinema. The plot revolves around an insurance salesman who is seduced into a murder plot by a provocative housewife. Together, they attempt to murder her husband and collect under an "accidental death" rider—the titular double indemnity clause. The film meticulously details the investigative process of the insurance company's claims adjuster, highlighting how actuaries and investigators detect fraud.
Term Life (2016)
Sharing the exact terminology, this action-comedy-drama starring Vince Vaughn features a criminal who takes out a million-dollar term life policy to benefit his estranged daughter. The catch? The policy does not take effect until he is actually dead, and numerous contract killers, corrupt cops, and mobsters are hunting him down. He must figure out how to stay alive long enough for the policy's waiting period and effective date conditions to lock in, blending high-speed chases with literal estate planning.
Wild Things (1998)
While focusing more on a complex web of blackmail and high-stakes inheritance fraud rather than a pure term policy, this neo-noir thriller uses legal contracts, wills, and conditional payouts to deceive both the characters and the audience. It demonstrates Hollywood's fascination with how legal documents can be weaponized.
The Role of the Insurance Investigator in Film
In many suspense films, the hero or antagonist is not the policyholder, but the insurance investigator. These characters operate much like detectives, but their jurisdiction is financial.
In cinematic universes, these investigators look past grief to analyze bank statements, medical records, and policy inception dates. They represent the voice of institutional skepticism. While real-world claims adjusters and Special Investigation Units (SIUs) rely heavily on data analytics, forensics, and legal subrogation, cinematic investigators often engage in renegade fieldwork, chasing suspects across state lines to prove or disprove foul play.
Financial Literacy Takeaways from Insurance Dramas
Despite the extreme dramatization found in movies, these films occasionally spark broader conversations about financial planning, estate management, and consumer awareness.
- The Importance of Transparency: Hiding medical conditions or financial histories on an application (material misrepresentation) gives real-world insurers the legal right to void a policy—a plot point that mirrors actual contract law.
- Understanding Insurable Interest: Movies often stretch credibility by allowing characters to insure people they have no legal or financial connection to. In reality, insurance regulators prevent wagering on human lives through strict insurable interest laws.
- The Value of Legitimate Coverage: While thrillers focus on scams, the underlying utility of term life insurance remains standard practice for income replacement, debt protection, and ensuring dependents are cared for after an untimely death.
Frequently Asked Questions
What is a term life insurance movie?
A term life insurance movie is a film that uses a temporary life insurance policy, underwriting rules, or insurance fraud as a central plot device to drive conflict, mystery, or criminal suspense.
Are movie plots involving life insurance fraud realistic?
Most cinematic portrayals exaggerate how quickly policies can be obtained, how easily investigations can be bypassed, and how lax insurers are regarding insurable interest. Real-world insurers employ rigorous underwriting and fraud detection frameworks.
What classic film best illustrates life insurance investigations?
Billy Wilder's 1944 film noir Double Indemnity is widely considered the definitive cinematic exploration of life insurance claims, underwriting, and fraud detection.
Can someone take out a life insurance policy on another person without their knowledge?
No. In reality, life insurance underwriting requires the consent, signature, and often a medical examination of the person whose life is being insured, preventing the secret plots commonly seen in fiction.
Why do screenwriters use life insurance as a plot device?
Life insurance introduces immediate financial stakes, moral ambiguity, and clear timelines, making it an efficient narrative tool for generating suspense, greed-driven motives, and psychological conflict.
Next Steps for Consumers
If watching financial thrillers has prompted you to evaluate your own estate planning or risk management strategy, the appropriate next step is to consult a licensed, independent insurance professional or financial advisor. Reviewing actual policy documents, understanding underwriting requirements, and ensuring proper coverage amounts will provide real-world financial security without the cinematic drama.
Image Gallery
Select an image to open it in a new tab.




Celine Dubois
Contemporary Living and Global Arts Columnist
