Managing Permanent Life Insurance Claims When a Relative Passes Away

When a relative dies and you are the beneficiary of a permanent life insurance policy associated with Hogan Partners LLP or similar entities, the immediate priority is to understand the administrative path to claim the death benefit. To initiate this process, you must contact the issuing insurance carrier directly with the policy number and a certified death certificate, as the legal entity holding the policy serves primarily as a fiduciary or intermediary for the account documentation.
Understanding the Role of Hogan Partners LLP
In the context of life insurance, entities identified as "Hogan Partners LLP" or similar legal partnerships often act in a professional capacity rather than as the insurance underwriter itself. These organizations frequently serve as financial advisors, estate planning consultants, or trustees who manage complex permanent life insurance portfolios.
If you have discovered documentation referencing Hogan Partners LLP in the personal effects of a deceased relative, it is critical to clarify their specific role. They may be the agent of record, a trust administrator, or an investment advisor. Because permanent life insurance—often referred to as whole life, universal life, or variable life insurance—includes a cash value component and strict beneficiary designations, these entities often hold the records necessary to facilitate a smooth transfer of assets. They are not usually the insurer, but they are the primary point of contact for administrative assistance regarding policy management.
Immediate Steps Upon the Death of a Policyholder
Navigating the insurance claims process can be overwhelming during a time of bereavement. However, acting systematically ensures that you satisfy the requirements of the insurance carrier and avoid unnecessary delays.
- Locate the Policy Documentation: Search for the original insurance contract, premium notices, or any correspondence from Hogan Partners LLP. If you cannot find the physical policy, look for bank statements showing premium payments.
- Obtain Certified Death Certificates: Secure several copies of the death certificate. The funeral director typically assists with this. Most insurance companies require a certified copy with a raised seal; standard photocopies are rarely accepted.
- Contact the Insurer and the Partner Firm: If the policy indicates an agent or firm, notify them immediately. They can often provide the specific "Notice of Death" form required by the insurance company, which streamlines the filing process.
- Verify Beneficiary Status: Confirm that you are the primary beneficiary. If the estate is named, the process will involve the probate court, which necessitates interaction with the executor or administrator of the estate.
Identifying the Permanent Life Insurance Structure
Permanent life insurance differs significantly from term life insurance. Understanding the nature of the policy held by your relative is essential for managing your expectations regarding the payout and any potential tax implications.
- Whole Life Insurance: This is the most common form of permanent insurance. It features fixed premiums and a guaranteed death benefit. The cash value grows at a steady rate.
- Universal Life Insurance: These policies offer more flexibility. Policyholders can often adjust their premiums and death benefits. However, if the account value is insufficient to cover internal costs, the policy may lapse unless handled correctly during the claim period.
- Variable Life Insurance: The cash value is tied to sub-accounts, similar to mutual funds. The death benefit may fluctuate based on investment performance, though most permanent policies have a guaranteed floor.
When a relative passes, the insurance company will perform a "date of death valuation." This calculation determines the exact value of the policy, including any accumulated dividends or unpaid loans, as of the day the insured person passed away.
Documentation Requirements for Claimants
Insurance carriers require specific evidence to process a death claim. While every company has its own internal protocols, the following documentation is standard across the industry in 2026.
| Document Type | Purpose | Requirement |
|---|---|---|
| Claim Form | Official request for benefits | Required for every beneficiary |
| Death Certificate | Legal proof of death | Must be certified/original |
| Policy Document | Contract identification | Helpful, but not always strictly required |
| Proof of Identity | Anti-fraud verification | Government-issued photo ID |
| Trust Documents | Required if a trust is the beneficiary | Legal copy of trust agreement |
If the policy has been held for many years, it is possible that the insurance company has been acquired or merged. If you encounter difficulty locating the carrier, check the National Association of Insurance Commissioners (NAIC) Life Insurance Policy Locator service, which helps beneficiaries find missing policies by searching for matches against the information of the deceased.
Potential Financial and Tax Considerations
Receiving a death benefit is generally a tax-advantaged event. In most jurisdictions, life insurance proceeds are not considered taxable income for the beneficiary. However, there are nuances to consider regarding the estate:
- Estate Taxes: If the deceased owned the policy at the time of death, the value of the death benefit may be included in the total taxable estate. If the estate exceeds current federal or state thresholds, inheritance taxes might apply.
- Accrued Interest: If there is a delay in paying the death benefit, the insurer may owe interest on the proceeds. This interest is generally considered taxable income.
- Policy Loans: If the deceased had taken out loans against the cash value of the permanent life insurance policy, those loans will be deducted from the final death benefit payout before you receive it.
Consulting with a tax professional or an estate attorney is advisable if the policy is substantial or if there are complications regarding the distribution of assets among multiple beneficiaries.
Common Hurdles and Troubleshooting
Beneficiaries often encounter specific challenges during the claims process. Awareness of these issues can help you proactively address them.
1. Outdated Beneficiary Designations: If the listed beneficiary has predeceased the policyholder or is an ex-spouse, the policy may default to the estate. This can complicate the distribution and subject the funds to the probate process, which is often lengthy.
2. Policy Lapses: If the policyholder missed premium payments in their final years, the policy may have lapsed. However, many permanent policies have "automatic premium loan" provisions or "non-forfeiture options" that might keep the coverage in effect for a limited period. Always request a full policy history if the insurance company claims the policy was inactive.
3. Contestable Periods: If the policy was issued very recently (typically within the last two years), the insurance company may conduct a contestability investigation. This is a standard procedure to ensure the policyholder did not make material misrepresentations on their original application.
4. Intermediary Delays: If Hogan Partners LLP is holding original documents or acts as the trustee, they may have their own internal verification procedures before they can release documentation to you. Maintain clear, written communication and follow up regularly if you do not receive a response within a reasonable timeframe (typically 7–10 business days).
Communicating with Professionals
When contacting Hogan Partners LLP or other financial entities, always keep a record of your interactions. Follow these best practices:
- Use Registered Mail: For sending original death certificates or legal forms, use a tracked shipping method to ensure documentation is received and signed for.
- Keep a Log: Note the date, the name of the representative you spoke with, and a summary of what was promised or requested.
- Request Written Confirmations: After a phone call, ask the representative to send a follow-up email confirming the status of your claim or the specific items you are required to submit next.
Frequently Asked Questions
What happens if I cannot find the original policy document? You do not strictly need the original physical policy to file a claim. Insurance companies maintain digital records of all active policies. If you can provide the deceased’s full name, Social Security number, and date of birth, the insurance carrier can usually locate the policy information. Contacting the agent or firm associated with the policy, such as Hogan Partners LLP, is the fastest way to retrieve these details.
How long does it typically take to receive the death benefit? Once a complete "proof of death" package (including the claim form and certified death certificate) is submitted and verified, most insurance companies issue payment within 30 days. If the claim requires further investigation or if there are multiple beneficiaries who have not yet submitted their forms, this timeline may be extended.
Do I need a lawyer to claim life insurance benefits? In most cases, you do not need an attorney. The claim process is designed to be accessible to beneficiaries. However, if there is a dispute regarding who is the rightful beneficiary, if the estate is being contested, or if there are significant tax implications, legal counsel specializing in estate law is highly recommended.
Can I get a partial payment if the claim is going to take a long time? Generally, insurers do not issue partial payments. The claim is treated as a single event. If you are experiencing financial hardship due to the death of the relative, discuss this with the insurance carrier’s claims department, though they are under no obligation to deviate from their established payout schedule.
What is the difference between a "contingent" and "primary" beneficiary? A primary beneficiary is the first person in line to receive the death benefit. A contingent beneficiary only receives the proceeds if the primary beneficiary has already passed away or is unable to accept the funds. Always ensure your relative’s records correctly reflect the intended hierarchy to prevent legal disputes.
Next Steps and Recommendations
If you are currently processing a claim, your immediate next step is to secure the certified death certificates and identify the underwriting insurance carrier. Do not rely solely on the information provided by any third-party firm; verify all information directly with the insurance company’s official claims department. Maintain a dedicated folder for all correspondence, as this documentation will be vital for your personal financial records and for any potential tax reporting next year. If you find the complexity of the policy exceeds your comfort level, reach out to a fee-only financial planner who can provide objective guidance without a conflict of interest.
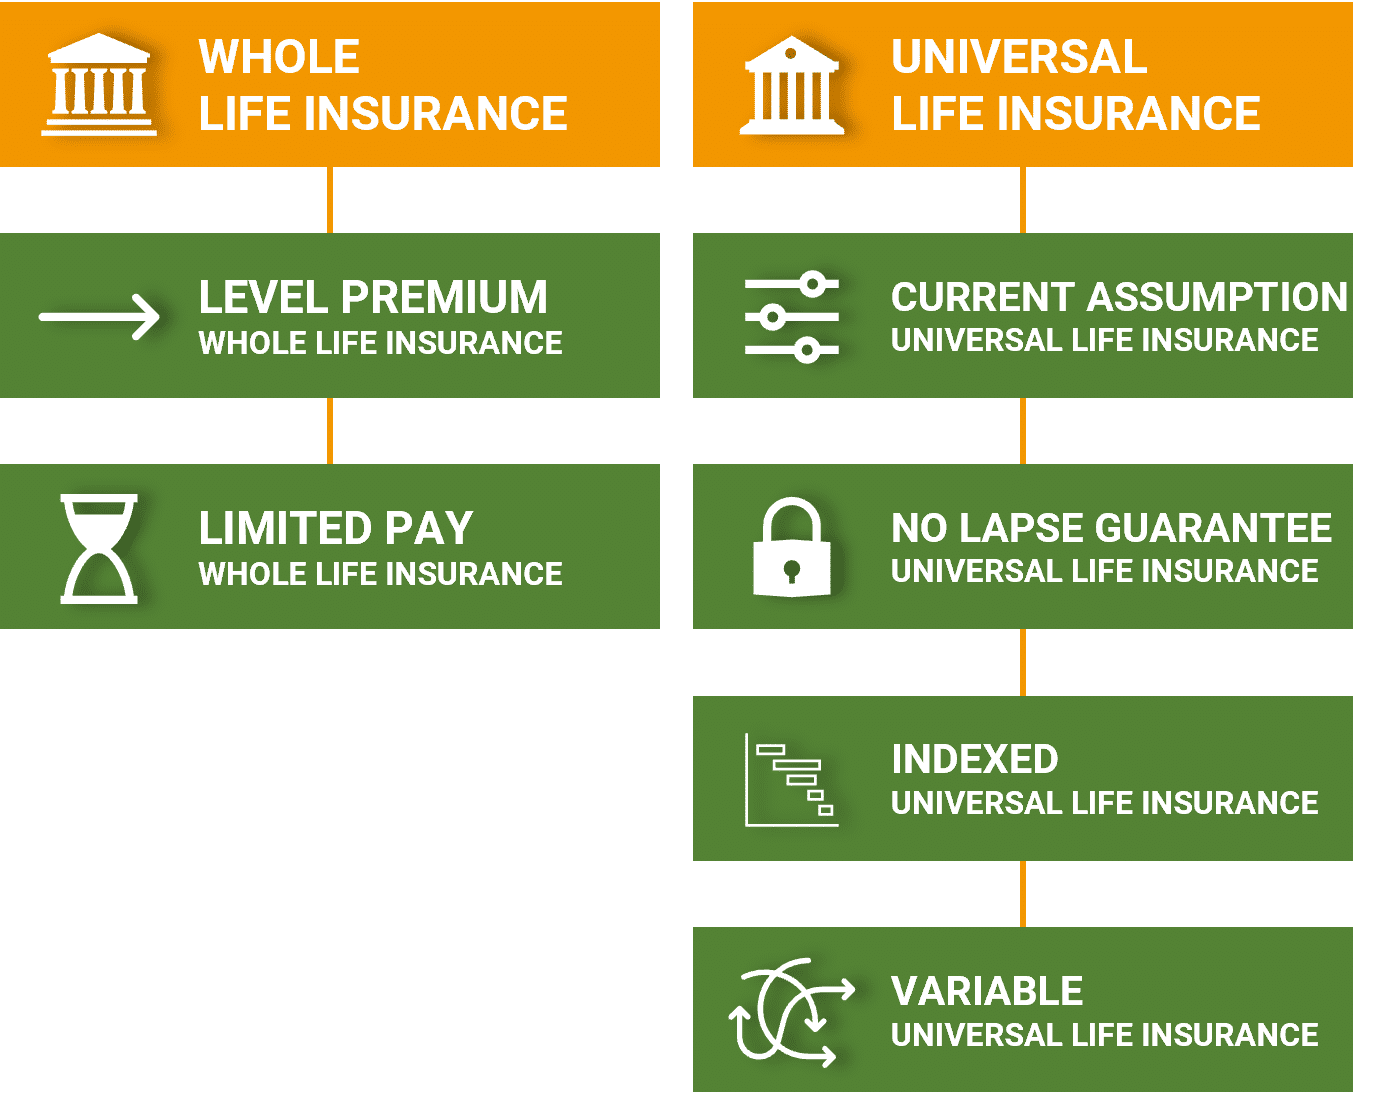
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
