
By 2026, non-traditional mortgage lenders—primarily non-bank fintechs and private lending institutions—have become the dominant force in residential real estate, originating over 70% of all home loans. These lenders shape homebuying by increasing market liquidity, providing specialized loan products for gig-economy workers, and utilizing advanced automation to drastically reduce closing times compared to traditional depository banks.
The mortgage landscape has undergone a seismic shift. For decades, the local bank was the gatekeeper of homeownership. Today, the "non-bank" sector, which includes independent mortgage companies and tech-driven platforms, has redefined the rules of engagement. This evolution is not merely a change in who provides the capital; it is a fundamental restructuring of how credit is assessed, how fast transactions occur, and who is eligible to participate in the housing market.
The Rise of the Non-Bank: A Structural Shift in Finance
To understand how non-traditional lenders shape homebuying, one must first define what they are. Unlike traditional banks (such as JPMorgan Chase or Bank of America), non-traditional lenders are non-depository institutions. They do not hold consumer checking or savings accounts. Instead, they fund loans through warehouse lines of credit and sell those loans on the secondary market to Government-Sponsored Enterprises (GSEs) like Fannie Mae and Freddie Mac, or to private investors.
The growth of these entities accelerated following the Great Recession, as traditional banks faced stricter capital requirements and retreated from "riskier" or more complex mortgage originations. By 2026, firms like Rocket Mortgage, Better.com, and United Wholesale Mortgage (UWM) have moved from the periphery to the center of the financial ecosystem. Their presence has forced a modernization of the entire industry, shifting the focus from physical branch visits to mobile-first, data-integrated applications.
Expanding Access Through Alternative Underwriting
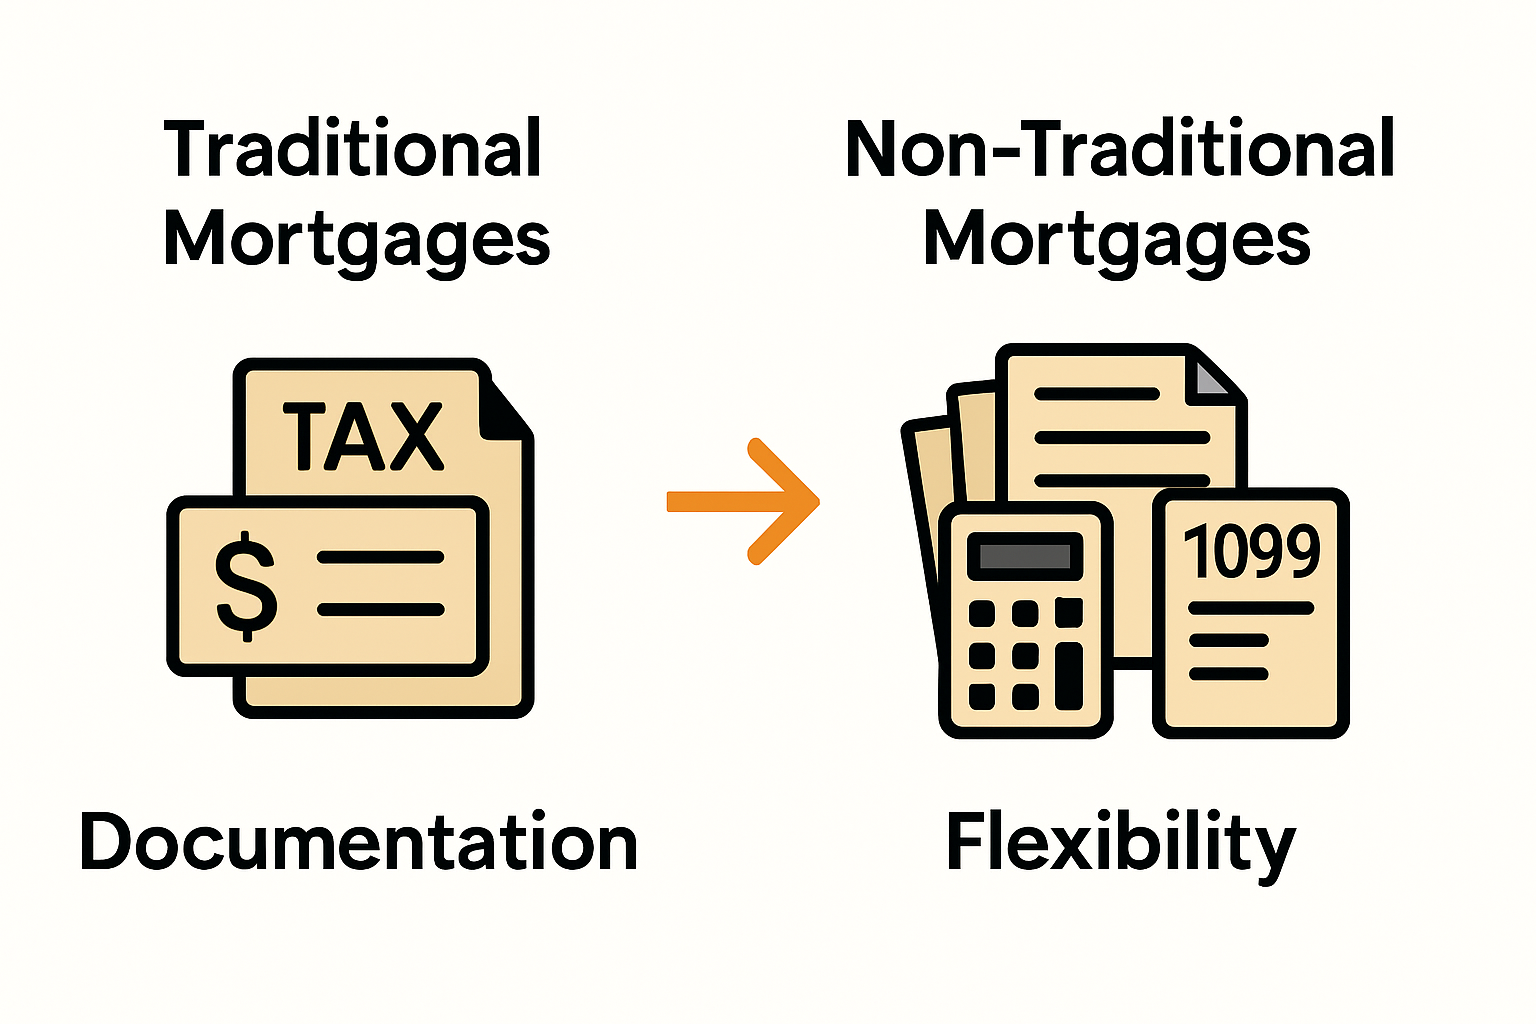
One of the most significant ways non-traditional lenders shape homebuying is by expanding the pool of eligible borrowers. Traditional banks often rely on rigid, automated underwriting systems that favor W-2 employees with long-term stability in a single industry. However, the 2026 workforce is increasingly composed of freelancers, entrepreneurs, and "1099" contractors.
Bank Statement and Asset Depletion Loans
Non-traditional lenders have filled the gap left by banks by championing "Non-QM" (Non-Qualified Mortgage) products. These include:
- Bank Statement Loans: Instead of tax returns, which may show low net income due to business deductions, lenders analyze 12 to 24 months of deposits to determine true cash flow.
- Asset Depletion Loans: For retirees or high-net-worth individuals with low monthly income but significant liquid assets, these loans calculate a monthly "income" based on the total value of their holdings.
By moving away from the standard debt-to-income (DTI) calculations used by the Federal Housing Administration (FHA) and conventional GSE guidelines, non-traditional lenders allow self-employed buyers to compete in high-demand markets where they were previously sidelined.
DSCR Loans for Small-Scale Investors
The rise of the Debt Service Coverage Ratio (DSCR) loan has also transformed the "buy-to-let" market. Non-traditional lenders offer these loans based on the projected rental income of the property rather than the borrower’s personal income. This has allowed a new class of "mom-and-pop" investors to enter the market, increasing competition for entry-level homes but also providing a consistent flow of capital into the renovation and rental sectors.
Accelerating the Transaction Velocity
In a competitive real estate market, speed is a currency. Non-traditional lenders have utilized proprietary technology to slash the time between application and closing. In 2026, the industry standard for a traditional bank closing remains 30 to 45 days. In contrast, many fintech-driven lenders can offer "verified pre-approvals" in minutes and close loans in as little as 10 to 14 days.
AI and Automated Appraisals
The integration of Artificial Intelligence (AI) in 2026 has allowed non-traditional lenders to move toward "appraisal waivers" on a larger scale. By using massive datasets of recent sales, satellite imagery, and interior data, these lenders can often bypass the physical appraisal process, which is a frequent bottleneck in homebuying. This speed allows buyers using non-traditional financing to compete more effectively against all-cash offers, which have historically dominated tight markets.
Digital Closing Rooms
The transition to fully digital closings (e-Closings) and Remote Online Notarization (RON) was spearheaded by non-banks. By removing the need for physical paperwork and in-person meetings, these lenders have made it possible for buyers to purchase homes across state lines with minimal friction. This has been a primary driver of the "geographic decoupling" of the workforce, where buyers live in different states than their employers.
Impact on Housing Competition and Pricing
While non-traditional lenders increase access, their role in shaping the market is not without controversy. By lowering the barriers to entry, they naturally increase the number of active buyers in the market. In an environment with limited housing inventory—a persistent issue in 2026—this increased demand can lead to upward pressure on home prices.
Furthermore, the proliferation of "bridge loans" and "cash-offer programs" offered by non-traditional entities has changed the negotiation dynamics. Some lenders now offer to buy a home in cash on behalf of the borrower, then sell it back to them once their traditional mortgage is finalized. This "institutionalizing" of the individual buyer allows them to compete with hedge funds but also adds a layer of fees and complexity to the transaction.
Risk Profiles and Market Stability
The shift from banks to non-banks has fundamentally altered the risk profile of the U.S. housing market. Because non-traditional lenders do not have deposits to fall back on, they are more sensitive to liquidity crunches.
The Role of Warehouse Lending
Non-traditional lenders depend on "warehouse lines" from larger banks to fund their originations. If the credit markets tighten—as seen in various cycles leading up to 2026—these lenders may suddenly pull back on their offerings. This can lead to "mortgage deserts" where specialized loan products disappear overnight, leaving borrowers in the lurch during a transaction.
Regulatory Oversight
The Consumer Financial Protection Bureau (CFPB) and the Federal Housing Finance Agency (FHFA) have increased their scrutiny of non-bank lenders. Concerns often center on whether these lenders provide adequate servicing for loans, especially during periods of economic downturn where loan modifications or foreclosures become necessary. Unlike banks, which have a long history of federal oversight, the non-bank sector is a more fragmented regulatory landscape, involving various state-level licenses and federal guidelines.
Comparison: Traditional Banks vs. Non-Traditional Lenders (2026)
| Feature | Traditional Banks (Depository) | Non-Traditional Lenders (Fintech/Non-Bank) |
|---|---|---|
| Primary Funding | Customer Deposits | Warehouse Lines & Secondary Market |
| Underwriting Style | Conservative, W-2 focused | Flexible, Niche-product focused |
| Approval Speed | Slow (Weeks) | Fast (Days/Minutes) |
| Tech Integration | Legacy systems with digital overlays | Native digital-first platforms |
| Credit Requirements | Higher FICO minimums | Wider range (including low/no-FICO) |
| Personal Relationship | High (In-branch services) | Low (Primarily digital/phone) |
| Regulation | High (OCC, FDIC, Fed) | Moderate (CFPB, State Regulators) |
The Cost Perspective: Rates and Fees
A common misconception is that non-traditional lenders are always more expensive. In reality, their lower overhead—no physical branches to maintain—often allows them to offer competitive interest rates. However, they may charge higher "origination fees" or "underwriting fees" to compensate for the speed and flexibility they provide.
For Non-QM products (like the aforementioned bank statement loans), interest rates are typically 1% to 2% higher than standard conventional rates. This "risk premium" is a key characteristic of how these lenders shape the market: they provide a path to homeownership for those who cannot fit the "Gold Standard" mold, but that path comes with a higher long-term cost.
Navigating the 2026 Mortgage Market
For a homebuyer in 2026, the choice between a traditional bank and a non-traditional lender often comes down to the complexity of their financial situation.
- The "Standard" Buyer: If you have a high credit score, a 20% down payment, and a stable W-2 job, a traditional bank may still offer the lowest absolute cost due to lower fees and "relationship pricing" for existing customers.
- The "Complex" Buyer: If you are an entrepreneur, have a fluctuating income, or need to close a deal in under 15 days to beat a competitor, a non-traditional lender is often the only viable path.
- The "Investor" Buyer: For those building a portfolio, the specialized products offered by non-banks (like DSCR loans) provide scalability that traditional banks, with their strict limits on the number of financed properties per individual, cannot match.
Frequently Asked Questions
Are non-traditional mortgage lenders safe?
Yes, non-traditional lenders are regulated by the Consumer Financial Protection Bureau (CFPB) and must comply with the Secure and Fair Enforcement for Mortgage Licensing Act (SAFE Act). While they do not have the same FDIC insurance as banks (since they don't take deposits), the loans they issue are subject to strict federal consumer protection laws regarding disclosure, fair lending, and predatory practices.
Can I get a FHA or VA loan from a non-traditional lender?
Absolutely. In fact, non-traditional lenders are among the largest originators of FHA and VA loans in the country. Their streamlined digital processes often make the typically paperwork-heavy government loan process much faster for veterans and first-time buyers.
Why do non-traditional lenders close faster?
They use API-based integrations to verify data in real-time. Instead of a borrower manually uploading a PDF of a bank statement, the lender connects directly to the financial institution to verify assets. AI-driven underwriting engines can then clear "conditions" instantly, whereas a traditional bank may require a human underwriter to review each document sequentially.
Do non-traditional lenders sell my loan?
Almost always. Most non-traditional lenders are "originate-to-sell" shops. They make their profit on the origination fees and the "service release premium" when they sell the loan to an investor or a larger servicing company. This means the company you close your loan with may not be the company you send your monthly checks to for the next 30 years.
What happens if a non-traditional lender goes out of business?
If a lender goes bankrupt, your mortgage contract remains valid. The "servicing rights" (the right to collect your payments) are a valuable asset that would be sold to another financial institution. Your interest rate, term, and balance do not change; you simply receive a notice telling you where to send your payments in the future.
Recommendations for Modern Homebuyers
To navigate this landscape effectively in 2026, buyers should prioritize pre-approval diversity. Do not simply get a pre-approval from your local bank; obtain a second one from a tech-driven non-bank lender. This allows you to compare not just the interest rate, but the "closing guarantee" and the flexibility of the underwriting.
Furthermore, buyers should be wary of the "convenience tax." The ease of a mobile app can sometimes mask higher-than-average closing costs. Always request a Loan Estimate (LE) from at least three different types of lenders to ensure that the speed of a non-traditional lender isn't costing you tens of thousands of dollars over the life of the loan.
Ultimately, non-traditional lenders have democratized access to the American Dream, shifting the power from old-guard institutions to the consumer. By understanding their business models and the niche products they offer, you can leverage their technology to secure a home in an increasingly competitive and complex market.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
