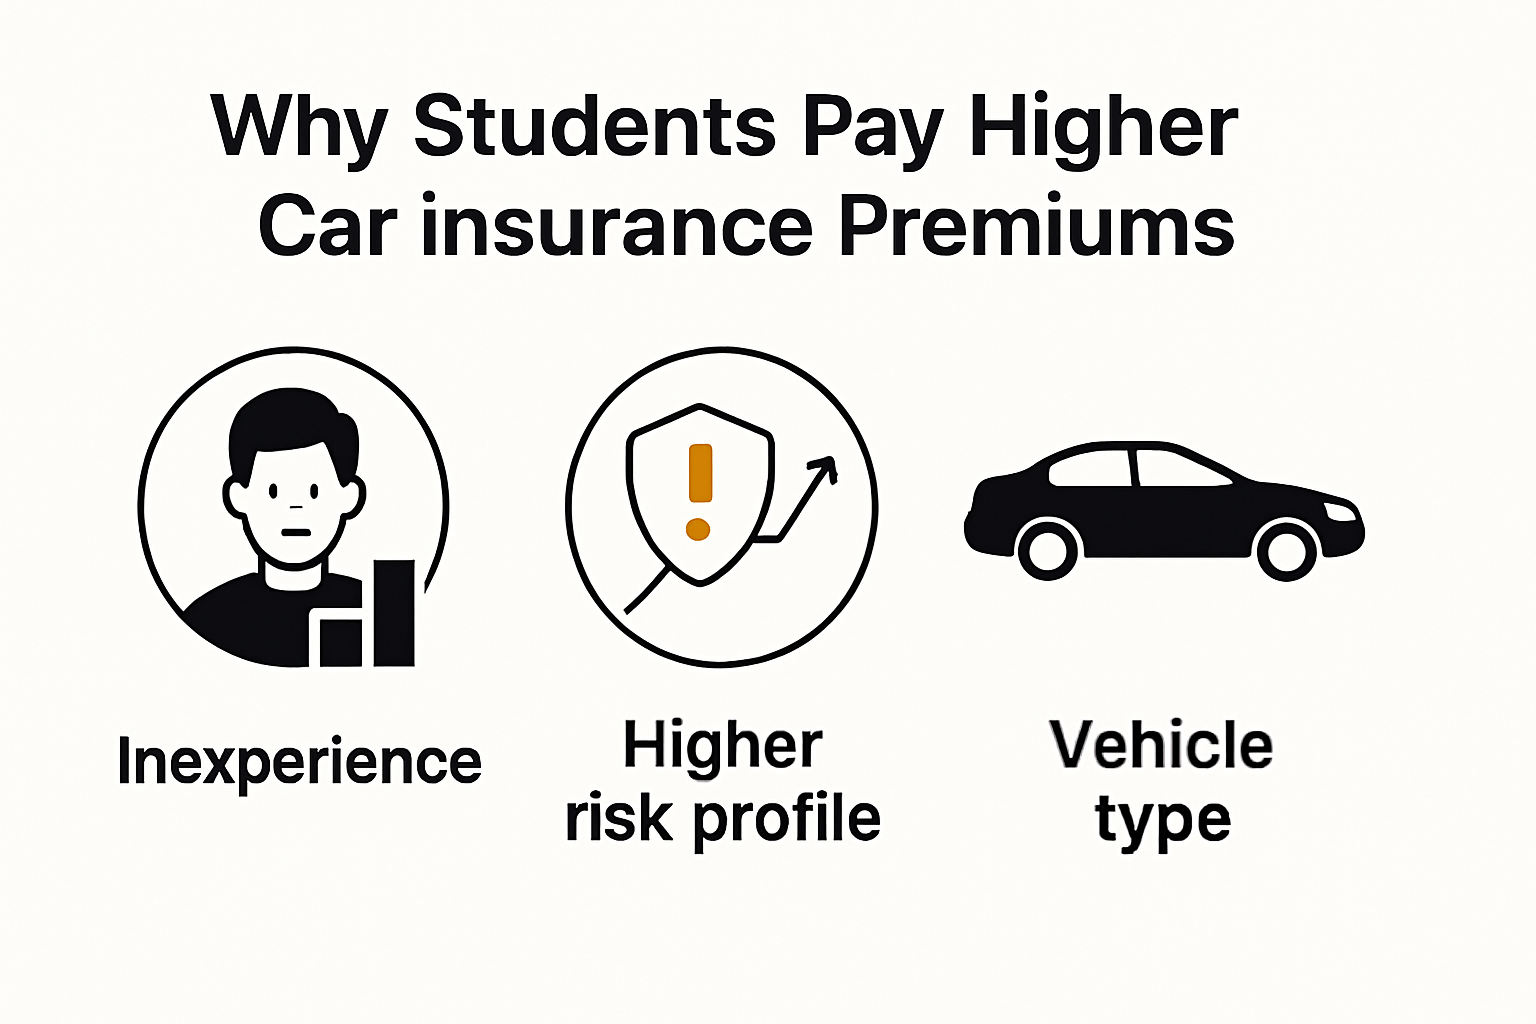
Securing affordable and reliable auto insurance for college students involves balancing coverage requirements with cost-saving strategies such as good student discounts, bundling, and choosing appropriate deductible levels. By understanding state minimums versus recommended coverage, students can mitigate high premiums typical for this demographic while ensuring adequate protection against significant financial liability.
Understanding the College Driver Risk Profile
Insurance providers classify college-aged drivers—typically those between the ages of 18 and 24—as high-risk. This classification is primarily driven by statistical data rather than individual behavior. Actuaries rely on historical loss data showing that younger, less experienced drivers are involved in a higher frequency of accidents.
When you enter the market for a policy in 2026, you are navigating a landscape where premiums are calculated based on a complex algorithm. These algorithms account for your age, location, the make and model of your vehicle, and your driving record. For a college student, the lack of a long credit history or a multi-year driving record often forces insurers to lean heavily on age-based risk assessment, leading to higher baseline rates compared to older, more experienced drivers.
Prerequisites for Obtaining Coverage
Before you begin shopping for quotes, you must have several key documents and pieces of information ready. Insurance companies require these to generate accurate quotes and verify your eligibility for specific discounts.
Essential Documentation
- Driver’s License: A valid, current driver’s license is required. If your license was issued in a different state than where you currently reside for school, check with your insurer; some states mandate that you obtain a local license if you stay for a set period.
- Vehicle Information: You will need the Vehicle Identification Number (VIN), current mileage, and information regarding safety features (e.g., anti-lock brakes, airbags, anti-theft systems).
- Driving History: While you may not have much, any moving violations or past accidents must be disclosed. Transparency is critical, as insurers will pull your Motor Vehicle Report (MVR) regardless.
- Academic Records: To qualify for "good student" discounts, you will need proof of your GPA or status on the dean's list. Most insurers require a GPA of 3.0 (or a "B" average) or higher.

Navigating Coverage Requirements
One of the most common mistakes college students make is opting for the absolute minimum coverage to save money. While this lowers your monthly premium, it exposes you to immense financial risk if you are found at fault in a major accident.
Minimum vs. Recommended Coverage
- Liability Coverage: This covers the costs of damages or injuries you cause to others. State minimums are often insufficient; if you cause a multi-car accident, legal and medical bills can easily exceed the state-mandated limits, leaving your personal assets vulnerable.
- Collision and Comprehensive: These cover damage to your own vehicle. If you drive an older, high-mileage vehicle, the cost of these premiums might exceed the current market value of the car. However, if you are driving a newer car or financing one, your lender will mandate these coverages.
- Uninsured/Underinsured Motorist (UM/UIM): This is essential. It covers your own medical expenses and property damage if you are hit by a driver who lacks sufficient insurance. Given that many drivers operate with bare-minimum policies, UM/UIM coverage is a vital layer of protection.
Strategy: Saving Money as a Student
Achieving the "best" insurance is not just about the lowest price; it is about finding the highest value for your budget. Use these strategies to lower your premiums in 2026.
Stay on Parents' Policy
If possible, remaining on your parents’ auto insurance policy is almost always the most cost-effective route. Insurers often provide multi-driver discounts, and the premium increase for adding a student is typically lower than the cost of a standalone policy for a young driver.
Good Student Discount
Most major insurers offer a discount for students who maintain a GPA of 3.0 or higher. This is one of the most reliable ways to shave 5% to 15% off your premium. You must provide a current transcript or report card to verify this annually.
Telematics Programs
Many insurance companies now offer mobile apps or plug-in devices that track your driving habits—speed, braking intensity, and time of day. If you are a safe driver, these programs can lead to significant premium reductions. However, be aware that poor driving habits can lead to rate increases in some jurisdictions.
Higher Deductibles
Increasing your deductible—the amount you pay out-of-pocket before insurance kicks in—is an effective way to lower your monthly premium. If you have an emergency fund, raising your collision or comprehensive deductible from $500 to $1,000 can result in immediate cost savings.
Comparison Table: Common Insurance Adjustments
| Strategy | Potential Savings | Requirement |
|---|---|---|
| Good Student Discount | 5%–15% | GPA 3.0+ (B average) |
| Raising Deductible | 10%–20% | Available emergency savings |
| Multi-Policy Bundle | 5%–10% | Insuring home/renters with same company |
| Telematics/Safe Drive | 10%–30% | Participation in tracking program |
Choosing the Right Provider
Not all insurance carriers weigh factors the same way. When requesting quotes, it is important to solicit information from both national carriers and regional mutual companies. National carriers often have robust mobile apps and better digital integration, which appeals to students, but regional carriers may offer more competitive rates in specific states or college towns.
When evaluating a quote, look beyond the premium price. Check the insurer's Financial Strength Rating (provided by agencies like AM Best) to ensure they have the capital to pay claims. Additionally, search for independent consumer satisfaction surveys or look at the National Association of Insurance Commissioners (NAIC) complaint index for your state to see how the company handles the claims process.
Frequently Asked Questions
Is it cheaper to stay on my parents' insurance or get my own?
Staying on your parents' insurance is almost universally cheaper. Adding a young driver to an existing policy leverages the parents' mature credit history and multi-car discounts, which a college student living alone cannot replicate.
Do I need to tell my insurer if I move away for college?
Yes. If you are attending school in a different city or state, your risk profile changes based on the local crime rate, traffic density, and state laws. Failing to update your "garaging address" can lead to a denial of a claim or cancellation of your policy for misrepresentation.
What happens if I go to school without a car?
If you are attending college far from home and leaving your car behind, ask your insurer about a "student away at school" discount. If you only drive when you are home on breaks, you may be able to significantly reduce your premium while keeping your policy active to maintain continuous coverage.
Does my GPA really affect my insurance rate?
Yes, for students under 25, many insurance companies treat a high GPA as a proxy for responsibility. Statistics suggest that students who prioritize academic performance are statistically less likely to engage in risky driving behaviors.
When should I switch to my own policy?
You should consider your own policy once you are financially independent, have your own vehicle registration in your name, and no longer reside at your parents' primary residence for the majority of the year.
Practical Next Steps for 2026
To secure the best auto insurance for your situation, follow this orderly process:
- Audit Your Assets: Determine if you need comprehensive and collision coverage based on the value of your vehicle.
- Gather Records: Collect your most recent transcript, driver's license, and current policy information.
- Get Multiple Quotes: Use the "Quote" tools from at least three national and two regional carriers. Ensure you are requesting the exact same coverage limits for a fair "apples-to-apples" comparison.
- Inquire About Discounts: Specifically ask about the "Good Student" and "Away at School" discounts during the application process.
- Review the Fine Print: Before finalizing, read the declarations page to verify that all applicable discounts have been applied and that the coverage limits match your needs.
Disclaimer: This information is for educational purposes only and does not constitute professional financial or legal advice. Auto insurance requirements and regulations vary significantly by state and municipality. Always consult with a licensed insurance agent to discuss your specific circumstances and local mandates.
Image Gallery
Select an image to open it in a new tab.

Akira Tanaka
International Academic Trends Correspondent
