
Choosing the best whole life insurance for families involves balancing permanent death benefit protection with the long-term cash value accumulation potential inherent in these policies. Unlike term life insurance, which provides coverage for a specific period, whole life insurance is a type of permanent policy designed to remain in force for the duration of the insured’s life, provided premiums are paid, while building a tax-advantaged cash reserve that families can access through loans or withdrawals.
Understanding the Mechanics of Whole Life Insurance
Whole life insurance functions as both a death benefit and a financial asset. When you purchase a policy, you agree to pay a fixed premium—often calculated based on your age, health status, and the desired death benefit amount. A portion of these premiums covers the cost of insurance and administrative fees, while the remainder is invested by the insurer into a general account.
The defining feature of whole life insurance is its guaranteed nature. Most policies offer a guaranteed death benefit, a guaranteed premium that does not increase over time, and a guaranteed cash value growth rate. Many policies sold by mutual insurance companies also offer the potential for non-guaranteed dividends. These dividends, while not promised, can be used to increase the death benefit, reduce future premiums, or be taken as cash, significantly enhancing the policy's long-term utility for a family’s financial planning.
Why Families Choose Whole Life Over Term Coverage
Families often evaluate whole life insurance when they require more than just a safety net for income replacement during their working years. While term life insurance is frequently sufficient for covering short-term debts like a mortgage or children’s education expenses, whole life provides a permanent solution for several specific family-oriented needs:
- Estate Liquidity: For families with significant assets, a whole life policy can provide the necessary liquidity to cover estate taxes or funeral expenses without the need to liquidate other family assets or property.
- Special Needs Planning: Parents of children with special needs often utilize whole life policies to fund a supplemental needs trust, ensuring that financial support remains available even after the parents are deceased.
- Supplemental Retirement Income: The cash value within a whole life policy can be accessed later in life to supplement retirement income, provided the policy is structured correctly and the policyholder does not take out loans that exceed the policy's basis, which could have tax implications.
- Legacy Building: Because the policy is permanent, it ensures that a legacy or inheritance is passed to heirs, regardless of when the insured passes away.
Evaluating Policy Features for Family Security
When comparing the best whole life insurance for families, you must look beyond the initial premium quote. The "best" policy is one that aligns with your family’s specific financial goals and the insurer's long-term stability.
The Role of Financial Strength Ratings
Since a whole life policy is a multi-decade contract, the financial strength of the insurer is paramount. Look for ratings from independent agencies such as A.M. Best, Moody’s, Standard & Poor’s, and Fitch. These agencies evaluate an insurer's ability to meet its future claims-paying obligations. For a product designed to last 30, 40, or 50 years, you should prioritize insurers with "Superior" or "Excellent" ratings.
Dividend Potential and Mutual vs. Stock Companies
Many of the most reputable whole life policies are offered by mutual insurance companies. These companies are owned by their policyholders rather than shareholders. In theory, this structure aligns the company’s interests with those of the families they insure, often resulting in more consistent dividend distributions. When comparing quotes, examine the "dividend scale" history of the insurer, noting that past performance is not a guarantee of future results.
Flexibility in Premium Payments and Withdrawals
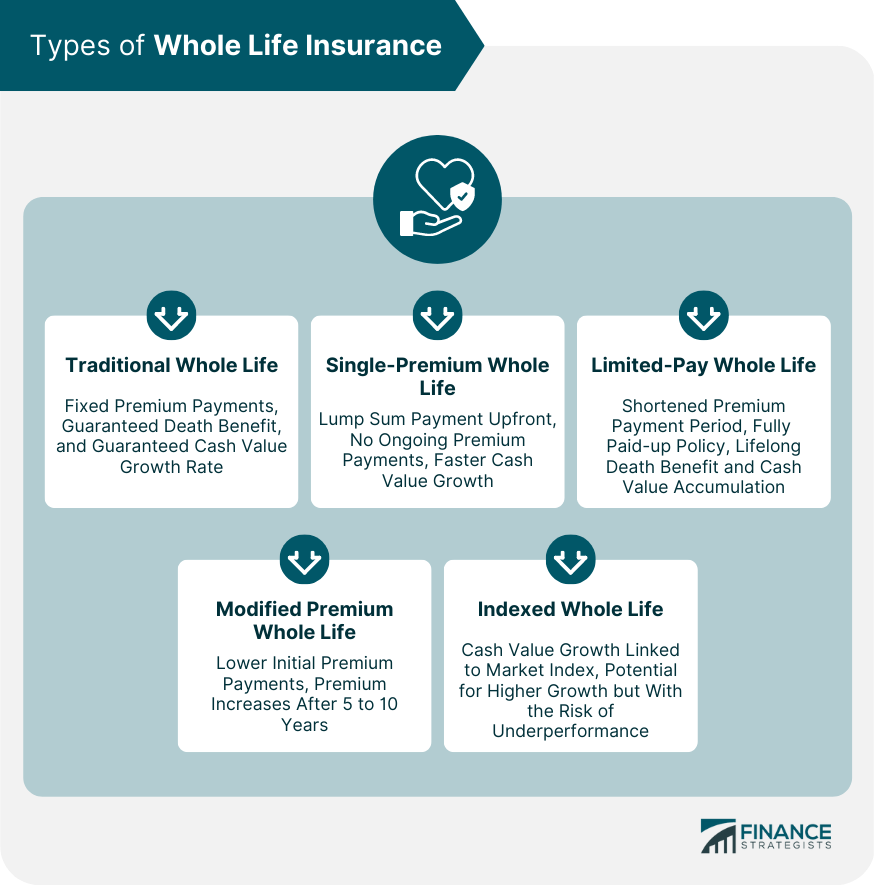
Some policies offer "limited-pay" options, where you pay higher premiums for a set number of years (e.g., 10 or 20 years) or until a certain age, after which the policy is considered "paid up." This can be an attractive feature for families who want to ensure their life insurance is fully funded before entering retirement.
Comparison of Life Insurance Structures
| Feature | Whole Life Insurance | Term Life Insurance | Universal Life Insurance |
|---|---|---|---|
| Duration | Permanent (Lifetime) | Specific Period (10-30 yrs) | Permanent (Flexible) |
| Premiums | Fixed | Fixed (for term length) | Flexible/Adjustable |
| Cash Value | Guaranteed Growth | None | Variable/Market-linked |
| Complexity | High | Low | Very High |
| Best For | Legacy & Estate Planning | Income Replacement | Flexible Planning |
Practical Steps to Securing Coverage
Before applying for a whole life policy, you should complete a thorough financial assessment.
- Determine Your Needs: Calculate how much coverage your family would need to maintain their standard of living, pay off all debts, and fund future goals like college tuition.
- Assess Budget Capacity: Because whole life insurance premiums are significantly higher than term premiums for the same death benefit amount, ensure the premium is sustainable for the long term. A lapsed policy early in its life can result in a significant loss of capital.
- Medical Underwriting: You will undergo a medical exam, which usually involves blood work and a review of your medical history. Be prepared to provide details on your family’s health history as well.
- Review the Illustration: Your agent will provide a policy "illustration." This document shows the projected growth of the cash value and the projected death benefit over the coming decades. Ask for a "non-guaranteed" vs. "guaranteed" scenario to understand the potential variance in costs and benefits.
Common Mistakes to Avoid
The most frequent error families make when purchasing whole life insurance is "over-insuring" early on, leading to a policy that becomes unaffordable during an economic downturn. It is often more prudent to start with a smaller permanent death benefit that you can realistically maintain, with the option to purchase additional coverage through "riders" or separate policies later.
Another common mistake is failing to understand the tax implications of accessing cash value. While withdrawals up to the cost basis of the policy are generally income-tax-free, loans taken against the policy can trigger tax consequences if the policy lapses. Always work with a licensed financial professional to understand the "Modified Endowment Contract" (MEC) status, which can occur if you put too much money into a policy too quickly, causing it to lose its tax-advantaged status.
Addressing Family-Specific Concerns
Families often ask whether they should insure children. While some families choose to purchase small whole life policies for children to lock in low premiums and ensure future insurability, the primary financial focus should remain on the breadwinner(s) of the family. Only after the primary earners are adequately protected should a family consider supplemental policies for other members.
Additionally, consider "riders"—optional policy enhancements. A "Waiver of Premium" rider can be essential for families, as it ensures the policy remains in force if the policyholder becomes disabled and unable to work. Similarly, an "Accidental Death Benefit" rider can provide additional protection during the years when children are most dependent.
Frequently Asked Questions
Does the cash value in a whole life policy earn interest? Yes, the cash value grows through a combination of a guaranteed interest rate set by the insurer and potential non-guaranteed dividends. These funds grow on a tax-deferred basis, meaning you do not pay income tax on the growth as it accumulates within the policy.
What happens if I cannot pay my premiums? Most whole life policies have a "grace period" for missed payments. If you continue to struggle, you may be able to use the accumulated cash value to pay the premiums (Automatic Premium Loan), reduce the death benefit to a "paid-up" status, or surrender the policy for its current cash value.
Is whole life insurance considered an investment? It is more accurately described as a financial product with a savings component. While it offers capital growth, its primary purpose is protection. Most financial advisors suggest using whole life insurance as a conservative, long-term foundation rather than a primary vehicle for aggressive market investment.
Can I change the beneficiary of my policy? Yes, the policyholder can change the beneficiary at any time, provided the policy is not structured in a way that limits this (such as an irrevocable trust). It is important to review your beneficiary designations every few years or after major life events like births, deaths, or divorces.
Are the death benefits taxable for my family? Generally, life insurance death benefits are paid to beneficiaries income-tax-free. However, if the policy is owned in a way that it becomes part of a taxable estate, or if the policy is sold during the insured's lifetime, tax implications may arise. Consult with a tax professional regarding your specific ownership structure.
Professional Guidance and Final Recommendations
The complexity of whole life insurance means that generic advice often fails to account for a family’s specific tax bracket, asset mix, and long-term goals. Before signing an application, request a "pro-forma" illustration that demonstrates how the policy would perform if dividend scales are lowered.
When interviewing insurance agents, prioritize those who act as fiduciaries or who provide a transparent view of the full market rather than those who only represent one carrier. Your goal is to secure a contract that provides peace of mind through guaranteed performance and the financial strength to survive for the next half-century. Once you have identified a reputable insurer with strong ratings and a clear illustration of costs, ensure that your premium payments are automated to avoid accidental lapses that could jeopardize your family's future security.
Image Gallery
Select an image to open it in a new tab.

Vivian Cho
Executive IT and Emerging Technologies Reporter
