Term Life Insurance for the Two Houses of Congress: A Guide to FEGLI and Benefits
Members of the U.S. House of Representatives and the U.S. Senate, along with their eligible staff, primarily access term life insurance through the Federal Employees' Group Life Insurance (FEGLI) program. This group term policy provides essential financial protection without requiring medical underwriting during initial eligibility periods, serving as a cornerstone of the federal benefits package in 2026.
The Structure of Congressional Life Insurance (FEGLI)
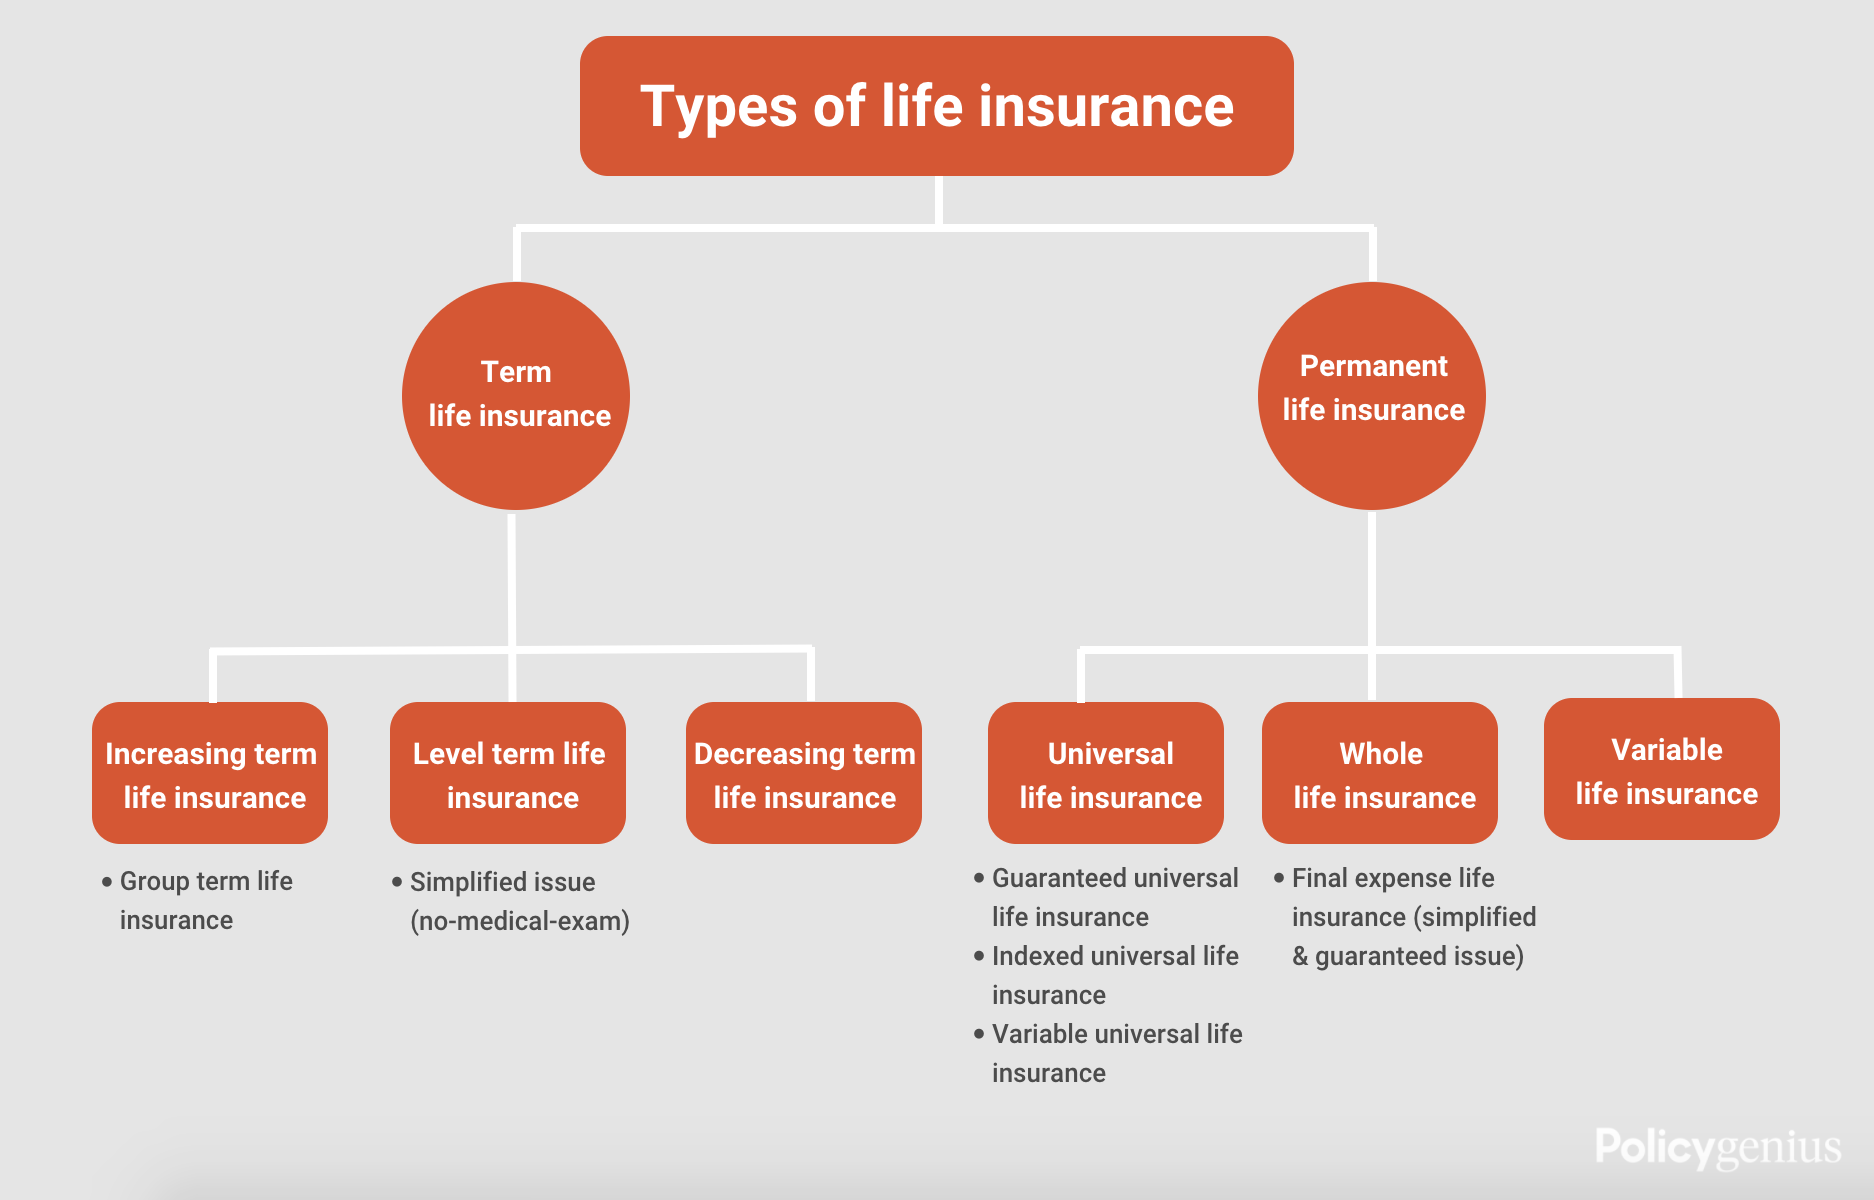
The federal government established the Federal Employees' Group Life Insurance (FEGLI) program in 1954 to provide a safety net for those serving in the legislative, executive, and judicial branches. For the "two houses of Congress"—the House of Representatives and the Senate—this program functions as the primary vehicle for term life insurance. Unlike whole life insurance, FEGLI does not build cash value; it is designed strictly to provide a death benefit to beneficiaries in the event of the insured’s passing.
In 2026, the FEGLI program remains the largest group life insurance program in the world, covering millions of federal participants. It is managed by the Office of Personnel Management (OPM), while the actual insurance is underwritten by the Metropolitan Life Insurance Company (MetLife) through the Office of Federal Employees' Group Life Insurance (OFEGLI). The structure is divided into Basic insurance and three additional options (A, B, and C), allowing members of Congress and their staff to customize their coverage levels based on their specific family needs and financial obligations.
Basic Life Insurance
Basic life insurance is the foundational coverage for members of Congress. Enrollment is automatic unless the individual specifically waives it. The coverage amount is calculated using a specific formula: the participant's annual rate of basic pay, rounded up to the nearest $1,000, plus an additional $2,000. For example, if a Member of the House earns the standard salary of $174,000, their Basic Insurance Amount (BIA) would be $174,000 rounded (already at $174,000) + $2,000, totaling $176,000.
One unique feature of the Basic insurance for younger staff members in the two houses of Congress is the "Extra Benefit." For employees under age 35, the benefit amount is doubled at no extra cost. This multiplier decreases by 10% each year until age 45, at which point the extra benefit ceases. The cost of Basic insurance is shared; the federal government pays one-third of the premium, while the individual pays the remaining two-thirds through payroll deductions.
Option A: Standard Coverage
Option A provides an additional $10,000 of coverage. While this amount may seem modest compared to modern financial needs, it serves as a legacy supplement to the Basic plan. Members of Congress who elect Option A pay the full cost of this coverage, with premiums based on age bands that increase every five years. Because this is a group term product, it remains relatively affordable for younger staffers but can become less competitive with private market rates as the individual enters senior age brackets.
Option B: Additional Coverage
Option B is often the most significant component for members of Congress who require high-value protection. This option allows the insured to choose coverage in multiples of one, two, three, four, or five times their annual basic pay. For a high-ranking official or a Senator, five times their salary provides substantial protection that scales automatically as their salary increases.
In 2026, Option B remains highly popular among congressional staff because it does not require a medical exam if elected within the first 60 days of employment. However, it is important to note that Option B premiums are "age-banded." As the insured moves into a new five-year age bracket (e.g., from 49 to 50), the cost per $1,000 of coverage increases. This can lead to significant premium hikes for long-serving members of Congress, necessitating regular reviews of whether the coverage is still cost-effective compared to private term life policies.
Option C: Family Coverage
Option C provides life insurance for the spouse and eligible dependent children of the member or staffer. The insured can choose up to five "multiples." Each multiple equals $5,000 for a spouse and $2,500 for each eligible child. Like Option B, the cost of Option C is determined by the age of the employee (not the age of the family members) and is paid entirely by the employee. This provides a streamlined way to ensure the entire household has a baseline level of protection without individual underwriting for each family member.
Eligibility and Enrollment for House and Senate Members
Eligibility for FEGLI extends to almost all permanent employees of the two houses of Congress. This includes the elected Members (Representatives and Senators) and the thousands of staffers who work in their personal offices, committee offices, and leadership offices.
Initial Enrollment Window
Upon entering service in 2026, a new member of Congress or a new staffer has a 60-day window to elect their life insurance options. During this "newly eligible" period, they are guaranteed coverage regardless of their health status. This is a critical benefit for individuals with pre-existing medical conditions who might otherwise struggle to find affordable term life insurance on the open market.
Life Event Changes
If a member of Congress initially waives coverage or wishes to increase it later, they generally must wait for a "Qualifying Life Event" (QLE). These events include marriage, divorce, the death of a spouse, or the birth/adoption of a child. Following a QLE, the individual has 60 days to enroll or increase their multiples in Option B and Option C.
Open Seasons and Medical Exams
FEGLI open seasons are exceptionally rare, occurring only a few times in the last several decades. Therefore, members of the two houses of Congress cannot rely on an annual enrollment period to update their coverage. In the absence of an open season or a QLE, an individual who wants to increase coverage must undergo a medical examination and provide evidence of insurability to OFEGLI, provided at least one year has passed since their last waiver of coverage.
2026 Premium Rates and Cost Considerations
As of 2026, the cost of FEGLI is determined by the specific type of coverage and the age of the participant. The following table outlines the structure of these costs and how they are applied to congressional salaries.
| Coverage Type | Benefit Amount | Premium Responsibility | Age-Based Increases |
|---|---|---|---|
| Basic | Salary + $2,000 | 66% Member / 33% Gov | No (Static rate per $1k) |
| Option A | $10,000 | 100% Member | Yes (Every 5 years) |
| Option B | 1x to 5x Salary | 100% Member | Yes (Significant at age 50+) |
| Option C | Family Multiples | 100% Member | Yes (Based on Member's age) |
The premiums for Basic coverage are fixed across all ages, which makes it an excellent value for older members of Congress but potentially more expensive for very young staffers compared to the private market. Conversely, Option B is very inexpensive for younger employees but increases dramatically in cost as a Senator or Representative reaches their 60s.
According to the Office of Personnel Management (OPM), the administrative costs are kept low because the program is managed centrally, and there are no commissions paid to insurance agents. This efficiency is one of the primary reasons why FEGLI remains the dominant choice for those working in the two houses of Congress.
Term Life vs. Private Market Alternatives for Congress
While FEGLI offers convenience and guaranteed issue, it is not always the most cost-effective option for every member of the two houses. Healthy individuals, particularly those in their 40s and 50s, may find that private term life insurance offers lower premiums for higher coverage amounts.
The Underwriting Factor
The primary advantage of FEGLI is the lack of medical underwriting during the initial 60 days. In contrast, a private life insurance company will require a physical exam, blood tests, and a review of medical records. For a member of Congress with a history of heart disease, diabetes, or other chronic conditions, FEGLI is almost always the superior choice.
Portability and Conversion
Private term life insurance is often portable, meaning you keep the policy as long as you pay the premiums, regardless of your employer. FEGLI is tied to federal employment. While you can carry FEGLI into retirement (if you meet the "five-year rule"), leaving the federal government for the private sector usually results in the termination of FEGLI coverage, unless you convert it to an individual permanent policy, which can be prohibitively expensive.
Tax Implications (IRS Section 79)
Under Internal Revenue Code Section 79, the value of employer-provided group term life insurance in excess of $50,000 is considered taxable income. For members of Congress whose Basic and Option B coverage often exceeds $1 million, the "imputed income" from this benefit is reported on their W-2 forms. While this is not a reason to decline coverage, it is a financial detail that congressional staff must account for during tax season in 2026.
Transitioning Coverage: Post-Term Options and Retirement
A significant concern for members of the two houses of Congress is what happens to their life insurance when they leave office or retire. The rules for "carrying" insurance into retirement are strict.
The Five-Year Rule
To continue FEGLI coverage into retirement, a congressional staffer or member must have been enrolled in the program for the five years of service immediately preceding their retirement (or for the full duration of their service if less than five years). This is why it is often advised that individuals do not cancel their FEGLI coverage late in their careers if they intend to keep it as a retiree.
Post-Retirement Reduction
Upon retirement, members of Congress can choose how they want their Basic insurance to be handled after age 65. The most common choice is the "75% Reduction," where the premium stops at age 65, and the benefit amount begins to reduce by 2% each month until it reaches 25% of its original value. Alternatively, retirees can choose a "No Reduction" or "50% Reduction" option, but these require significantly higher premiums that continue for life.
Coverage During Re-election Cycles
For Representatives and Senators, the term-based nature of their jobs adds a layer of complexity. If a member loses an election, their life insurance coverage continues for a 31-day grace period. During this time, they have the right to convert their coverage to a private policy without a medical exam, though the premiums will be based on standard individual rates, which are significantly higher than the group rates.
Common Challenges and Mistakes
One of the most frequent mistakes made by those in the two houses of Congress is failing to update beneficiary designations. FEGLI benefits are paid out according to a specific "Order of Precedence" set by federal law:
- Designated beneficiary.
- Widow or widower.
- Children and descendants of deceased children.
- Parents.
- Executor or administrator of the estate.
- Other next of kin.
If a member of Congress gets divorced but forgets to remove their former spouse as the designated beneficiary on Form SF 2823, the insurance company is legally obligated to pay the former spouse, regardless of what a will or a divorce decree might state. In 2026, keeping these records updated via the electronic portals provided by the House and Senate administrative offices is a critical task for all personnel.
Another challenge is the "all or nothing" nature of the medical exam for late enrollment. If an individual applies for coverage based on medical evidence and is denied, they may find it difficult to apply again unless a new open season is declared or they experience a qualifying life event.
FAQ
Can a member of Congress have both FEGLI and a private term life policy? Yes. Many members of the House and Senate use FEGLI as their "floor" of protection because it is convenient and guaranteed. They then supplement it with a private term life policy to lock in lower rates for larger amounts of coverage, especially if they are in good health.
Does congressional life insurance cover accidental death? The Basic FEGLI policy for employees includes Accidental Death and Dismemberment (AD&D) coverage at no additional cost. This provides double the benefit if the death is accidental. However, AD&D coverage does not carry over into retirement; it ceases the moment the member or staffer retires.
What happens to the insurance if a staffer moves from a House office to a Senate office? Because both houses of Congress are part of the federal government, FEGLI coverage is continuous. As long as there is no break in service of more than three days, the coverage levels and the five-year retirement clock remain intact. The staffer simply needs to ensure the new payroll office receives their benefit records.
Is there a "Living Benefit" for terminally ill members of Congress? Yes. FEGLI allows for a "Living Benefit" election. If a participant is diagnosed with a terminal illness and has a life expectancy of nine months or less, they can elect to receive the full value of their Basic insurance as a lump sum while still alive. This can be used to cover medical expenses or settle debts, but it eliminates the death benefit for beneficiaries.
Are the premiums for Option B the same for a Representative and a staffer? Yes. FEGLI premiums are based on the age of the individual and the amount of coverage, not their job title or rank. A 40-year-old Representative and a 40-year-old legislative assistant pay the exact same rate per $1,000 of Option B coverage.
Practical Recommendation
For those currently serving in or working for the two houses of Congress in 2026, the best approach to term life insurance is a tiered strategy. Always maintain the Basic insurance to take advantage of the government's 33% contribution. If you have dependents, maximize Option B early in your career when the age-banded premiums are lowest. However, once you reach age 50, perform an annual comparison between FEGLI Option B and a private 20-year term policy. If you are in good health, the private market may offer a fixed premium that will eventually be lower than the escalating costs of FEGLI as you age. Always ensure your SF 2823 Beneficiary Form is current and on file with the Secretary of the Senate or the Clerk of the House.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
