
The Massachusetts auto insurance landscape in 2026 is defined by managed competition, high regulatory oversight from the Division of Insurance, and a significant shift toward telematics-driven pricing. While national carriers dominate market share, regional players and independent agencies remain vital, offering specialized coverage and localized service for the Commonwealth's unique driving conditions and legal requirements.
The Evolution of the Massachusetts Insurance Market
To understand the current state of the Massachusetts auto insurance market in 2026, one must look at the transition from a state-fixed system to "managed competition." For decades, Massachusetts was unique in that the Commissioner of Insurance set uniform rates for all companies. This changed in 2008, opening the door for national carriers like GEICO and Progressive to enter the state and compete on price and service.
In 2026, this evolution has matured. The market is no longer a novelty for national giants; it is a sophisticated environment where companies use advanced data analytics to segment drivers. However, unlike some states where "Wild West" pricing occurs, the Massachusetts Division of Insurance (DOI) still maintains strict review processes for rate filings. This ensures that while companies can compete, they cannot implement predatory pricing or fluctuate rates without actuarial justification. This regulatory "safety net" provides a level of stability for consumers that is often missing in more deregulated markets.
The landscape is also shaped by the state’s high population density and complex road infrastructure. Insurers in 2026 must account for the high frequency of "fender benders" in the Greater Boston area while balancing the lower-risk profiles of drivers in the Berkshires. This geographical diversity forces companies to offer highly localized rating factors, often down to the specific ZIP code or even the street level through telematics data.
Mandatory Coverage and Legal Requirements
Massachusetts remains a "no-fault" insurance state, which is a cornerstone of its insurance landscape. This means that regardless of who is at fault in an accident, your own insurance policy’s Personal Injury Protection (PIP) typically covers your medical expenses and a portion of lost wages.
As of 2026, the mandatory minimum coverage limits in Massachusetts are:
- Bodily Injury to Others: $20,000 per person / $40,000 per accident.
- Personal Injury Protection (PIP): $8,000 per person.
- Bodily Injury Caused by an Uninsured Auto: $20,000 per person / $40,000 per accident.
- Damage to Someone Else's Property: $5,000 per accident.
While these are the legal minimums, the 2026 landscape shows a significant trend toward higher limits. Due to the rising cost of vehicle repairs—driven by advanced driver-assistance systems (ADAS) and the proliferation of electric vehicles (EVs)—the $5,000 property damage limit is widely considered inadequate. Most reputable insurers and agents now recommend a minimum of $100,000 in property damage coverage to protect against the total loss of a modern vehicle.
Furthermore, the "Safe Driver Insurance Plan" (SDIP) continues to influence the landscape. This merit-rating system rewards safe drivers with lower premiums and surcharges those with at-fault accidents or traffic violations. While companies can create their own merit-rating plans, they must be approved by the DOI, ensuring a standardized approach to assessing driver risk across the Commonwealth.

Profiles of Leading Carriers in the 2026 MA Landscape
The market is currently split between three types of entities: large national "direct" writers, established regional carriers, and tech-focused "insurtech" firms.
Mapfre Insurance (The Commerce Insurance Company)
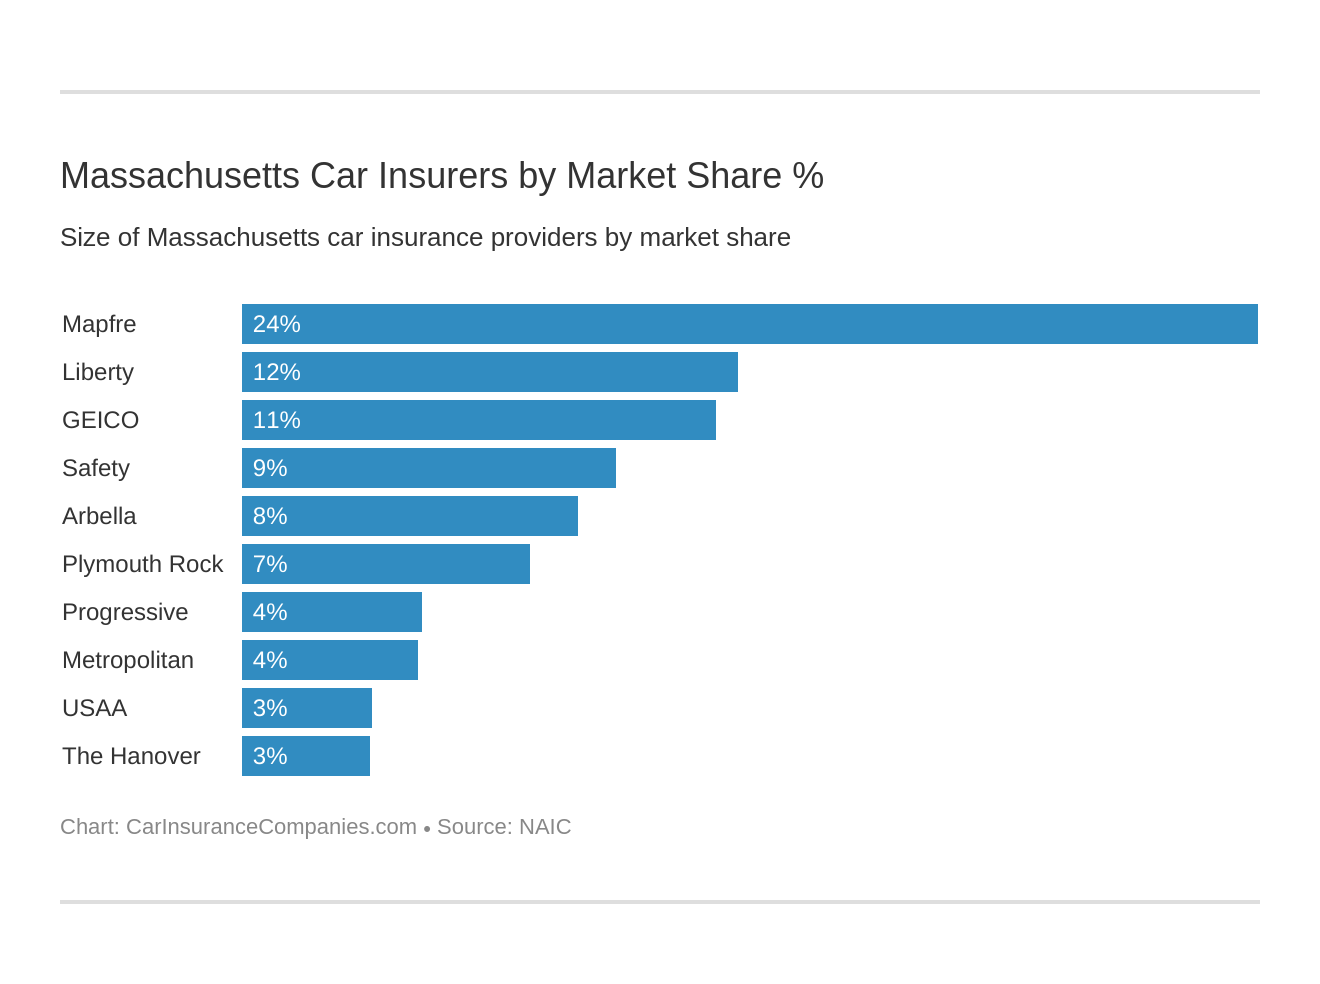
Historically the largest writer of auto insurance in Massachusetts, Mapfre maintains a dominant position through its extensive network of independent agents. In 2026, Mapfre remains a preferred choice for residents who value the "human touch" of a local agent. They have successfully modernized their back-end systems to offer competitive digital tools while preserving the agency-based model that many Massachusetts drivers prefer.
GEICO and Progressive
These national giants have solidified their presence in the state. By 2026, their aggressive marketing and high-tech mobile apps have captured a large portion of the younger demographic. They lead the market in usage-based insurance (UBI), where drivers can opt into tracking via smartphone apps or plug-in devices in exchange for significant discounts based on safe driving habits.
Liberty Mutual
Headquartered in Boston, Liberty Mutual carries a "hometown" advantage and a deep understanding of the local market. In 2026, they are particularly strong in the employer-sponsored insurance segment, offering group discounts to employees of many Massachusetts-based corporations and universities. Their "Better Car Replacement" and "Deductible Fund" features remain popular among high-value vehicle owners.
Amica Mutual
Frequently topping customer satisfaction charts, Amica operates a direct-to-consumer model without the massive advertising budgets of GEICO or Progressive. In the 2026 landscape, Amica serves as the benchmark for claims handling and customer retention. Their policyholder-owned structure often results in dividends being returned to drivers, making them highly competitive for long-term, low-risk clients.
Plymouth Rock Assurance
A regional powerhouse, Plymouth Rock is known for innovation specifically tailored to the Northeast. In 2026, their "Crashbuster" mobile units and specialized coverage for rideshare and delivery drivers make them a go-to for the modern "gig economy" worker in Massachusetts. They have leveraged local partnerships (such as those with the Boston Red Sox or New England Patriots) to maintain high brand visibility and loyalty.
Comparing Top Massachusetts Auto Insurers
The following table summarizes the key attributes of the major players in the 2026 Massachusetts market to help consumers distinguish between their offerings.
| Company | Primary Distribution | Known For | Best For | Telematics Program |
|---|---|---|---|---|
| Mapfre | Independent Agents | Local presence, agent support | Drivers wanting personal advice | DriveSafe |
| GEICO | Direct/Online | Low initial rates, easy app | Budget-conscious, tech-savvy | DriveEasy |
| Progressive | Direct & Agents | Competitive for "risky" drivers | Drivers with prior incidents | Snapshot |
| Amica | Direct/Phone | Exceptional claims service | Long-term, high-value clients | StreetSmart |
| Liberty Mutual | Direct/Agents | Affinity/Group discounts | Professionals & Boston locals | RightTrack |
| Plymouth Rock | Independent Agents | Regional expertise, gig coverage | Rideshare & delivery drivers | RoadRewards |
Key Trends Shaping the 2026 Landscape
The Massachusetts landscape is currently facing several pressures that dictate how companies operate and how much consumers pay.
The Dominance of Telematics and UBI
Usage-Based Insurance (UBI) has transitioned from an optional perk to a central pricing component. In 2026, insurers use real-time data to monitor braking, acceleration, cornering, and even phone distractions. For Massachusetts drivers, who often face heavy congestion on the Mass Pike or I-93, these programs offer a way to prove their safety despite their high-traffic environment. Companies like Progressive and GEICO now lead with these programs, often offering a "participation discount" just for signing up.
Inflation and Specialized Repair Costs
Massachusetts has some of the highest labor rates for auto repairs in the country. In 2026, the complexity of EVs and the sensors required for autonomous features have driven the average cost of a claim significantly higher. This has forced insurers to be more selective in their underwriting and has contributed to a general upward trend in premiums across the board, despite the increased safety of newer vehicles.
Climate and Infrastructure Impacts
The increasing frequency of "Nor'easters" and severe winter weather in Massachusetts has led to a spike in comprehensive claims (damage not caused by collision). Insurers are now using sophisticated climate modeling to price policies in coastal areas like Cape Cod or the North Shore, where flooding and wind damage are more prevalent. Additionally, the state's ongoing infrastructure projects (the "Big Dig" legacy and bridge repairs) contribute to high accident rates in construction zones, which insurers track closely.
How to Choose an Insurer in the Current Market
Navigating the 2026 landscape requires a multi-step approach. Because Massachusetts is a managed competition state, the "best" company for one driver may be the most expensive for another.
- Verify Financial Stability: Use ratings from AM Best or Demotech. Even in 2026, the financial health of an insurer is critical to ensuring they can pay out large claims during a catastrophic weather event.
- Evaluate the SDIP Impact: If you have points on your license, look for companies that offer "vanishing deductibles" or accident forgiveness. Some carriers are more "forgiving" of a single minor infraction than others.
- Bundle for Savings: The "multi-policy" discount remains the most effective way to lower premiums in Massachusetts. Combining auto with homeowners, renters, or umbrella insurance can save between 10% and 25%.
- Review the Agent vs. Direct Choice: If you have a complex situation (e.g., teen drivers, a business vehicle, or a classic car), an independent agent who can shop multiple carriers like Mapfre, Plymouth Rock, and Travelers is often better than going direct to a single company.
Common Pitfalls and Troubleshooting
The most common mistake Massachusetts drivers make in 2026 is under-insuring for property damage. With the average price of a new car in the Commonwealth exceeding $50,000, the $5,000 state minimum is a significant liability risk. If you hit a luxury vehicle or cause a multi-car pileup, you could be personally liable for the difference.
Another issue involves the "Step-Down" provision. Some lower-cost insurers include clauses that reduce your coverage to the state minimums if an unlisted driver (someone living in your house not on the policy) is behind the wheel. It is essential to ensure every licensed driver in your household is properly disclosed to avoid a coverage gap.
Frequently Asked Questions
Is Massachusetts a no-fault state in 2026?
Yes, Massachusetts remains a no-fault state. This means your own insurance company pays for your medical bills and lost wages up to $8,000 through Personal Injury Protection (PIP), regardless of who caused the accident. This system is designed to reduce the number of small-claims lawsuits for minor injuries.
Can I get insurance in MA with a bad driving record?
Yes, but it will be significantly more expensive. Massachusetts has a "residual market" known as the Massachusetts Automobile Insurance Plan (MAIP). If you are unable to find coverage in the voluntary market because you are considered too high-risk, MAIP ensures that you can still obtain the legal minimum coverage by assigning you to an insurance company.
Does my credit score affect my insurance rate in Massachusetts?
No. Massachusetts is one of the few states that prohibits insurance companies from using credit scores to determine auto insurance premiums. Your rate is based on your driving history, years of experience, location, and the type of vehicle you drive, but not your financial creditworthiness.
What is the "Safe Driver Insurance Plan" (SDIP) in 2026?
The SDIP is a point-based system used to track your driving history over a rolling six-year period. Points are assigned for traffic violations and at-fault accidents. A "clean" record results in a "99" rating, which qualifies you for the best rates, while accumulated points lead to surcharges on your premium.
Is telematics mandatory for Massachusetts drivers?
While not legally mandatory by the state, many insurance companies in 2026 have made telematics a core part of their pricing strategy. You can still find policies without tracking, but you may miss out on the most competitive rates, as insurers increasingly use this data to identify and reward their lowest-risk customers.
Recommended Next Action
To ensure you are getting the best value in the 2026 Massachusetts auto insurance landscape, you should perform a "comprehensive quote audit" every two years. Start by contacting an independent agent to check regional carriers like Mapfre and Plymouth Rock, and then spend 15 minutes obtaining a direct quote from a national carrier like GEICO or Amica. This dual approach ensures you capture both the localized discounts and the national competitive pricing available in the Commonwealth.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
