Lakeside Auto Insurance Options for Drivers: Coverage Types, Costs, and Regional Risk Factors
Drivers residing in or frequently traveling through lakeside communities face a distinct combination of environment-specific hazards and standard roadway risks. Securing appropriate lakeside auto insurance options requires balancing compulsory state liability requirements with comprehensive protection for flood hazards, lake-effect weather, vehicle corrosion, and specialized equipment such as boat trailers. Evaluating customized coverage tiers, regional rate factors, and multi-policy discounts allows motorists along waterfront routes to protect their vehicles and personal finances effectively.
Understanding Auto Insurance Requirements and Local Risk Profiles
Auto insurance policies operate under a framework of state-mandated legal minimums, but relying solely on basic legal coverage often leaves drivers near waterfront environments exposed to severe out-of-pocket losses. State mandatory minimums typically cover third-party bodily injury liability and third-party property damage liability. However, these baseline limits do not pay for damage to the policyholder's own vehicle caused by natural hazards, weather events, or single-vehicle accidents common near shorelines.
Living or driving near major lakes, reservoirs, or coastal basins introduces specific environmental risk profiles that standard insurance policies must be structured to handle:
- Localized Flooding and Water Rise: Lakeshore areas are particularly susceptible to flash flooding, rising water tables, and lake overflow caused by heavy rain or rapid spring snowmelt. Water entering the engine compartment or cabin can instantly cause catastrophic mechanical and electrical damage.
- Lake-Effect Weather Patterns: Proximity to large bodies of water often creates localized microclimates. Drivers encounter sudden fog, severe hail, torrential downpours, high shoreline wind gusts, and intense lake-effect snowstorms that increase collision frequency and vehicle damage.
- Corrosion and Moisture Exposure: Constant high humidity, damp air, and standing moisture near shorelines accelerate rust on frame components, braking systems, and electrical wiring. In northern regions, winter salt applications combined with lake moisture exacerbate undercarriage wear.
- Terrain Hazards and Wildlife: Shoreline access roads are frequently narrow, winding, unpaved, or heavily forested. Drivers face an elevated risk of striking falling tree limbs, loose gravel, or wildlife such as deer and waterfowl that frequent riparian habitats.
Evaluating these environmental variables is the first step in constructing an auto insurance portfolio that addresses both legal compliance and practical risk management.
Core Auto Insurance Options for Drivers Near Lakes
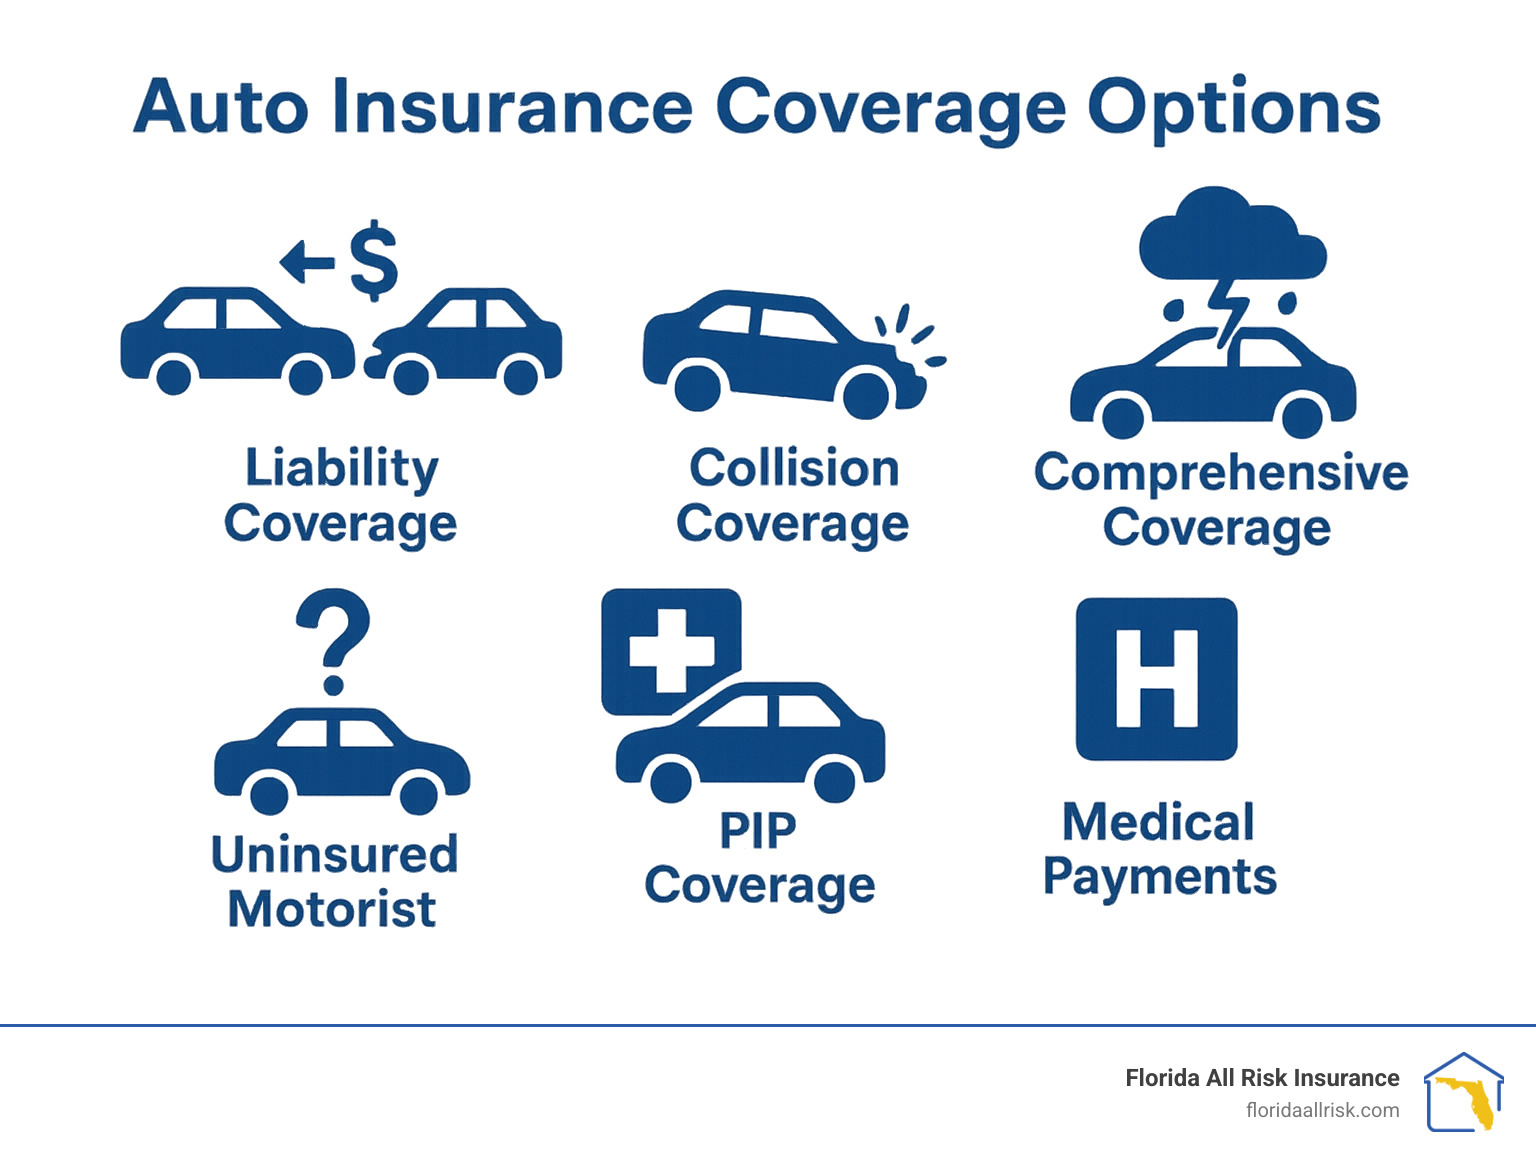
To achieve robust protection, drivers in lakeside regions must look beyond compulsory liability insurance and incorporate physical damage protections and first-party coverage options into their policy declarations.
- Lakeside Vehicle Risk Profile
- Environmental Risks
- Rising Lakes
- Severe Storms
- Humidity/Rust
- Falling Trees
- Comprehensive Coverage
- Roadway & Terrain Risks
- Narrow Roads
- Winding Turns
- Lake-Effect Ice
- Wildlife Cross
- Collision Coverage
- Towing & Utility Risks
- Boat Launching
- Ramp Slippage
- Unhitched Trailer Damage
- Endorsements & Roadside Tows
- Environmental Risks
Comprehensive Coverage (Acts of Nature and Environmental Damage)
Comprehensive insurance is non-collision physical damage coverage. It protects against events outside the driver's operational control, making it essential for waterfront vehicle owners.
Comprehensive policies cover claims resulting from:
- Submersion or water damage due to rising lake levels or storm surges.
- Falling tree branches, pine cones, or heavy debris dislodged by windstorms.
- Windshield chipping or cracking caused by gravel kicked up on unpaved shoreline access routes.
- Vandalism or theft, which can spike in seasonal tourist destinations during off-peak months.
- Direct collisions with animals, such as deer or large waterfowl crossing lakeside highways.
Collision Coverage
Collision insurance pays to repair or replace the policyholder's vehicle if it strikes another automobile, an object, or flips over, regardless of fault. Near lakes, common collision scenarios include sliding off icy, moisture-slicked roads into ditches, striking retaining walls or docks, or slipping backward on wet, algae-covered boat launch ramps. If a vehicle is financed or leased, the lender will mandate both comprehensive and collision insurance until the loan is fully satisfied.
Uninsured and Underinsured Motorist (UM/UIM) Protection
Lakeside regions often draw high volumes of seasonal vacationers, weekend boaters, and out-of-state drivers. A notable percentage of motorists on the road may carry only minimum state liability limits or operate vehicles without valid insurance. If an uninsured or underinsured driver causes a severe collision, UM/UIM coverage steps in to pay for bodily injuries, lost wages, and in some jurisdictions, property damage to the insured driver and passengers.
Medical Payments (MedPay) and Personal Injury Protection (PIP)
First-party medical coverage pays for immediate medical expenses, hospital visits, and emergency transport for the driver and passengers after an accident, regardless of who caused the collision. In states with no-fault insurance frameworks, PIP is mandatory and can cover broader costs including lost income and rehabilitation.

Specialized Endorsements and Add-Ons for Lakeside Motorists
Standard auto policies exclude several specialized scenarios common to lake life. Motorists who tow recreational equipment, navigate remote backroads, or drive customized vehicles should evaluate supplemental endorsements.
Roadside Assistance and Winch-Out Coverage
Basic roadside assistance typically covers battery jump-starts, tire changes, and fuel delivery. However, drivers near lakes should verify whether their plan includes extended towing limits and specialized winch-out services. If a car or SUV becomes stuck in loose mud, soft shoreline sand, or on a slippery boat ramp, standard towing endorsements may not cover the cost of extraction unless specific winch-out language is included in the policy.
Boat and Utility Trailer Coverage Mechanics
A frequent point of confusion for lakeside drivers is how auto insurance interacts with towed trailers (such as boat trailers, jet ski trailers, or utility haulers).
- Liability Transfer: When a trailer is physically hitched to an insured vehicle, the towing vehicle’s auto liability insurance extends to cover third-party property damage or injuries caused by the trailer while in transit.
- Physical Damage Exclusions: The auto policy does not automatically cover physical damage to the trailer itself if it flips, detaches, or is damaged in a crash. Protecting the trailer's hull or structural frame requires either a specific trailer endorsement on the auto policy or dedicated physical damage coverage under a marine/watercraft insurance policy.
- Unhitched State: Once a trailer is unhitched from the vehicle at a campsite, driveway, or launch dock, auto liability coverage ceases. Separate trailer or watercraft insurance is required for liability protection while unhitched.
Custom Parts and Equipment (CPE) Endorsements
Trucks and SUVs configured for lakeside activities often feature aftermarket upgrades, including suspension lift kits, heavy-duty winches, roof racks for kayaks, custom hitches, or auxiliary lighting. Standard auto policies base payouts on factory equipment. Adding a CPE endorsement ensures that non-factory equipment is fully valued and reimbursed if damaged or stolen.
Evaluating Insurance Rates and Regional Pricing Factors
Insurance companies determine policy premiums by analyzing statistical risk matrices linked to geographic location, vehicle specifications, and individual driver characteristics.
| Geographic & Environmental Factors | Driving Record & Usage Profiles |
|---|---|
| • Zip code flood risk indices• Proximity to body of water• Seasonal traffic density | • Annual mileage driven• Telemetry / Driving habits• Claims history & credit tier |
| Vehicle Characteristics | Policy Structure Choices |
| • 4WD/AWD drivetrain availability• Modern safety & telemetry tech• Anti-corrosion design elements | • Selected liability limits• Comprehensive/Collision deducts• Optional endorsements added |
Zip Code Risk and Flood Mapping
Insurers evaluate historical loss data tied to specific zip codes. Living in close proximity to a lake can influence comprehensive rates if that area historically experiences high claims volumes related to flash flooding, severe wind damage, or winter storm accidents. Areas designated as high-risk flood zones by municipal authorities or federal agencies may see elevated baseline costs for comprehensive protection.
Vehicle Drivetrain and Usage Patterns
Vehicles equipped with All-Wheel Drive (AWD) or Four-Wheel Drive (4WD) are frequently preferred in lakeside environments for navigating slippery ramps and snow-covered terrain. While AWD/4WD systems enhance traction, vehicles equipped with these drivetrains often incur slightly higher repair costs after a mechanical or structural failure, which can marginally increase collision premiums.
Additionally, usage patterns affect rates: a vehicle driven daily along winding shorelines will incur different pricing than a secondary vehicle driven only during summer weekends.
Annual Mileage and Seasonal Storage
Drivers who maintain secondary vehicles strictly for seasonal lake access can reduce costs by reporting accurate annual mileage. When a vehicle is kept in secure garage storage during off-season winter months, policyholders can inquire about seasonal storage modifications—sometimes referred to as lay-up policies—which temporarily remove collision coverage while preserving comprehensive coverage against fire, theft, and falling debris.
Comparison of Insurance Coverage Tiers for Lakeside Drivers
The table below outlines common auto insurance policy components, detailing how each addresses specific risks encountered in lakeside environments, along with typical recommended limits.
| Coverage Type | Primary Protection Focus | Lakeside Risk Addressed | Optional vs. Mandatory | Recommended Limit / Consideration |
|---|---|---|---|---|
| Bodily Injury Liability | Third-party injuries caused by policyholder | Collisions on narrow waterfront roads or near pedestrian docks | Mandatory by state law | $100,000 per person / $300,000 per accident minimum |
| Property Damage Liability | Third-party physical property damage | Striking parked watercraft, docks, guardrails, or structural fences | Mandatory by state law | $100,000 minimum limit |
| Comprehensive Coverage | Non-collision vehicle damage | Rising lake water, flooding, falling tree limbs, hail, deer strikes | Optional (Mandatory for active auto loans) | Low deductible ($250–$500) due to high environmental risks |
| Collision Coverage | Vehicle impact with objects or cars | Slipping on launch ramps, rollover on unpaved roads, single-vehicle slides | Optional (Mandatory for active auto loans) | $500–$1,000 deductible managed against personal emergency funds |
| Uninsured/Underinsured Motorist | Injuries/damage caused by underinsured third parties | Accidents with transient, out-of-state, or uninsured seasonal visitors | Mandatory in some states; optional in others | Match selected Bodily Injury Liability limits |
| Roadside Assistance & Towing | Emergency breakdown and towing | Vehicles stranded on muddy access trails or slipping into boat ramps | Optional endorsement | Ensure policy includes winch-out services and 50+ miles of towing |
| Trailer Physical Damage | Structural damage to towed equipment | Jackknifing, highway roll-overs, or detachment of boat trailers | Optional endorsement / Separate policy | Stated Value or Actual Cash Value of the trailer |
Strategies to Lower Auto Insurance Premiums in Lakeside Areas
High coverage levels do not necessarily require exorbitant premiums. Motorists can apply strategic cost-reduction techniques to manage insurance expenses effectively.
Multi-Policy Bundling
One of the most effective ways to lower rates is placing multiple insurance products with a single carrier. Combining auto coverage with home, renters, condo, or personal watercraft (boat/PWC) policies often yields multi-policy discounts ranging from 10% to 25% across all linked accounts.
Usage-Based Telematics Programs
Many national and regional insurance carriers offer usage-based insurance (UBI) programs. These telematics platforms track driving behaviors—such as braking intensity, cornering speeds, acceleration rates, and time of day—via smartphone applications or OBD-II port devices. Drivers who navigate calm lakeside routes smoothly and avoid late-night driving can unlock substantial policy discounts.
Strategic Deductible Management
Selecting higher deductibles on comprehensive and collision coverage directly lowers recurring premium payments. However, policyholders should calculate their out-of-pocket exposure. If a vehicle resides in a high-risk flood or windstorm zone, setting a comprehensive deductible too high ($1,500+) could create financial strain if an environmental claim occurs. A balanced approach involves maintaining a moderate comprehensive deductible ($250 to $500) while opting for a slightly higher collision deductible ($1,000) if personal emergency reserves permit.
Defensive Driving Courses
Completing an accredited defensive driving course—approved by state motor vehicle departments or national safety organizations—can reduce liability and collision premiums for up to three years. This option is particularly beneficial for mature drivers and young operators exposed to seasonal traffic surges.
Handling Claims for Flood, Water, and Shoreline Accidents
Filing a vehicle claim involving water or severe weather requires specific documentation and rapid response to mitigate secondary damage.
- Vehicle Water Exposure Event Occurs
- DO NOT Attempt to Start the Engine (Prevents Hydro-locking)
- Document Scene & Water Levels (Take Photos/Videos of High Water Mark)
- Contact Insurance Carrier Immediately (Initiate Claim & Request Tow)
- Towed to Certified Facility (Inspect Mechanical & Electrical Modules)
- Claims Adjuster Evaluation
- Repairable Damage
- Drain/flush fluids
- Harness decontamination
- Interior drying/sanitizing
- Total Loss Threshold Met
- Water reached dash/ECU
- Valuation & payout processed
- Repairable Damage
Steps to Take Following Water Immersion
- Do Not Attempt to Start the Engine: If a vehicle has been partially submerged in lake water or caught in rising floodwaters, attempting to start the ignition can draw water directly into the engine cylinders, causing immediate internal destruction known as hydro-locking.
- Document the Scene and Water Line: Photograph the vehicle in place if safe to do so. Capture clear images showing the high-water line on the exterior doors, tires, and interior cabin.
- Notify the Carrier Promptly: Contact the insurance company's claims department to report the incident. Explicitly state whether the water was standing, rising, or if the vehicle slid off an embankment or launch ramp.
- Mitigate Secondary Mold and Corrosion: Once towed to a certified repair shop, request immediate disconnect of the main battery to prevent short-circuiting sensitive electronic control units (ECUs).
Understanding Total Loss Thresholds for Water Damage
Modern vehicles contain extensive electronic architecture, including harness connectors, air-bag sensors, and computers situated beneath seat tracks and floorboards. When fresh or brackish lake water penetrates the floorboards and reaches electrical modules, insurance adjusters frequently declare the vehicle a total loss.
State regulations dictate total loss thresholds (often when repair costs exceed 70% to 80% of the vehicle’s Actual Cash Value). Water damage claims frequently hit this threshold due to long-term reliability risks associated with internal wiring corrosion.
Frequently Asked Questions
Does standard auto insurance cover damage if my car gets flooded near a lake?
Yes, provided you carry comprehensive coverage on your policy. Comprehensive insurance covers physical damage resulting from non-collision environmental events, including flash floods, rising lake waters, and severe storm surges. Standard state-minimum liability policies do not cover flood damage to your own vehicle.
How does towing a boat trailer affect my car insurance policy?
When a trailer is properly hitched to your vehicle, your auto policy’s liability coverage extends to cover third-party property damage or injuries caused by the trailer while driving. However, auto liability does not cover physical damage to the trailer itself or the boat it carries. Physical protection for the trailer requires a trailer endorsement on your auto policy or dedicated coverage under a marine policy.
What happens if my car slips on a boat ramp and slides into the lake?
If your vehicle slips on a wet or algae-covered ramp and slides into the water, the claim is typically processed under collision coverage if the vehicle struck the ramp structure or slid during operation, or under comprehensive coverage depending on the specific policy language and adjuster assessment. Financing lenders require both coverages to protect against this risk.
Are insurance rates higher for drivers living directly on a lakefront?
Rates are primarily determined by zip code data, claims frequency, local weather trends, and flood risk mapping rather than shoreline distance alone. However, if your specific address falls within a designated high-risk flood zone or an area with a history of severe weather claims, comprehensive premiums may be slightly higher than in adjacent inland neighborhoods.
Does roadside assistance cover extracting a car stuck in mud or sand near the shore?
Standard roadside assistance covers towing on paved roads. To cover a vehicle stuck in soft sand, mud, or unpaved shoreline access paths, your policy must include winch-out coverage. Verify the distance and terrain limitations of your roadside endorsement to ensure adequate coverage near water access areas.
Can I drop collision coverage on a seasonal vehicle during the winter months?
Yes. If a vehicle is kept in secure indoor storage for the winter, you can convert the policy to a lay-up or seasonal storage policy. This temporarily suspends collision and liability coverage to reduce premiums while keeping comprehensive coverage active to protect against fire, theft, vandalism, or building structural damage.
Final Guidance and Actionable Next Steps
Managing auto insurance in a lakeside community requires aligned policy limits and proactive environmental protection. Review your current auto insurance policy declarations page to confirm that comprehensive physical damage coverage, adequate liability limits, and necessary roadside endorsements are fully active.
Drivers should evaluate their coverage strategy by following these concrete steps:
- Audit Physical Damage Deductibles: Review your comprehensive deductible against your emergency savings. Ensure it is low enough to be manageable if seasonal flooding or storm damage occurs.
- Verify Towing and Winch-Out Limits: Check your roadside assistance details to confirm that winching services are included for soft ground or boat launch recovery, and ensure towing distance limits are sufficient for rural routes.
- Confirm Trailer and Accessory Coverage: If you tow boats, jet skis, or utility haulers, confirm whether your auto policy covers physical trailer damage or if a supplemental marine endorsement is required.
- Explore Multi-Policy Bundling: Contact your insurance agent or carrier to review potential discounts from bundling auto, homeowners, renters, and watercraft policies under a single umbrella.
Taking these steps ensures full legal compliance, robust financial protection against regional environmental hazards, and seamless coverage wherever waterfront roads lead.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
