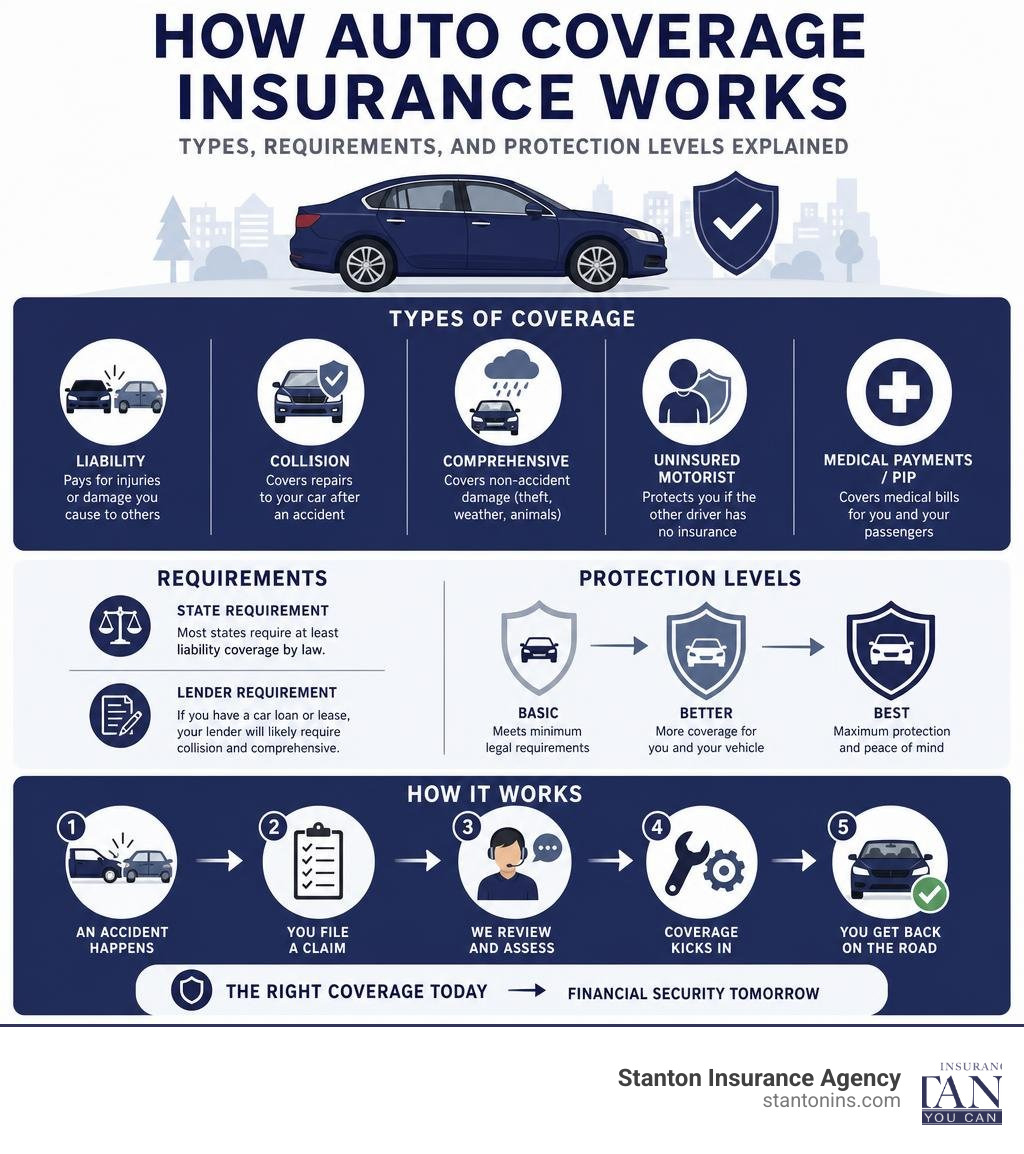
The Infinite Auto Insurance continuous coverage model is a perpetual policy structure designed to eliminate traditional expiration dates and renewal cycles. By integrating real-time telematics and automated subscription billing, this model ensures that drivers maintain an uninterrupted insurance history, effectively preventing "coverage gaps" that typically lead to higher premiums, legal penalties, and the loss of preferred risk status.
The Evolution of the Continuous Coverage Model
In the 2026 insurance landscape, the "Infinite" model represents a significant departure from the legacy system of six-month or annual terms. For decades, the auto insurance industry relied on fixed-term contracts. Under those older systems, a driver would purchase a policy, pay a premium for a set period, and then undergo a manual or semi-automated renewal process. If a payment was missed or a renewal notice ignored, the policy would lapse.
A lapse in coverage, even for as little as twenty-four hours, carries heavy consequences. Actuarially, individuals with gaps in their insurance history are categorized as higher risk. Consequently, when they re-apply for insurance, they are often relegated to "non-standard" carriers with significantly higher rates. The Infinite Auto Insurance model addresses this structural flaw by transitioning the policy into a permanent, "always-on" utility, much like a cellular data plan or a software subscription.
This model is predicated on the concept of Perpetual Underwriting. Instead of evaluating a driver’s risk once every six months, the insurer uses real-time data to adjust the policy conditions and pricing incrementally. This prevents the "renewal shock" often seen in legacy models, where a driver is suddenly hit with a massive premium increase at the end of a term due to market shifts or minor incidents.
Technical Mechanics: How the Infinite Model Operates
The Infinite Auto Insurance continuous coverage model functions through three primary technical pillars: Integrated Telematics, Automated Financial Synchronization, and Dynamic Risk Adjustment. Understanding these components is essential for any policyholder looking to leverage the model for long-term savings.
1. Integrated Telematics and OEM Connectivity
By 2026, most vehicles are equipped with native "connected car" technology. The Infinite model hooks directly into the vehicle’s original equipment manufacturer (OEM) interface or a secondary OBD-II device. This connection transmits data points such as:
- Total mileage driven: Allowing for pay-per-mile cost scaling.
- Hard braking and acceleration events: Creating a real-time safety score.
- Time of day usage: Identifying high-risk late-night driving patterns.
- Geographic location: Adjusting for localized risk factors like theft rates or weather-related accident frequency.
2. Automated Financial Synchronization
To maintain "continuous" status, the model utilizes a "fail-safe" billing system. Unlike traditional monthly bills that might result in immediate cancellation upon a single missed payment, the Infinite model typically incorporates a grace-period buffer or a secondary payment method requirement. This ensures that the policy remains "in force" legally, even if there is a temporary disruption in the primary payment method, thereby protecting the driver’s continuous coverage history.
3. Dynamic Risk Adjustment
In the Infinite model, premiums are not static. They are adjusted in a "rolling" fashion. If a driver’s safety score improves over a thirty-day period, the following month’s premium may decrease automatically. Conversely, if the vehicle is moved to a more hazardous zip code, the rate adjusts in real-time. This transparency allows the driver to see the direct financial impact of their behaviors without waiting for a semi-annual renewal.
Comparison: Infinite Continuous Model vs. Traditional Term Insurance
The following table highlights the operational differences between the Infinite continuous model and the legacy term-based insurance models still found in some segments of the market.
| Feature | Legacy Term Insurance | Infinite Continuous Model |
|---|---|---|
| Contract Duration | Fixed (6 or 12 months) | Perpetual (No expiration) |
| Renewal Process | Manual or semi-auto re-underwriting | Automated dynamic adjustment |
| Pricing Structure | Static for the duration of the term | Dynamic based on real-time behavior |
| Lapse Risk | High (occurs at end of term/non-payment) | Low (fail-safe billing & subscription) |
| Data Usage | Historical (past 3-5 years) | Real-time (current month + history) |
| Transparency | Low (reason for increases often vague) | High (direct link between behavior/cost) |
| Premium Payments | Lump sum or monthly installments | Subscription-based / Usage-based |
The "Continuous Coverage Credit" and Its Financial Impact
One of the most compelling reasons to utilize the Infinite model is the preservation of the Continuous Coverage Credit. In the insurance industry, "continuity" is a proxy for responsibility and financial stability.
When a driver maintains coverage without a gap for three, five, or ten years, they move into the "Preferred" or "Ultra-Preferred" underwriting tiers. According to the Insurance Information Institute, drivers with a continuous coverage history of at least five years pay an average of 35% less than those with a 30-day lapse in their recent history.
The Infinite model automates the maintenance of this credit. Because there is no "end date" to the policy, the "clock" for continuous coverage never resets. This is particularly vital in states like California and Florida, where regulatory environments heavily reward long-term policyholders through "loyalty" mandates or standardized risk-rating steps.
Legal and Regulatory Considerations
While the Infinite Auto Insurance model offers convenience, it must still comply with state-specific mandates regarding "Proof of Financial Responsibility."
State Reporting and SR-22/FR-44
For drivers who require high-risk filings (such as SR-22s), the continuous coverage model is a safeguard. In many jurisdictions, if a high-risk policy lapses for even one day, the insurer is legally required to notify the Department of Motor Vehicles (DMV), which can lead to immediate license suspension. The "infinite" nature of this model prevents these accidental notifications by ensuring the filing stays active as long as the subscription is maintained.
Data Privacy and Telematics
A significant hurdle for the continuous coverage model involves data privacy laws, such as the California Privacy Rights Act (CPRA). Because the model relies on constant data streams from the vehicle, insurers must provide clear disclosures about what data is being collected and how it affects the rate. Drivers have the right to request a "data audit" to see exactly which driving events triggered a premium increase.
Prerequisites and Eligibility
To enroll in an Infinite Auto Insurance continuous coverage plan in 2026, certain requirements must be met:
- Vehicle Compatibility: The vehicle must have an active telematics link (usually model year 2018 or newer) or be compatible with a third-party sensor.
- Digital Payment Infrastructure: Users must maintain a verified digital payment method (credit card, bank link, or digital wallet) to support the perpetual billing cycle.
- Consent to Real-Time Underwriting: Drivers must agree to the "Dynamic Pricing" disclosure, acknowledging that their rates can change monthly based on behavior and mileage.
- Jurisdictional Availability: While expanding, some states with rigid "prior approval" rate laws may have limited versions of the Infinite model that only adjust pricing every 90 days rather than in real-time.
Potential Drawbacks: What Drivers Should Watch Out For
Despite the benefits of continuity, the Infinite model is not without its challenges.
- Premium Volatility: For inconsistent drivers, the monthly premium can fluctuate significantly. A single long-distance road trip or a week of heavy traffic commuting can cause a spike in the following month's cost.
- The "Privacy Tax": Those who are uncomfortable with 24/7 location and behavior tracking may find themselves excluded from the best rates offered by the Infinite model.
- Automated Complacency: Because the policy never expires, some drivers may forget to "shop around." While the model rewards continuity, it does not always guarantee the lowest possible market rate if other carriers introduce new competitive products.
Troubleshooting Common Issues in the Continuous Model
Problem: The vehicle’s telematics unit stops sending data.
- Solution: Most Infinite policies include a "Default Risk Rate." If data is lost (e.g., a hardware failure), the insurer will charge a standard rate based on your last 60 days of average driving until the connection is restored. You should contact support immediately to avoid being moved to a "non-usage" high-rate tier.
Problem: Changing vehicles while maintaining continuity.
- Solution: The Infinite model is designed for "seamless migration." You can typically add a new vehicle to the "Infinite" stream via a mobile app. The coverage for the old vehicle is terminated only after the new vehicle’s telematics link is verified, ensuring there is never a second where you are uninsured during the transition.
Problem: Dealing with a declined payment.
- Solution: Most continuous models utilize a "Status Hold." If a payment fails, the policy enters a 10-to-15-day grace period where coverage remains active. During this time, the insurer will send multiple digital alerts. Resolving the payment within this window is critical to preventing a formal "Notice of Cancellation" (NOC) from being generated.
Frequently Asked Questions
Does the Infinite model replace the need for a renewal notice?
Yes, in its purest form, the Infinite model removes the "renewal" event entirely. However, insurers are still legally required in most states to provide a "Periodic Statement of Coverage" every six to twelve months. This document summarizes your premiums paid and confirms your active status, but it does not require you to take action to keep the policy active.
Can I cancel an Infinite continuous policy at any time?
Yes. Just because the model is "infinite" does not mean it is a "lock-in" contract. Most providers allow for mid-month cancellation. Because it is subscription-based, you are typically refunded a pro-rated amount for the remaining days in the billing cycle, or the policy simply terminates at the end of the current month.
How does this model affect my "Insurance Score"?
Your insurance score is heavily influenced by your history of maintaining coverage. By using the Infinite model to prevent lapses, your insurance score generally improves over time. This makes you more attractive not only to your current insurer but also to lenders for auto and home loans.
Is the Infinite model more expensive for high-risk drivers?
Initially, yes. High-risk drivers may start with a higher "base subscription." However, the model provides a faster "path to redemption." In legacy models, a driver has to wait six months to show they’ve improved. In the Infinite model, safe driving behavior over 30 days can result in an immediate downward rate adjustment.
Strategic Recommendation
For drivers in 2026, the Infinite Auto Insurance continuous coverage model is highly recommended for those who prioritize long-term financial stability over the lowest possible "introductory" rate. To maximize the value of this model, drivers should ensure their vehicle's telematics are functioning correctly and maintain a dedicated "buffer" in the account linked to the policy to avoid payment disruptions.
By embracing this model, you effectively "insulate" your insurance history from the volatility of manual renewals and the punitive costs of coverage gaps. If you value a "set-and-forget" approach to financial responsibility, transitioning to a perpetual, continuous coverage framework is the most logical step in modern vehicle management.
Image Gallery
Select an image to open it in a new tab.



Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
