The IRS energy credit framework functions as a primary catalyst for the global energy transition by drastically reducing the net capital cost of clean energy projects. Through mechanisms like the Investment Tax Credit (ITC) and Production Tax Credit (PTC), these incentives provide long-term financial certainty, enabling institutional investors and developers to achieve viable internal rates of return on renewable infrastructure.
As of 2026, the landscape of federal energy incentives has matured significantly. The Internal Revenue Service (IRS) no longer simply manages niche rebates; it oversees a comprehensive suite of "technology-neutral" credits that have fundamentally altered how corporations, utilities, and even non-profits approach energy procurement and asset management. By moving away from short-term legislative extensions toward a decade-long horizon, the IRS has effectively institutionalized clean energy as a core asset class for American capital.
The Shift to Technology-Neutral Credits (Sections 45Y and 48E)
For decades, energy tax policy was a patchwork of specific incentives for wind and solar that required frequent renewals. In 2026, we are operating under the "technology-neutral" regime established by the Inflation Reduction Act (IRA). These credits, specifically the Clean Electricity Production Credit (Section 45Y) and the Clean Electricity Investment Credit (Section 48E), have replaced the legacy Section 45 and Section 48 credits for projects placed in service after December 31, 2024.
The "technology-neutral" approach means the IRS does not care how you generate clean electricity—whether through advanced solar, modular nuclear, geothermal, or even zero-emission combustion—as long as the greenhouse gas emissions rate is zero or lower. This shift has unlocked investment in emerging technologies that previously struggled to find a specific legislative "home."
Investment Tax Credit (ITC) vs. Production Tax Credit (PTC)
Choosing between an ITC and a PTC remains the most critical decision for a project developer.
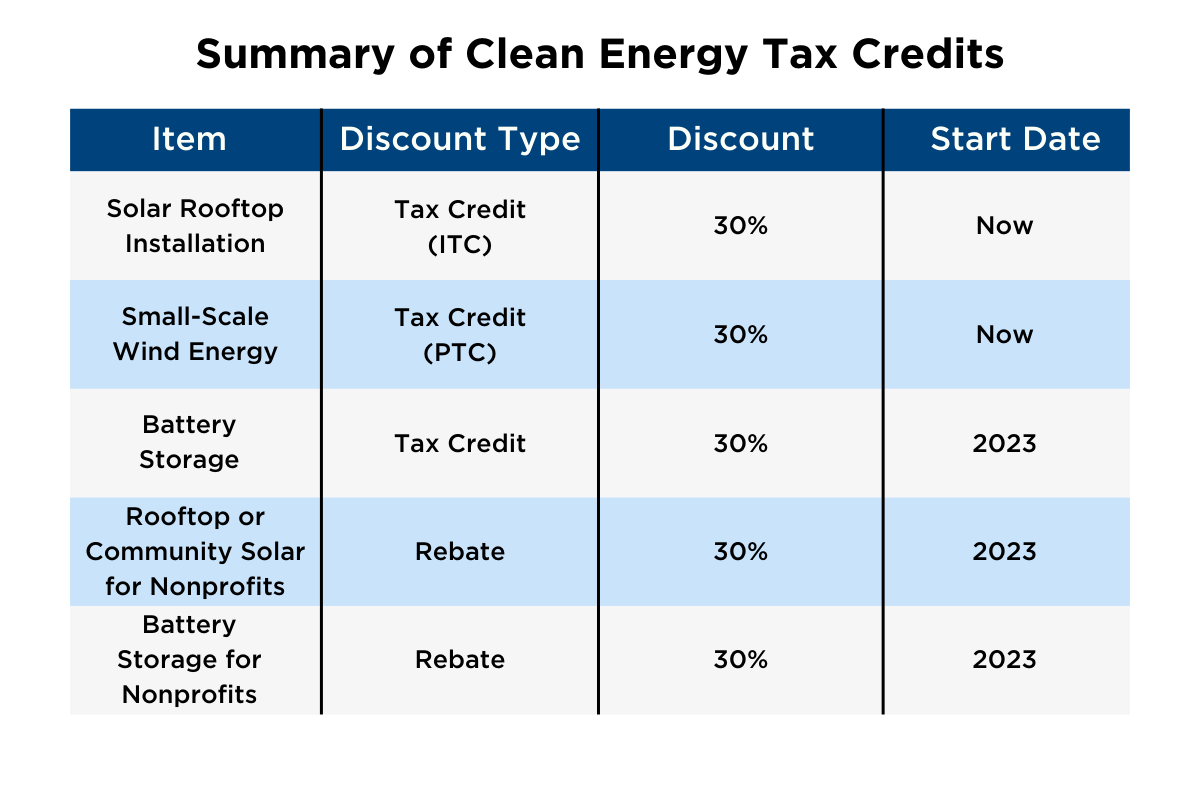
- The ITC (Section 48E) is a one-time credit based on the percentage of the total investment in the facility. In 2026, the base rate is 6%, but it scales to 30% (or more with bonuses) if labor and domestic content requirements are met. It is generally preferred for projects with high upfront capital costs but lower capacity factors, such as offshore wind or solar-plus-storage.
- The PTC (Section 45Y) is a credit per kilowatt-hour (kWh) of electricity produced and sold over a 10-year period. This is often more lucrative for high-efficiency projects in wind-rich regions or high-performance solar farms where the total energy output over a decade outweighs the upfront tax relief of the ITC.
Market Disruptors: Transferability and Direct Pay
Perhaps the most significant way the IRS has shaped energy investment is through the introduction of credit "monetization." Historically, project developers with high expenses but low tax liability had to enter complex "tax equity" partnerships with massive banks to use their credits. In 2026, two mechanisms have streamlined this process: Transferability and Direct Pay.
Section 6418: Transferability
Under Section 6418, most taxable entities can now sell their energy credits to an unrelated third party for cash. This has created a robust secondary market. A manufacturing company with a large tax bill can now "buy" tax credits from a solar developer at a slight discount (e.g., paying 90 cents for every dollar of credit). This provides the developer with immediate liquidity to fund construction while giving the buyer an efficient way to manage their tax liability. The IRS has established rigorous "pre-filing registration" requirements to track these transfers and prevent fraud.
Section 6417: Direct Pay (Elective Pay)
Direct Pay is a game-changer for tax-exempt entities, including local governments, tribal nations, and 501(c)(3) non-profits. Before this provision, these entities could not benefit from tax credits because they didn't pay federal income tax. Now, the IRS treats the credit as a payment of tax, resulting in a direct refund check to the entity. This has led to a surge in municipal energy projects and solar installations on schools and community centers.

Strategic "Adders": Maximizing the Base Credit
In 2026, achieving the "base" credit is rarely the goal. To maximize the internal rate of return (IRR), investors target specific "adders" or bonus credits that can push an ITC from 30% to as high as 50% or 70% in extreme cases.
- Energy Communities Bonus: Projects located in "energy communities"—areas with a history of fossil fuel employment, brownfield sites, or regions where a coal mine or plant has closed—receive a 10% increase (for ITC) or a 10% increase in the credit amount (for PTC). This incentive has successfully redirected capital toward "Just Transition" regions.
- Domestic Content Bonus: To qualify, a certain percentage of the steel, iron, and manufactured products used in the facility must be produced in the United States. In 2026, the manufactured product requirement has scaled upward, challenging supply chains but rewarding those who invest in domestic manufacturing.
- Low-Income Communities Bonus (Section 48(e)): This is a competitive allocation for small-scale solar and wind projects (under 5MW) that serve low-income residential buildings or provide economic benefits to disadvantaged communities.
Prevailing Wage and Apprenticeship (WA&R) Requirements
A cornerstone of the current IRS energy credit framework is the enforcement of labor standards. To qualify for the full 30% ITC (rather than the 6% base rate), project developers must ensure that all laborers and mechanics are paid prevailing wages as determined by the Department of Labor. Furthermore, a specific percentage of total labor hours (15% in 2026) must be performed by qualified apprentices.
The IRS has issued strict guidance on record-keeping for WA&R. Failure to maintain these records or to "cure" underpayments with penalties can result in the loss of the "increased credit rate," effectively destroying the project's financial viability. This has forced energy investors to become much more diligent in their oversight of EPC (Engineering, Procurement, and Construction) contractors.
Comparison of Key Energy Credits in 2026
The following table outlines the primary credits available for energy investments and their core requirements.
| Credit Section | Common Name | Primary Target | 2026 Typical Rate (with WA&R) | Monetization Method |
|---|---|---|---|---|
| Section 48E | Clean Electricity ITC | Capital Investment (Solar, Wind, Nuclear) | 30% of Basis | Transferable / Direct Pay* |
| Section 45Y | Clean Electricity PTC | Energy Production (Per kWh) | ~2.9 cents / kWh (inflation-adj) | Transferable / Direct Pay* |
| Section 45X | Advanced Manufacturing | Component Production (Cells, Blades, Inverters) | Varies by component | Transferable / Direct Pay |
| Section 45V | Clean Hydrogen | Hydrogen Production (based on carbon intensity) | Up to $3.00 / kg | Transferable / Direct Pay |
| Section 45Q | Carbon Sequestration | Carbon Capture & Storage (CCS) | Up to $85 - $180 / tonne | Transferable / Direct Pay |
*Direct Pay is generally limited to tax-exempt entities for 45Y and 48E, whereas 45X, 45V, and 45Q have broader Direct Pay eligibility for a limited initial period.
The Impact on Corporate Investment Strategy
The IRS energy credit system has transformed clean energy from a "feel-good" ESG initiative into a rigorous financial strategy. Corporate treasurers now view energy credits as a tool for capital stack optimization.
- De-risking Early Stage Projects: The certainty of a 10-year credit window allows developers to secure lower interest rates from lenders. Banks are more willing to provide "bridge loans" when they know an IRS refund or a credit sale is guaranteed at the end of construction.
- Vertical Integration: Companies like auto manufacturers are increasingly utilizing Section 45X (Advanced Manufacturing Production Credit). By building battery plants in the US, they receive credits for every battery cell produced, which they can then use to offset their corporate taxes or sell for cash.
- Recapture Risk Management: Investors must still be wary of "recapture." If a project is taken out of service or changes ownership under certain conditions within the first five years, the IRS may "recapture" a portion of the ITC. This has led to the growth of specialized tax insurance products that protect investors against such losses.
Technical Documentation and IRS Compliance
Compliance in 2026 is data-intensive. The IRS requires digital "pre-filing" for all entities intending to transfer credits or claim elective pay. This involves:
- Obtaining a unique registration number for each energy property.
- Submitting detailed information about the project's location, capacity, and placed-in-service date.
- Maintaining a "lifecycle" audit trail that proves domestic content and labor compliance.
For investors, this means the "due diligence" phase of a deal now includes a heavy focus on tax technicals and labor documentation, rather than just engineering and interconnection agreements.
Frequently Asked Questions
1. How do I qualify for the 30% credit rate instead of the 6% base rate?
To qualify for the full 30% rate, projects must meet the IRS Prevailing Wage and Apprenticeship requirements. This means all workers must be paid wages at or above the local prevailing rate for their specific trade, and a set percentage of labor hours must be completed by registered apprentices. Projects under 1 megawatt (MW) AC are generally exempt from these requirements and receive the 30% rate automatically.
2. Can a small business sell its energy tax credits?
Yes. Under the Section 6418 transferability rules, any "eligible taxpayer" (essentially any entity that is not tax-exempt) can sell all or a portion of their energy credits to an unrelated party for cash. The sale must be an all-cash transaction, and the income from the sale is generally not taxable to the seller, nor is the "discount" deductible for the buyer.
3. What constitutes an "Energy Community" for the 10% bonus?
The IRS defines three categories: (1) Brownfield sites; (2) "Statistical Areas" that had significant employment or tax revenue related to coal, oil, or natural gas and have an unemployment rate at or above the national average; and (3) Census tracts where a coal mine has closed (after 1999) or a coal-fired electric generating unit has been retired (after 2009), including adjacent tracts.
4. How long will these technology-neutral credits be available?
The credits are designed to stay in effect until the later of 2032 or the year the US electric sector's greenhouse gas emissions fall to 25% of 2022 levels. Once that "trigger" is met, the credits will phase out over a three-year period. In 2026, most projections suggest these credits will remain fully available well into the mid-2030s.
5. Does the IRS allow credits for energy storage without solar?
Yes. As of 2023, and continuing through 2026, standalone energy storage (batteries, thermal storage, etc.) with a capacity of at least 5 kilowatt-hours is eligible for the Section 48E ITC. Previously, batteries had to be physically "charged" by a co-located solar array to qualify, but that restriction has been removed.
Recommendation for Investors and Developers
For those looking to leverage IRS energy credits in 2026, the primary recommendation is to integrate tax counsel early in the project design phase. Because the "adders" (Domestic Content and Energy Communities) and the "multipliers" (Prevailing Wage and Apprenticeship) now represent the majority of the credit value, they cannot be treated as afterthoughts.
Developers should implement robust labor-tracking software from day one of construction and engage with supply chain partners to secure the "Domestic Content" certifications necessary for the 10% bonus. For institutional investors, the focus should be on the credit transfer market, utilizing specialized platforms and tax insurance to mitigate the risk of IRS audits or project non-performance.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
