
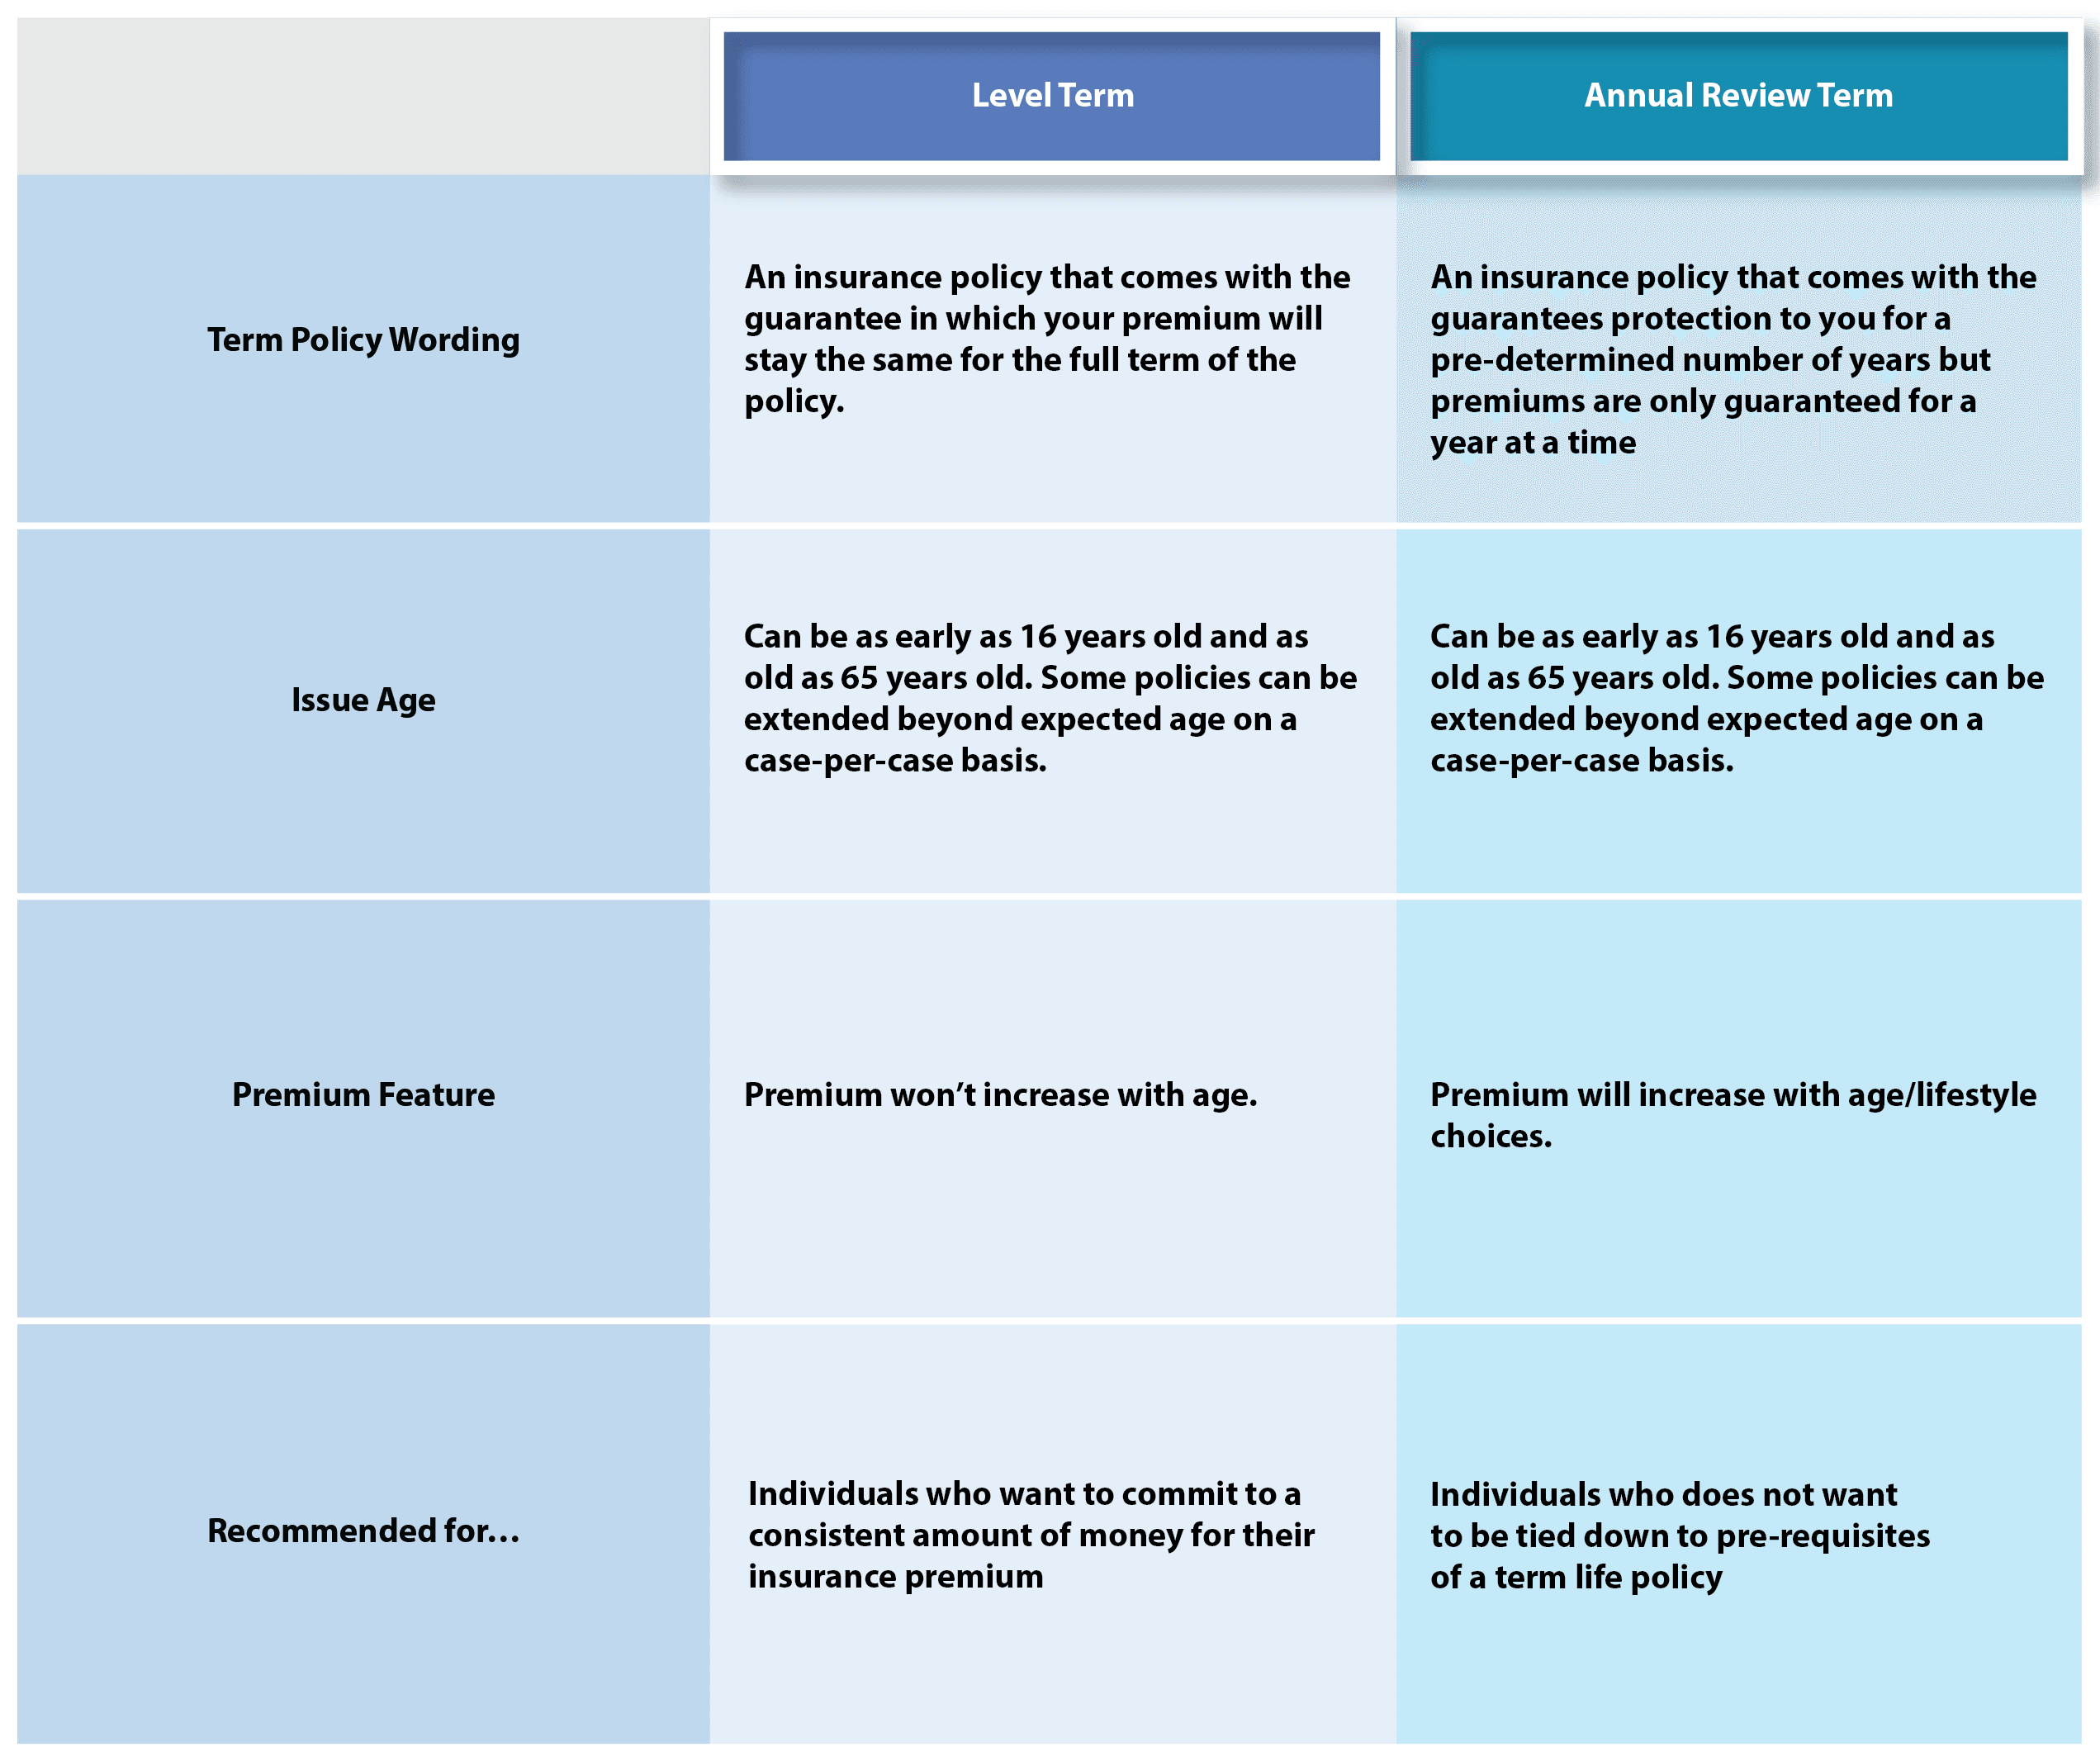
Pacific Life term insurance levels refer to the tiered durations of level-premium coverage—typically 10, 15, 20, 25, or 30 years—and the varying death benefit amounts starting at $50,000. These "levels" ensure that both your monthly premiums and your total coverage amount remain constant throughout the chosen period.
The Foundation of Pacific Life Term Insurance
When discussing "levels" in the context of Pacific Life, it is essential to distinguish between the duration of the policy, the amount of the death benefit, and the underwriting class assigned to the policyholder. As of 2026, Pacific Life remains a top-tier provider, consistently recognized for its financial strength and its flagship term product, PL Promise Term.
Pacific Life has built a reputation over more than 150 years as a mutual holding company, meaning it is not beholden to short-term stock market pressures but rather to the long-term interests of its policyowners. For a consumer looking at term insurance levels in 2026, this stability is a critical factor. Term insurance is a contract for the future; you need the assurance that the "level" of protection you buy today will be honored decades from now.
The "level" aspect of these policies is their most attractive feature. In the insurance industry, "level premium" means that the cost you agree to at the age of 30 or 40 will be the exact same cost you pay in the final year of the term. Similarly, a "level death benefit" means the $500,000 policy you buy to protect your mortgage will still pay out $500,000 whether the claim is made in year two or year twenty-nine.
The Primary Duration Levels: Choosing Your Timeline
The most common way consumers categorize Pacific Life term insurance levels is by the length of the guarantee. Pacific Life offers several specific tiers designed to match different life stages and financial obligations.
10-Year Term Level
The 10-year level is often the most affordable entry point. It is ideally suited for individuals who have short-term debts or are nearing the end of their primary financial responsibilities. For instance, if you are 55 years old and plan to retire at 65, a 10-year term provides a safety net for your spouse during those final high-income years without the higher cost of a 30-year commitment.
15-Year and 20-Year Term Levels
These are the most popular "middle-ground" levels. The 20-year term is frequently cited as the standard for new parents. It ensures that from the time a child is born until they reach early adulthood, a financial cushion exists. Pacific Life’s pricing for these tiers is historically competitive, particularly for those in "Preferred" health classes.
25-Year and 30-Year Term Levels
These longer levels are designed for long-term debt protection, most notably a 30-year mortgage. By locking in a rate for three decades, younger families can ensure that their housing costs and children's education are protected until the mortgage is paid off or the children are financially independent. In 2026, the 30-year level remains a cornerstone of the PL Promise Term suite.
Coverage Levels: Determining the Face Amount
Beyond the duration, the "level" of coverage—also known as the face amount—is a critical decision. Pacific Life offers significant flexibility here, catering to both the middle market and high-net-worth individuals.
Entry-Level Coverage ($50,000 to $249,999)
While many premium carriers focus exclusively on million-dollar policies, Pacific Life offers accessible entry levels. These are often used for "final expense" planning or to cover smaller debts like auto loans or credit card balances.
Mid-Tier Coverage ($250,000 to $999,999)
This is the "sweet spot" for many American families. At these levels, the underwriting becomes more detailed, but the cost per $1,000 of coverage (the "unit cost") often drops. Pacific Life utilizes advanced data analytics and fluidless underwriting (where applicable) to streamline the process for these amounts.
High-Limit Coverage ($1 Million and Above)
For business owners needing key-person insurance or families with significant assets, Pacific Life offers levels reaching into the tens of millions. These policies require more rigorous medical and financial underwriting but offer some of the most competitive "Preferred Best" rates in the industry.
Underwriting Levels: How Health Impacts Your Rate
A frequently overlooked "level" in term insurance is the underwriting class. When you apply for Pacific Life term insurance, you are assigned a risk level based on your health, lifestyle, and family history. This level determines your premium.
- Preferred Best: The highest tier. Reserved for those in excellent health with no tobacco use and a clean family medical history.
- Preferred: Still excellent, but perhaps with one minor health indicator (like slightly elevated cholesterol) that prevents the "Best" designation.
- Select: A tier for those in good health who might have a more significant but well-managed health issue.
- Standard: The baseline for average health.
- Substandard (Rated): For individuals with chronic conditions (e.g., diabetes or heart disease). These levels involve "table ratings," which increase the premium by a certain percentage.
Understanding these levels is vital because a 20-year term at the "Preferred" level might actually be cheaper than a 10-year term at the "Standard" level. Pacific Life’s PL Promise Term documentation provides clear guidelines on how these classes are determined.
Key Features and Riders Across All Levels
Regardless of the duration or coverage amount you select, Pacific Life includes or offers several features that enhance the value of the policy. These are not merely "add-ons" but are integral to the flexibility of the term insurance levels.
The Conversion Level
One of the most powerful features of Pacific Life term insurance is the conversion privilege. This allows the policyholder to convert their term policy into a permanent life insurance policy (like Universal Life) without undergoing a new medical exam.
As of 2026, this is a critical hedge against future uninsurability. If you develop a health condition during your 20-year term, you can "level up" to a permanent policy at the end of the term, keeping the same health rating you had when you were younger and healthier.
Accelerated Death Benefit Rider
Most Pacific Life term levels include an accelerated death benefit for terminal illness. This allows the policyholder to access a portion of the death benefit while they are still living if they are diagnosed with a terminal condition. This provides a level of "living benefits" that can help pay for medical costs or end-of-life care.
Waiver of Premium Rider
For an additional cost, you can add a level of protection against disability. If you become totally disabled and are unable to work, Pacific Life will waive your premium payments, keeping your life insurance in force even when you lose your primary income.
Comparing Pacific Life Term Levels
To help visualize how these levels function, the following table breaks down the standard offerings for the PL Promise Term product.
| Feature | 10-Year Level | 20-Year Level | 30-Year Level |
|---|---|---|---|
| Minimum Age | 18 | 18 | 18 |
| Maximum Age (Non-Tobacco) | 80 | 65 | 50-55* |
| Minimum Face Amount | $50,000 | $50,000 | $50,000 |
| Premium Structure | Guaranteed Level | Guaranteed Level | Guaranteed Level |
| Best Use Case | Short-term debt/Business | Raising children | 30-year mortgage |
| Conversion Window | Generally up to 10 years | Generally up to 20 years** | Generally up to 20 years** |
*Maximum age for 30-year terms varies based on health and tobacco usage. **Conversion periods are subject to the specific terms of the policy contract; usually the lesser of the term length or age 70.
Technical Depth: The Mechanics of Level Premiums
Why does the "level" nature of these premiums matter so much? To understand this, one must look at the "natural cost of insurance." As humans age, the statistical probability of death increases every year. If you were to pay for life insurance on a year-by-year basis (Annually Renewable Term), your price would go up every single year, eventually becoming unaffordable in your 60s or 70s.
Pacific Life uses actuarial leveling. They calculate the total cost of insuring you for, say, 20 years, and then average that cost out so you pay a flat rate. In the early years of the policy, you are technically "overpaying" relative to your current risk of death. In the later years, you are "underpaying" significantly. The "level" premium protects the consumer from the price shocks associated with aging.
Furthermore, Pacific Life’s 2026 underwriting models utilize Medical Information Bureau (MIB) data and prescription history to offer "Smooth Sailing" or accelerated underwriting. This means that for many applicants at various levels, the traditional "level" of hassle—needles and physical exams—is being reduced or eliminated for those who qualify.
Common Mistakes When Selecting Levels
Choosing the wrong level can be a costly mistake. Here are the most frequent errors observed in the 2026 market:
- Underestimating the Duration: Many people choose a 10-year level because it is the cheapest, only to find that they still need insurance 11 years later. Buying a new policy at an older age is always more expensive than having bought a longer term initially.
- Ignoring the Conversion Window: People often forget that their "level" term can become a "level" permanent policy. Failing to monitor the expiration of the conversion rider can result in losing the ability to keep coverage if health declines.
- Inflation Neglect: A $500,000 level of coverage may seem like a lot today, but with 2026 inflation considerations, its purchasing power in 2046 will be significantly less. It is often wise to "level up" the coverage amount slightly more than you think you need.
Frequently Asked Questions
What happens after my Pacific Life term level expires?
Once the initial level period (e.g., 20 years) ends, the policy does not necessarily cancel immediately, but the "level" premium guarantee expires. If you continue the policy, the premiums will typically spike significantly to the Annually Renewable Term rate, which increases every year. Most policyholders choose to either let the policy lapse, convert it to permanent insurance before the term ends, or apply for a new term policy.
Can I change my coverage level after the policy is issued?
You can generally request to decrease your coverage level (face amount) to lower your premium, subject to Pacific Life’s minimum requirements. However, you cannot "level up" or increase your coverage amount without undergoing a new medical exam and application process, as this represents an increased risk to the insurer.
Does Pacific Life offer a "Return of Premium" level?
Historically, some carriers offered a Return of Premium (ROP) level where you get your premiums back if you outlive the term. As of 2026, Pacific Life focuses primarily on the PL Promise Term, which is a pure protection product without an ROP feature. This keeps the premiums significantly lower than ROP products.
Is the death benefit taxable at different levels?
In the United States, under Internal Revenue Code Section 101(a), the death benefit from a life insurance policy is generally received by the beneficiary tax-free, regardless of whether the level is $50,000 or $5,000,000. However, if the policy is part of a very large estate, it may be subject to estate taxes. Consult a tax advisor for specific 2026 regulations regarding high-level policies.
How does Pacific Life's "level" compare to other companies?
Pacific Life is known for being extremely aggressive with pricing in the "Preferred" and "Preferred Best" levels. While some competitors might offer lower rates for "Standard" health risks, Pacific Life is often the go-to for those who are healthy and want the highest financial strength ratings (A+ or higher from AM Best).
Final Recommendation: How to Choose Your Level
When selecting your Pacific Life term insurance level, start by mapping out your longest financial obligation. If you have a child who is 2 years old, a 20-year term is your minimum "level" for duration. If you have a 30-year mortgage, the 30-year level is the most logical choice.
Once you have the duration, calculate your coverage level by adding your total debts, your mortgage, and 5 to 10 times your annual salary. Finally, work with a financial professional to run a quote for Pacific Life's PL Promise Term. Because Pacific Life utilizes a "Level Premium" structure, the earlier you lock in your age and health class, the lower your long-term costs will be.
By 2026 standards, Pacific Life remains a premier choice for those seeking predictable, high-quality term insurance that provides peace of mind through fixed, level tiers.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
