
Securing homeowners and auto insurance quotes in California requires understanding Wawanesa’s specific digital quoting platforms, regional eligibility criteria, policy bundle structures, and the distinct statutory requirements mandated by the California Department of Insurance.
Navigating the insurance landscape in California has become increasingly complex due to evolving market conditions, legislative changes, and shifting carrier appetites. For residents looking to secure coverage through Wawanesa Mutual Insurance Company—a prominent mutual property and casualty insurer operating in the state—obtaining accurate homeowners and auto insurance quotes involves a structured evaluation of personal risk profiles, vehicle specifications, property characteristics, and bundling opportunities. Because insurance is regulated closely at the state level, finding the right policy requires familiarity with both Wawanesa's digital intake systems and California’s consumer protection frameworks.
Understanding Wawanesa's Presence in the California Insurance Market
Wawanesa Mutual Insurance Company has a long-standing history of providing property and casualty insurance. Originally founded in Canada, the company established a significant footprint in the United States, with a heavy operational emphasis on the California personal lines market. For decades, the carrier built a reputation on customer-centric service, competitive pricing structures, and mutual ownership models where policyholders technically share in the company’s financial health through potential dividends, though dividend distributions are never guaranteed and depend entirely on board approval and underwriting performance.
In recent years, the California property insurance market has undergone severe systemic disruption. Catastrophic wildfires, inflation, rising construction costs, and reinsurance market pressures have forced numerous carriers to restrict new business, non-renew existing policies, or implement steep rate revisions approved by regulatory bodies. Wawanesa has navigated these turbulent market dynamics by tightening its underwriting guidelines, modifying its digital quoting engines, and updating its risk-scoring algorithms. Consequently, securing a policy today is vastly different than it was a decade ago, demanding meticulous accuracy when submitting quote requests.
Auto Insurance Quotes in California: Process and Requirements
When requesting an auto insurance quote from Wawanesa in California, applicants must navigate a state-specific regulatory framework governed by Proposition 103. Under California law, auto insurance premiums cannot be based primarily on credit scores. Instead, insurers must weigh three mandatory primary factors: driving safety record, annual mileage, and years of driving experience. Secondary factors, such as vehicle safety ratings and garaging zip code, also play substantial roles.
Step-by-Step Quoting Workflow
- Gather Required Personal Data: Prepare your driver's license numbers for all household drivers, Social Security numbers (used for identity verification and claims history reports, though not for credit-based pricing in CA), and current policy declaration pages if you are switching carriers.
- Compile Vehicle Specifications: Note the exact Vehicle Identification Numbers (VINs), annual mileage estimates, primary use (commute, pleasure, business), and any custom aftermarket equipment.
- Select Coverage Limits: Determine your desired liability limits, comprehensive and collision deductibles, and optional coverages such as uninsured/underinsured motorist protection, roadside assistance, and rental car reimbursement.
- Initiate the Online or Agent Quote: Access Wawanesa’s digital portal or connect with a licensed captive agent or independent broker who represents the carrier. Enter the collected data accurately to prevent discrepancies during underwriting verification.
- Review and Customize Discounts: Examine the generated quote to ensure all eligible discounts—such as paperless billing, multi-car, good driver, and safety feature discounts—have been properly applied.
California Minimum Liability Mandates vs. Recommended Coverages
California law mandates specific minimum liability limits (often referred to as 15/30/5 limits):
- $15,000 for injury or death of one person per accident.
- $30,000 for total injury or death liability per accident.
- $5,000 for property damage per accident.
Insurance professionals and consumer advocates widely caution that these statutory minimums are drastically inadequate for modern financial protection. A minor fender-bender involving a luxury vehicle or an accident resulting in severe medical treatment can easily exceed these limits within seconds, leaving the at-fault driver personally liable for remaining judgments. Wawanesa’s quoting platform typically encourages higher limits, such as 100/300/100, to ensure robust asset protection.
Homeowners Insurance Quotes in California: Navigating High-Risk Real Estate
Securing homeowners insurance (HO-3 or HO-5 policy forms) in California has evolved into a meticulous underwriting exercise. Unlike auto insurance, where credit score pricing is restricted, property insurance underwriting heavily accounts for physical location, brush clearance, proximity to wildfire hazard zones, roof age and construction materials, and historical claims data (tracked via industry databases like CLUE—Comprehensive Loss Underwriting Exchange).
Key Information Required for a Homeowners Quote
- Property Characteristics: Exact square footage, year built, number of stories, foundation type, and roof construction material/installation date.
- Protection Class: Distance to the nearest fire hydrant and professional fire department station.
- Clerical History: A complete record of any property-related claims filed within the past five to seven years.
- Safety Mitigations: Presence of monitored burglar and fire alarm systems, automatic water shut-off valves, and defensible space compliance.
Wildfire Risk Scoring and Availability
Wawanesa, like all major property insurers in California, utilizes advanced geospatial mapping tools and proprietary risk-scoring models to evaluate wildfire vulnerability. Properties situated in State Responsibility Areas (SRAs) or Local Responsibility Areas (LRAs) designated as High or Very High Fire Hazard Severity Zones face intense underwriting scrutiny. In some cases, automated online quoting may be restricted for homes in extreme brush zones, requiring manual review by an underwriter or referral to the California FAIR Plan as a residual market mechanism, supplemented by a wrap-around Difference in Conditions (DIC) policy.
Bundling Auto and Homeowners Policies
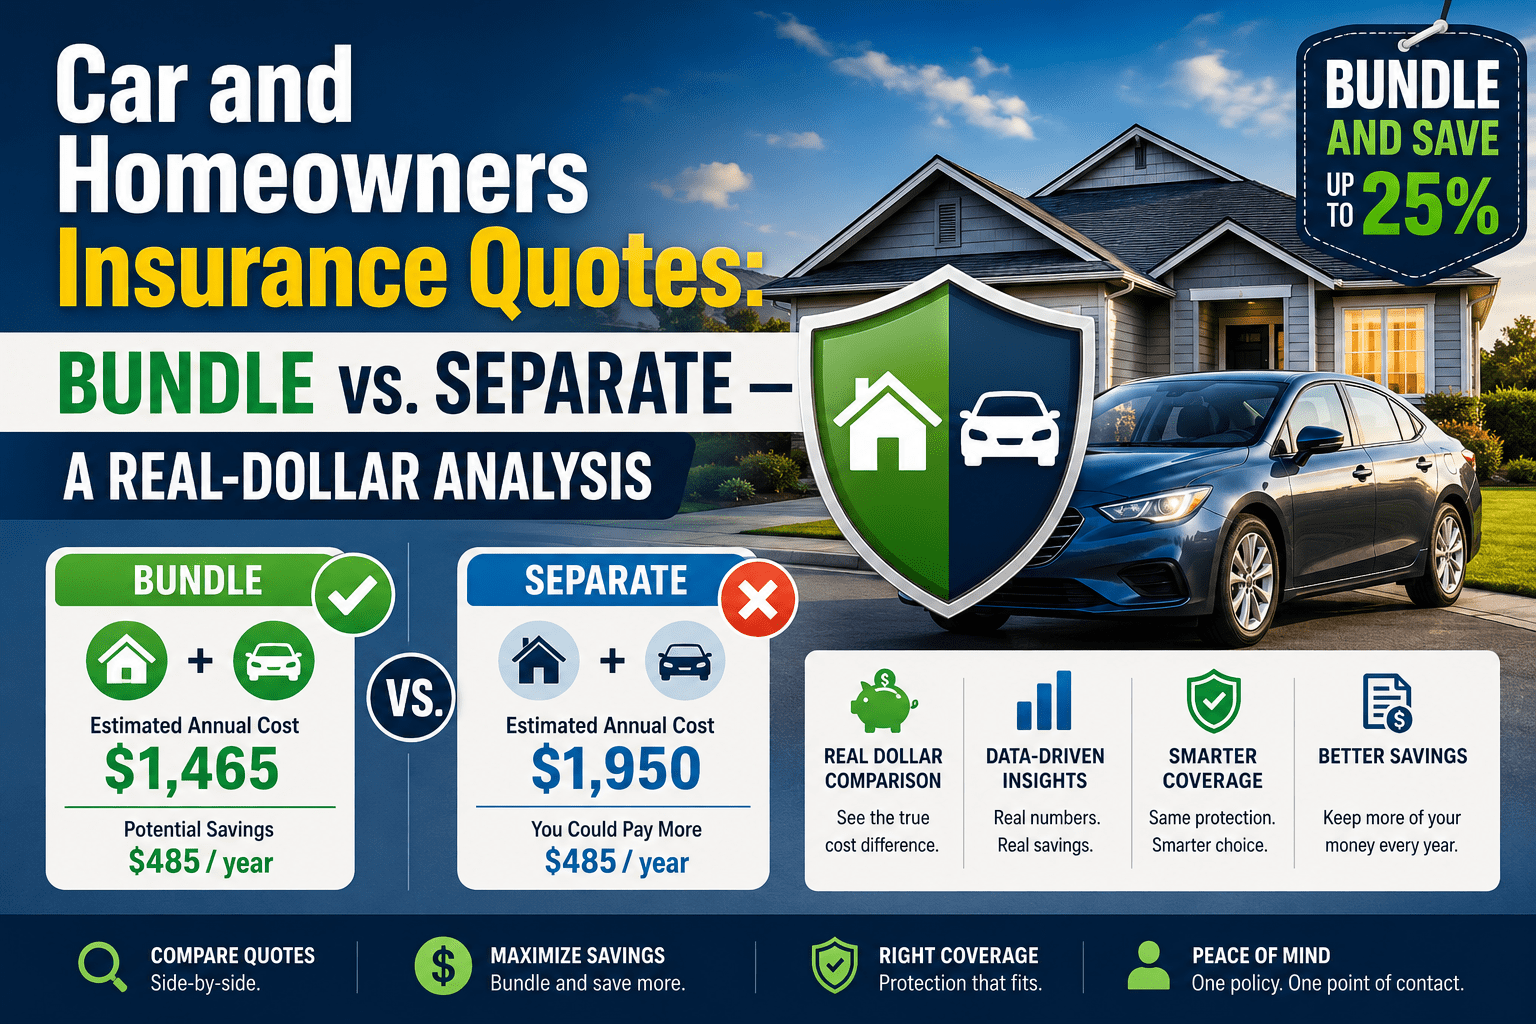
One of the most effective strategies to optimize pricing and maximize acceptance probability with Wawanesa is bundling homeowners and auto insurance. Multi-policy discounts provide significant percentage reductions on premium totals. Beyond financial incentives, bundling simplifies administrative oversight, aligning renewal dates, billing schedules, and customer service touchpoints under a single carrier ecosystem.
| Insurance Feature | Auto Insurance Policy | Homeowners Insurance Policy | Bundled Advantage |
|---|---|---|---|
| Primary Governing Law | California Proposition 103 (Driving record, mileage, experience) | California Insurance Code / Wildfire Mitigation Guidelines | Integrated multi-policy discount applied to both premiums |
| Core Protection | Liability, Collision, Comprehensive, Uninsured Motorist | Dwelling (Replacement Cost), Personal Property, Liability | Single carrier claims coordination for multi-line incidents |
| Underwriting Focus | Motor vehicle reports, VIN safety ratings, annual commute miles | Property age, roof condition, wildfire risk score, CLUE report | Streamlined annual renewal review and consolidated billing |
| Deductible Structure | Flat dollar amounts per occurrence ($500, $1,000) | Percentage-based or flat deductibles (Wind/Hail, Fire, All Other Perils) | Unified customer portal access for payment and document retrieval |
Step-by-Step Guide: Obtaining and Managing Your Quote
To maximize efficiency and secure the most accurate pricing when interacting with Wawanesa's systems, follow a disciplined procedural approach.
- Audit Your Current Policies: Before requesting a new quote, pull your current declaration pages. Note your existing coverage limits, endorsements, and deductible levels. This establishes a baseline for apples-to-apples comparisons.
- Prepare Verification Documents: Have your vehicle registrations, driver's licenses, and property deed or closing statement handy. Inaccurate VINs or square footage figures will trigger underwriting re-quotes and potential premium adjustments later.
- Run Separate and Combined Quotes: Test the portal by requesting an auto-only quote, a homeowners-only quote, and a combined bundled quote. Compare the cost differences to evaluate the true financial benefit of the multi-policy discount.
- Examine Endorsements and Riders: Standard policies do not cover everything. Review optional endorsements for earthquake coverage (often written separately through the California Earthquake Authority), water backup protection, ordinance or law coverage, and scheduled personal property (jewelry, fine art).
- Bind and Verify Effective Dates: Once you select a quote, complete the payment setup and ensure that effective dates align seamlessly with your previous policy expiration to prevent any coverage gaps.
Frequently Asked Questions
Can I get an instant online quote for both auto and home with Wawanesa in California?
Yes, Wawanesa provides digital quoting tools on their official website that allow prospective policyholders to input vehicle and property details. However, properties located in designated high-risk wildfire zones or vehicles with specialized commercial modifications may require manual underwriting review, which pauses instant online generation.
Does Wawanesa use credit scores to calculate auto insurance quotes in California?
No. Proposition 103 strictly prohibits California auto insurers from using credit scores, credit history, or credit-based insurance scores in rating auto insurance policies. Rates are determined strictly by driving record, annual mileage, and years of experience, alongside secondary vehicle-specific factors.
How do I qualify for a multi-policy discount with Wawanesa?
To qualify for the multi-policy (bundle) discount, you must maintain active, qualifying personal auto and homeowners (or renters/condo) insurance policies concurrently with Wawanesa. The discount is typically applied automatically to your billing statements once both policies are verified as active in the system.
What should I do if my home is denied coverage due to wildfire risk?
If automated underwriting declines your homeowners insurance quote due to brush exposure or wildfire risk, do not panic. Consult with an independent agent who can explore admitted carrier alternatives, surplus lines options, or the California FAIR Plan paired with a DIC policy to ensure your mortgage lender's requirements are fully satisfied.
Are Wawanesa insurance quotes guaranteed for a specific period?
Insurance quotes are estimates based on the information provided at the exact time of entry. They are subject to verification of driving records, motor vehicle reports, and property inspections. Quotes are typically valid for a limited window (usually 30 days) before requiring a refresh to reflect current rate filings approved by the state.
Final Recommendations and Next Actions
When seeking Wawanesa homeowners insurance and auto quotes in California, preparation and precision are your greatest assets. Ensure all data regarding your driving history and property specifications are meticulously accurate to prevent underwriting delays or post-bind premium spikes. Because the California insurance market remains dynamic and capacity-constrained, obtaining quotes well in advance of your current policy expiration date ensures uninterrupted protection for your home, vehicles, and financial assets. Review your policy coverages annually with a qualified insurance professional to adapt to changing property values and statutory updates.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
