Understanding the No Fee Refinance Mortgage: Costs, Benefits, and Mechanics in 2026

A no fee refinance is a mortgage restructuring where the borrower pays no upfront closing costs at the time of signing. Instead, lenders recover these expenses by either charging a slightly higher interest rate—known as premium pricing—or by rolling the closing costs into the new loan's principal balance.
In the 2026 mortgage market, "no fee" refinancing remains a popular tool for homeowners looking to capitalize on interest rate fluctuations without depleting their liquid savings. However, the term itself is often a marketing shorthand that requires a deeper technical understanding to navigate effectively. While you may avoid a check at the closing table, the costs of originating, appraising, and insuring a mortgage do not disappear; they are simply redistributed over the life of the loan. Understanding how these costs are structured is essential for determining whether a no fee refinance serves your long-term financial interests or merely provides short-term relief.
The Structural Mechanics of a No Fee Refinance
To understand a no fee refinance, one must first identify where traditional closing costs usually go. Standard refinancing typically involves thousands of dollars in "third-party" and "origination" fees, including appraisal fees, title insurance, credit report fees, recording fees, and lender origination points. In a standard "low-rate" refinance, the borrower pays these out of pocket.
In a no fee refinance, the lender uses one of two primary methods to cover these costs:
1. Lender Credits via Premium Pricing
This is the most common form of a true "no-cost" refinance. The lender offers you an interest rate that is higher than the current market "par rate." For example, if the market rate is 5.5%, a lender might offer you a rate of 5.875%. The extra interest you pay over the life of the loan generates a "credit" from the lender. This credit is then used to pay off the closing costs on your behalf.
From a technical SEO and financial perspective, this is often called an "above-par" loan. The lender is essentially betting that the extra interest they collect over the first few years will exceed the money they paid out for your closing costs.
2. Financed Closing Costs (The "Wrap")
In this scenario, the interest rate remains closer to market levels, but the closing costs are added to the principal balance of the loan. If you owe $300,000 on your home and your closing costs are $6,000, your new mortgage balance becomes $306,000. While this is often marketed as a "no-cost" option because no cash is required at closing, it is technically a "no out-of-pocket cost" refinance.
The distinction is critical: in the first method, you pay more interest on the same principal; in the second method, you pay interest on a larger principal. Both methods result in a higher long-term cost than a traditional refinance where fees are paid upfront.
Analyzing the Break-Even Point
The most important metric in any refinance, particularly a no fee one, is the break-even point. This is the moment when the monthly savings generated by the new, lower interest rate have finally covered the "hidden" costs of the refinance.
When you opt for a no fee refinance via a higher interest rate, your monthly savings will be smaller than they would have been with a standard refinance. Therefore, you must calculate how long you intend to stay in the home. If the "standard" refinance saves you $200 a month but costs $5,000 upfront, your break-even point is 25 months. If the "no fee" refinance saves you only $100 a month but costs $0 upfront, you are technically "in the black" from month one.
However, over a 30-year period, that $100 difference in savings adds up. By year 10, the "standard" refinance would have saved you more money total, even after accounting for the initial $5,000 investment. This makes no fee refinancing a strategic tool for borrowers who anticipate selling the property or refinancing again within a three-to-five-year window.
Comparing Traditional vs. No Fee Refinance Options
The following table illustrates a hypothetical scenario for a borrower in 2026 with a $400,000 loan balance, comparing a traditional refinance to the two primary types of no fee options.
| Feature | Traditional Refinance | No Fee (Lender Credit) | No Fee (Financed Costs) |
|---|---|---|---|
| Interest Rate | 5.5% | 6.0% | 5.5% |
| Principal Balance | $400,000 | $400,000 | $408,000 |
| Upfront Cash Required | $8,000 | $0 | $0 |
| Monthly Payment (P&I) | $2,271 | $2,398 | $2,317 |
| Monthly Savings vs. 7% Rate | $392 | $265 | $346 |
| Break-Even Period | 20.4 Months | Immediate | Immediate |
| Total Interest (10 Years) | $194,545 | $214,120 | $198,435 |
Note: Figures are estimates based on 2026 market projections for a 30-year fixed-rate mortgage. "P&I" stands for Principal and Interest.
Eligibility and Requirements in 2026
As we move through 2026, lenders have maintained strict but fair standards for no fee products. Because the lender is taking on the risk of "pre-paying" your closing costs, they often require a more robust borrower profile to ensure they recoup their investment through the higher interest rate over time.
Credit Score Thresholds
While standard refinances may be accessible with a credit score in the mid-600s, the most competitive no fee refinance offers typically require a FICO score of 720 or higher. Lenders view borrowers with higher scores as less likely to default or prepay too early, which protects the lender’s margin on the premium interest rate.
Equity and Loan-to-Value (LTV)
You generally need a significant amount of equity to qualify for the best no fee terms. If you are rolling costs into the loan balance, your LTV ratio will increase. If this pushes your LTV above 80%, you may be required to pay Private Mortgage Insurance (PMI), which could easily negate any savings gained from the refinance. In 2026, most technical advisors recommend having at least 25% equity before pursuing a financed-cost refinance.
The Role of the Loan Estimate (LE)
Under the Consumer Financial Protection Bureau (CFPB) guidelines, lenders must provide a Loan Estimate within three business days of your application. When evaluating a no fee refinance, you must look at Page 2, Section J of the LE. This section will show "Lender Credits." If the credits exactly match the "Total Closing Costs" in Section I, you have a true zero-out-of-pocket refinance.
When a No Fee Refinance is the Right Choice
Choosing a no fee refinance is less about the "cheapest" loan and more about liquidity management. There are several specific scenarios where this product outshines a traditional refinance:
- Preserving Emergency Funds: If paying $7,000 in closing costs would deplete your savings, a no fee refinance allows you to lower your monthly payment while keeping your cash reserves intact for home repairs or life emergencies.
- Short-Term Residency: If you plan to sell your home in two to four years, you likely won't reach the break-even point of a traditional refinance. A no fee option allows you to start saving money on your monthly payment immediately without ever having to "earn back" an upfront investment.
- Declining Rate Environments: In a market where rates are expected to drop further in the next 12 to 18 months, a no fee refinance is an excellent "bridge." You can lower your current rate now for $0 down, and then refinance again later when rates hit their floor, without having lost money on the first transaction.
- High Opportunity Cost of Capital: If you are a savvy investor and can earn a 10% return in the stock market or a business venture, paying $8,000 upfront for a mortgage refinance (which might only "save" you 5% effectively) is a poor use of capital. Keeping the $8,000 and taking the higher mortgage rate is mathematically superior.
Potential Pitfalls and Mistakes
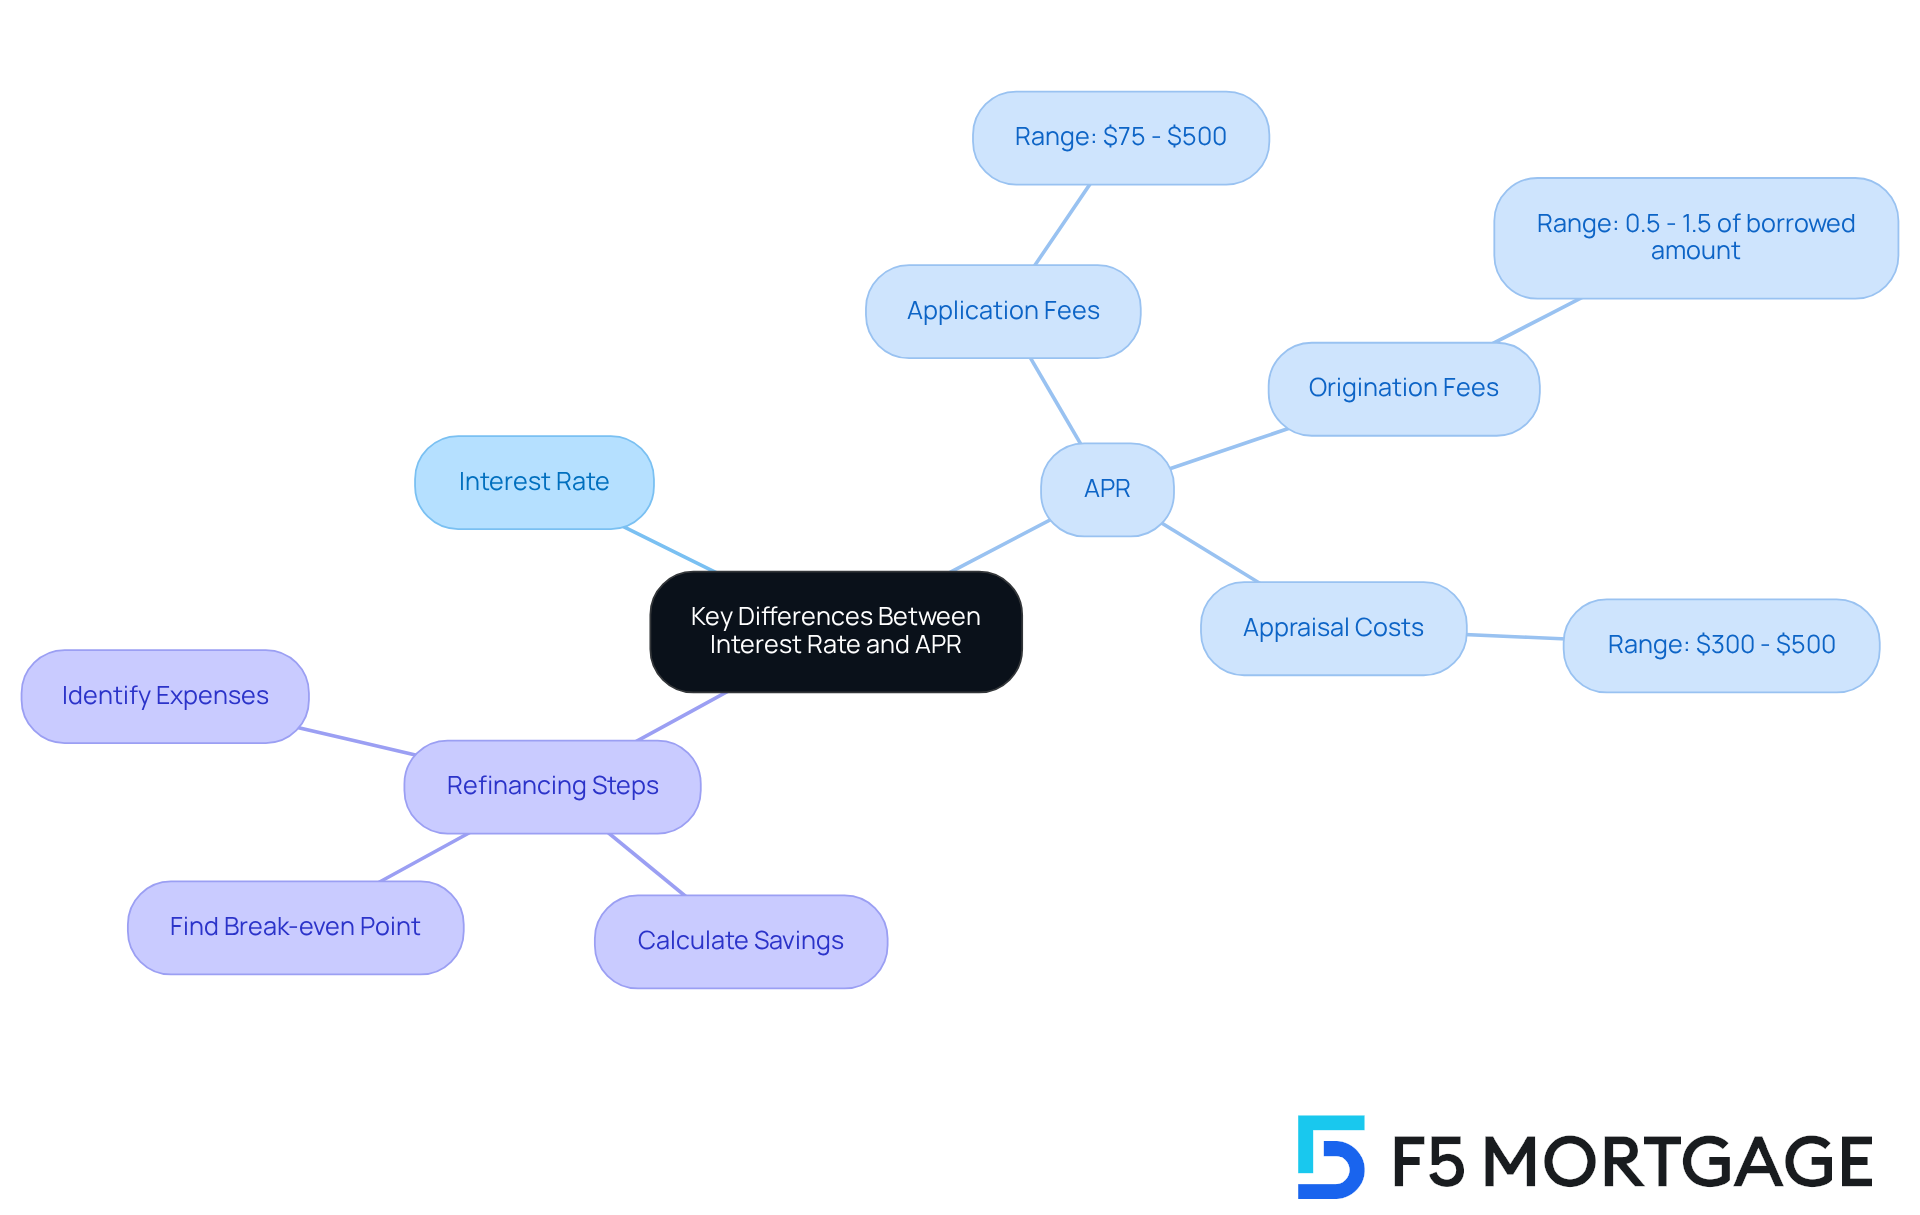
Despite the convenience, borrowers often fall into traps when navigating no fee mortgages. The most common error is ignoring the Annual Percentage Rate (APR). The APR represents the true cost of the loan, including interest and fees expressed as a yearly rate. In a no fee refinance involving lender credits, the APR will be higher than the base interest rate. Borrowers should use the APR to compare different no fee offers from multiple lenders to see who is truly offering the best deal.
Another mistake is "resetting the clock" without calculation. If you are 10 years into a 30-year mortgage and you refinance into a new 30-year no fee mortgage, you may lower your monthly payment, but you are extending your debt by a decade. In 2026, many borrowers are instead opting for 15-year or 20-year no fee refinances to ensure they don't end up paying vastly more in total interest over the lifetime of the home.
Lastly, be wary of "junk fees." Even in a no fee refinance, some unscrupulous lenders might try to hide "processing" or "administrative" fees that aren't fully covered by the credits. Always compare the "Total Cash to Close" line on your Closing Disclosure—it should be zero or a very small amount representing pre-paid interest or escrow cushions.
FAQ
Is a no fee refinance actually "free"?
No, a no fee refinance is not free. The costs are either built into a higher interest rate or added to your loan balance. You are simply trading upfront cash for a slightly higher long-term cost. It is a method of financing the transaction costs rather than paying them at the start.
Does a no fee refinance affect my credit score?
The refinance itself involves a hard credit inquiry, which may cause a temporary, minor dip in your credit score. However, the "no fee" structure specifically does not have a unique impact on your score compared to any other type of mortgage. The long-term impact of a lower monthly payment often helps your credit by improving your debt-to-income ratio.
Can I get a no fee refinance on a 15-year mortgage?
Yes, no fee structures are available for various loan terms, including 15-year and 20-year fixed-rate mortgages. Because 15-year mortgages already have lower interest rates than 30-year ones, the "premium" rate you accept for a no fee deal may still be significantly lower than what you are currently paying on a 30-year loan.
How do I know if the lender is giving me a fair deal?
The best way to verify fairness is to request two quotes from the same lender: one for a standard refinance with fees and one for a no fee refinance. Compare the interest rates. If the no fee rate is more than 0.5% higher than the standard rate, the lender might be overcharging for the "no fee" convenience.
Are no fee refinances available for FHA or VA loans?
Yes, FHA and VA loans have specific "streamline" refinance programs. While these often have lower documentation requirements, they still have closing costs (like the VA funding fee or FHA upfront mortgage insurance premium). These can often be rolled into the loan, effectively creating a no-out-of-pocket refinance.
Summary and Next Actions
Understanding the no fee refinance mortgage is about recognizing that you are choosing a different payment schedule for your closing costs. It is an ideal solution for those who prioritize immediate cash flow and liquidity over the absolute lowest interest rate possible.
If you are considering this path in 2026, your next step should be to gather your current mortgage statement and a recent home valuation. Contact at least three lenders and ask for a "Loan Estimate with Lender Credits" to cover all closing costs. Compare these estimates side-by-side, paying close attention to the APR and the Total Interest Percentage (TIP). By doing so, you can ensure that your "no fee" deal is a sound financial move rather than a costly convenience.
Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
