How to Find Affordable Auto Insurance Without Sacrificing Necessary Protection
Finding affordable auto insurance requires balancing state legal requirements, vehicle-specific needs, and personal financial profiles to secure the lowest possible rates without leaving yourself exposed to catastrophic financial risk. Insurance premiums are calculated using a complex matrix of risk factors, meaning the cheapest policy for one driver might be entirely inadequate or overly expensive for another. To lower your monthly or semi-annual bill, you must understand how insurers price risk, evaluate your coverage limits, maximize available discounts, and systematically compare quotes from multiple providers.
Understanding the Mechanics of Auto Insurance Pricing
To successfully find affordable auto insurance, you first need to understand how insurance companies determine your rates. Insurers do not pull numbers out of thin air; they use actuarial data to predict the likelihood that you will file a claim and the potential cost of that claim.
Every time an insurer evaluates a policy application, they weigh personal risk factors against broader statistical trends. Recognizing which elements of your profile you can control and which you cannot allows you to focus your efforts where they will yield the greatest financial return.
Core Factors Influencing Your Premium
- Driving Record: Your history of accidents, traffic violations, and speeding tickets is one of the heaviest influences on your rate. Clean records secure the lowest tiers, while moving violations trigger rate hikes that can last for three to five years.
- Credit History: In most jurisdictions, insurers use a credit-based insurance score to predict risk. Statistically, drivers with higher credit scores file fewer claims. Improving your credit score over time directly reduces your insurance costs.
- Vehicle Make and Model: The cost to repair or replace your vehicle, its safety ratings, its engine size, and its theft rates directly impact comprehensive and collision coverage pricing.
- Location: Urban areas with high traffic density, vandalism rates, and weather-related risks generally experience higher insurance premiums than rural areas.
- Coverage Levels and Deductibles: Choosing higher liability limits increases your base price, while raising your deductibles lowers your immediate premium.
Deciding on the Right Coverage Levels
A common mistake made by drivers searching for cheap car insurance is slashing coverage to the bare legal minimum. While state-minimum liability insurance yields the lowest upfront cost, it leaves you financially vulnerable if you cause a severe accident.
Understanding the components of a policy ensures you do not buy coverage you do not need while protecting yourself from devastating out-of-pocket expenses.
Key Coverage Components Explained
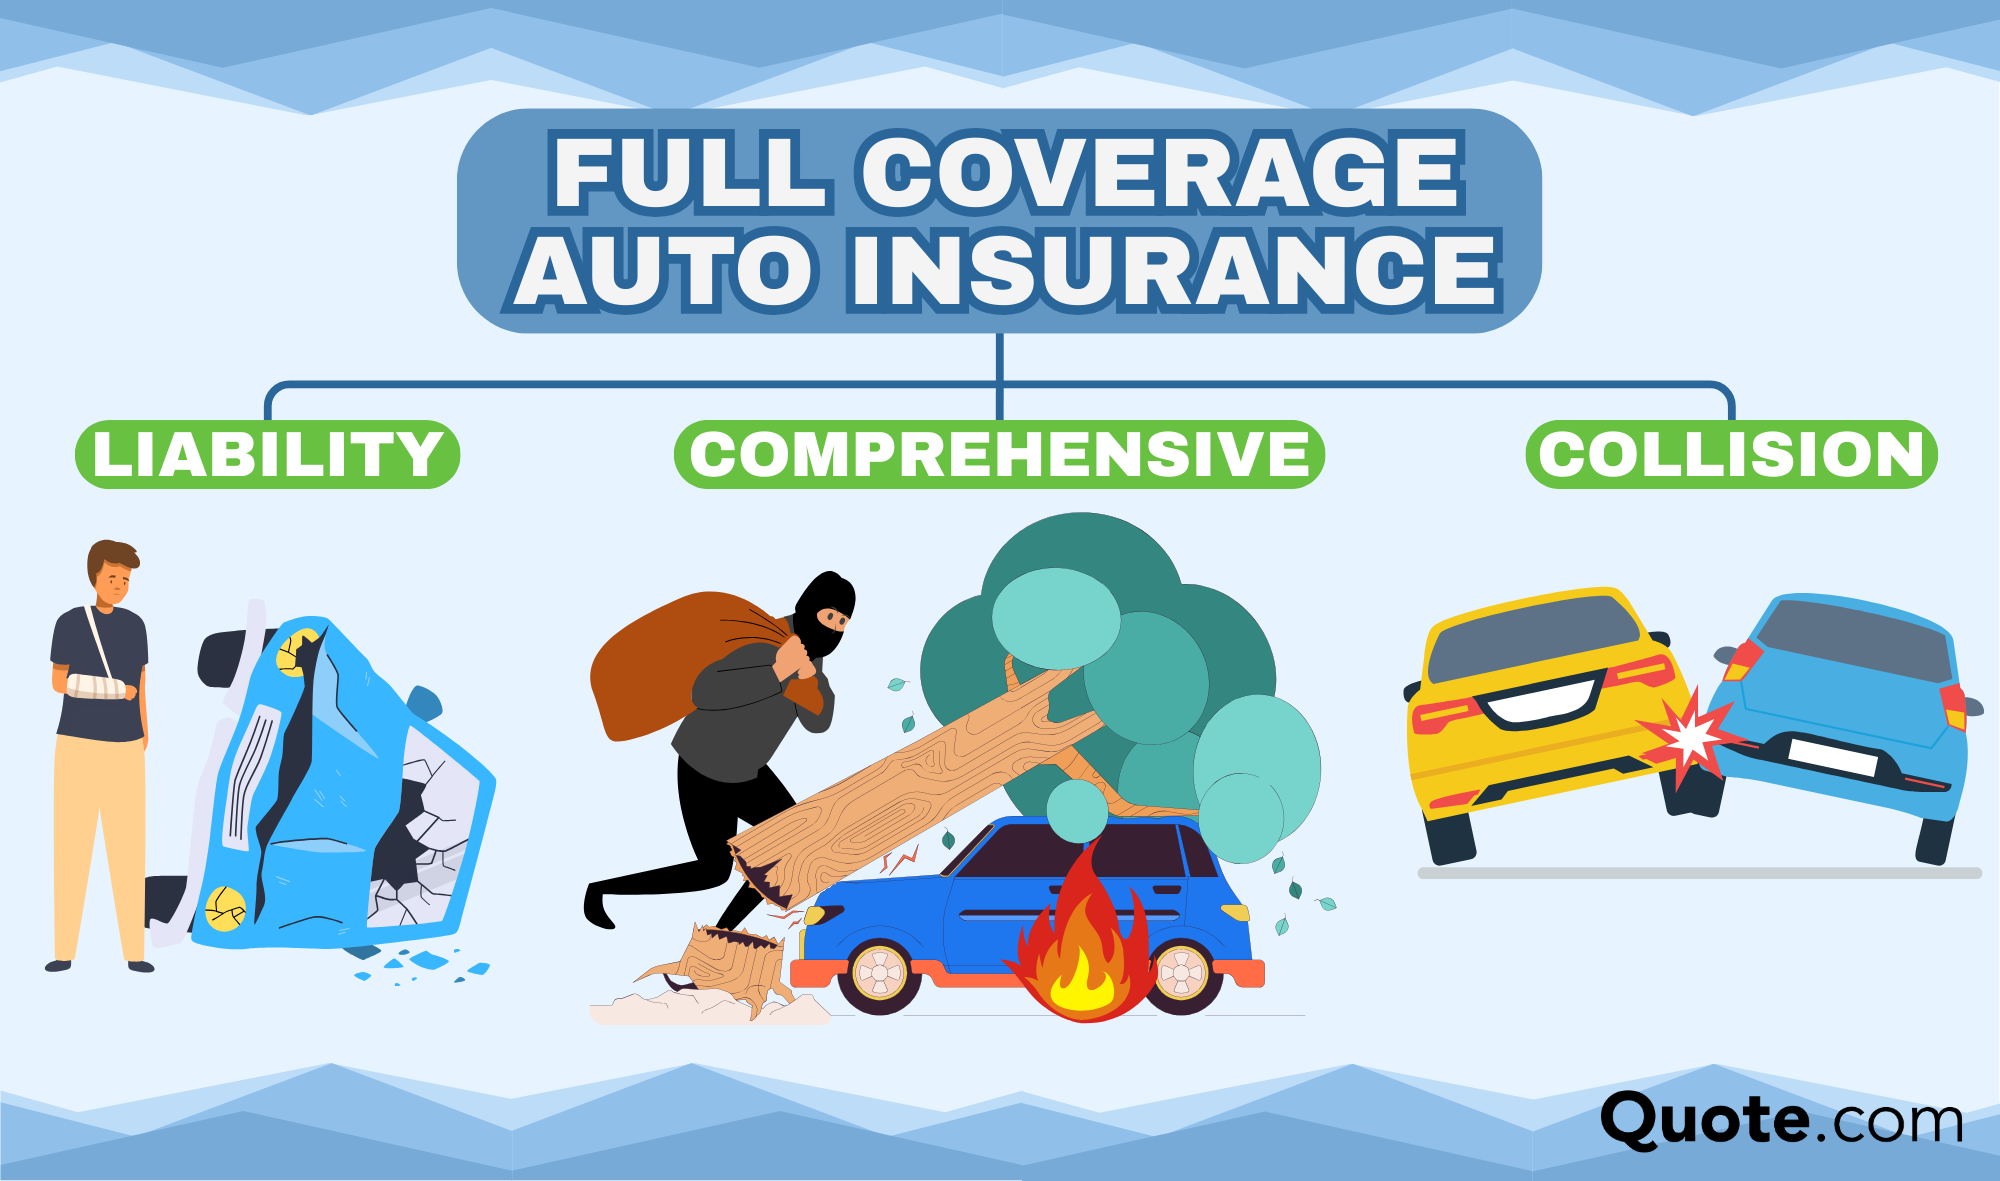
- Liability Coverage: Pays for bodily injury and property damage you cause to others. This is legally mandated in nearly all jurisdictions. Purchasing limits higher than the state minimum—such as 100/300/100 (thousands of dollars in bodily injury per person, per accident, and property damage)—provides essential protection without dramatically increasing your bill.
- Collision Coverage: Pays for damage to your own vehicle resulting from a collision with another car or object, regardless of fault.
- Comprehensive Coverage: Protects against non-collision incidents such as theft, fire, vandalism, animal strikes, or weather events like hail and floods.
- Uninsured/Underinsured Motorist Coverage: Steps in if you are hit by a driver who carries no insurance or lacks adequate limits to cover your medical bills and car repairs.
If you drive an older vehicle with a low market value—typically worth less than 10 to 15 times the annual cost of comprehensive and collision coverage—it makes financial sense to drop these coverages entirely. The payout from an insurance claim on an old car rarely justifies the continuous premium payments.

Comparing Auto Insurance Types and Cost Structures
| Coverage Type | Primary Purpose | Recommended For | Cost Impact |
|---|---|---|---|
| State Minimum Liability | Meets legal driving requirements only | Old cars with no loan and low personal assets | Lowest upfront cost, highest personal risk |
| Standard Liability (100/300/100) | Protects personal assets from major lawsuits | Most standard drivers with average savings | Moderate cost, balanced protection |
| Full Coverage (Liability + Comp/Collision) | Protects your car and others in all scenarios | Newer cars, financed vehicles, or daily commuters | Higher cost, comprehensive security |
| High-Deductible Full Coverage | Lowers monthly payments via higher out-of-pocket risk | Drivers with emergency savings seeking lower premiums | Lower monthly cost, higher financial risk during a claim |
Practical Strategies to Lower Your Car Insurance Bill
Securing affordable rates requires proactive steps. Insurance companies rarely offer their lowest rates by default; you must qualify for them and ask for them.
1. Shop Around and Compare Quotes Regularly
Insurance markets fluctuate, and pricing models change frequently. Experts recommend gathering quotes from at least three different carriers—including major national brands and reputable regional insurers—every one to two years. Never assume your current provider is giving you the best deal simply because you have been with them for a long time.
2. Bundle Your Policies
Most insurers offer multi-policy discounts if you purchase your auto insurance alongside homeowners, renters, life, or umbrella insurance. Bundling simplifies your financial management while typically slicing 10% to 25% off your auto premium.
3. Maximize Specialized Discounts
Insurers provide a wide array of discounts that drivers often overlook. Ask your agent about eligibility for:
- Good Driver Discounts: Maintaining a clean record for three to five consecutive years.
- Safety Equipment Discounts: Having factory-installed anti-lock brakes, airbags, daytime running lights, and passive restraint systems.
- Anti-Theft Discounts: Equipping your vehicle with tracking systems, alarms, or steering wheel locks.
- Good Student Discounts: Maintaining a B average or higher in high school or college.
- Low-Mileage Discounts: Driving significantly fewer miles than the national average, often tracked via traditional odometer readings or telematics monitoring apps.
4. Optimize Deductibles
If you have an emergency fund capable of covering unexpected expenses, raise your comprehensive and collision deductibles from $500 to $1,000. This adjustment can immediately reduce your physical damage premiums by 10% to 15%.
Managing Special Risk Profiles and Difficult Situations
Certain drivers face steep insurance costs due to objective risk factors. If you fall into one of these categories, finding affordable coverage requires targeted strategies.
High-Risk Drivers
Drivers with a DUI conviction, multiple speeding tickets, or a lapse in coverage are often classified as high-risk, leading to non-renewal or exorbitant quotes from standard carriers. In these cases, look toward specialized non-standard insurance companies that cater specifically to high-risk profiles. Additionally, many states operate assigned-risk plans (automobile insurance plans) that guarantee coverage for drivers who cannot find insurance on the open market, though this should be treated as a last resort due to higher costs.
Young and Teen Drivers
Adding a teenager to an auto insurance policy is notoriously expensive. To mitigate these costs, keep the teen on your family policy rather than buying a separate standalone policy, ensure they take an accredited defensive driving course, and assign them to the least expensive, safest vehicle in the household. Many insurers also offer telematics discounts where a mobile app monitors driving habits like speed and braking smoothness, rewarding safe teenage drivers with lower rates.
Step-by-Step Action Plan to Secure Affordable Coverage
- Pull Your Driving Record: Review your Motor Vehicle Report (MVR) for errors before applying for insurance. Disputing and correcting an incorrect speeding ticket can instantly lower your quotes.
- Determine Your Needs: Assess your car's value and your personal asset protection requirements to establish appropriate liability limits and deductible thresholds.
- Collect Multiple Quotes: Use online comparison tools or contact independent insurance agents who can pull quotes from dozens of carriers simultaneously.
- Verify Discounts: Explicitly ask each quoting agent to review the discount checklist—including paperless billing, auto-pay, safety features, and professional affiliations.
- Review Annually: Set a calendar reminder to re-evaluate your policy every twelve months to catch new rate adjustments or qualify for newly available discounts.
Frequently Asked Questions
Does my credit score really affect the cost of my auto insurance?
Yes, in most states, insurers use a credit-based insurance score to evaluate risk. Statistical data shows a strong correlation between credit health and the likelihood of filing insurance claims. However, California, Hawaii, Massachusetts, and Michigan prohibit or heavily restrict the use of credit scores in determining auto insurance rates.
Is it cheaper to pay my auto insurance in full or monthly?
Paying your auto insurance premium in full for a six-month or annual term is almost always cheaper. Monthly payment plans typically include installment fees, service charges, or interest fees that can add up to an extra 5% to 10% to your overall annual cost.
Will filing a minor insurance claim cause my rates to go up?
It depends on your insurer and whether you have "accident forgiveness" coverage. If you cause an accident with minor property damage, paying out-of-pocket for the repair may be cheaper than filing a claim that triggers a multi-year premium surcharge. Many companies also waive rate increases for your first minor at-fault accident if you have a clean history.
How can telematics or tracking devices lower my insurance bill?
Telematics programs use a plug-in device or a smartphone app to monitor your real-time driving habits, including your speed, rapid acceleration, hard braking, and phone usage while driving. If the data shows you are a safe, low-risk driver, you can earn discounts of up to 30% or more, though aggressive driving habits can occasionally cause rates to increase.
What should I do if my insurance company drops me?
If your insurer non-renews or cancels your policy, do not panic and do not drive uninsured. Insurers typically drop drivers due to accidents, traffic violations, or changes in company underwriting guidelines. Contact an independent insurance broker immediately to shop your profile across specialized non-standard carriers that routinely write policies for drivers with checkered records.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
