Blue Cross Blue Shield GLP-1 Coverage: What to Expect and How to Navigate Your Benefits
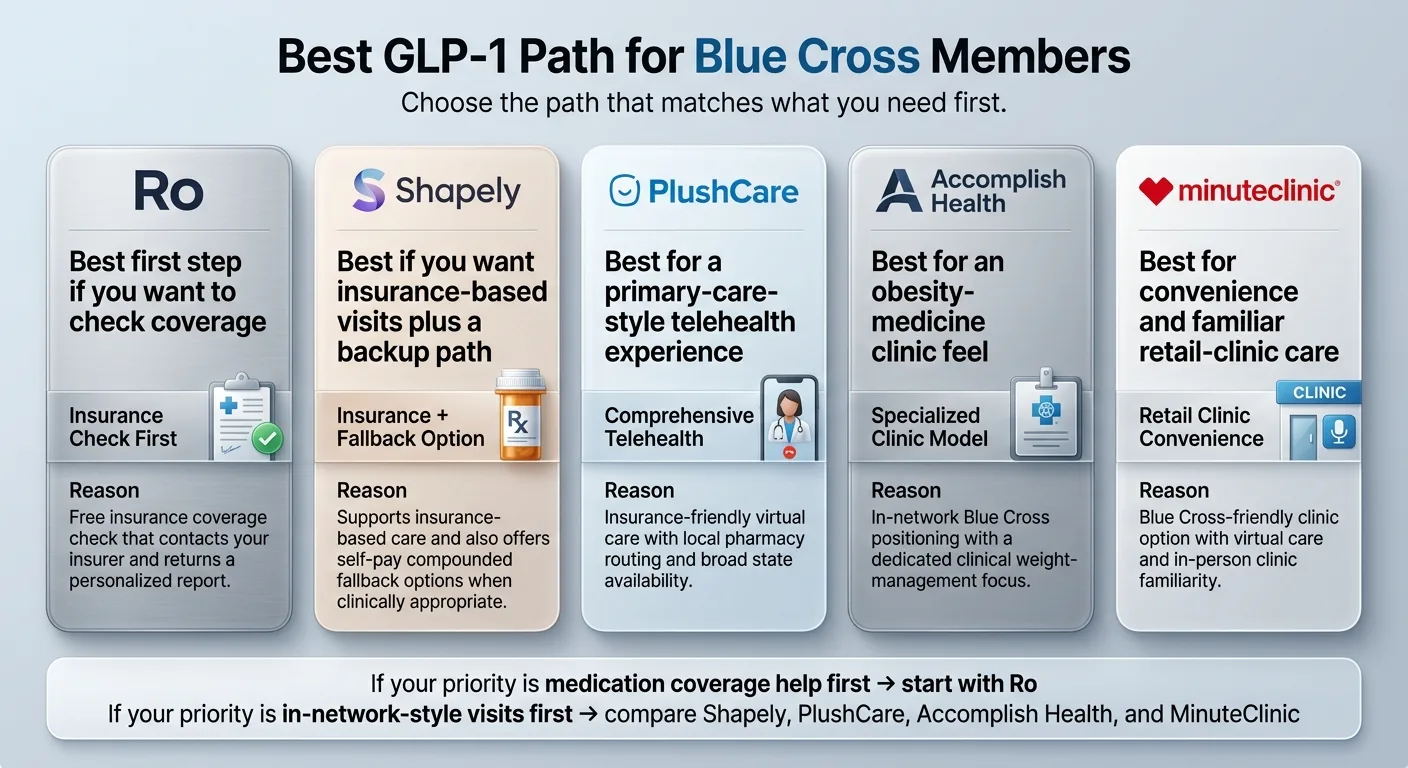
Navigating Blue Cross Blue Shield (BCBS) GLP-1 coverage requires understanding your specific plan's formulary, prior authorization criteria, and the distinction between treatments prescribed for type 2 diabetes versus chronic weight management. Because BCBS operates as a network of independently operated, state-based health insurance companies, specific coverage policies, tier placements, and out-of-pocket costs vary significantly depending on your geographic location, employer-sponsored plan design, or individual marketplace tier.
Securing coverage for glucagon-like peptide-1 receptor agonists—such as semaglutide, tirzepatide, and liraglutide—demands meticulous attention to clinical documentation, plan formularies, and the appeals process. As utilization management criteria tighten across the insurance landscape, understanding the mechanics of how BCBS evaluates these therapies is essential for managing costs and maintaining continuous access to your prescribed treatment regimen.
Understanding the Landscape of BCBS GLP-1 Coverage
Glucagon-like peptide-1 receptor agonists have transformed the treatment landscape for type 2 diabetes and chronic weight management. However, health insurance providers face substantial financial pressures due to the high list prices and immense popularity of these medications. Blue Cross Blue Shield plans approach these drugs through a framework that strictly separates clinical indications, primarily distinguishing between glycemic control for diabetes mellitus and weight loss for obesity or overweight status with comorbid conditions.
Because Blue Cross Blue Shield is not a single national entity but rather a federation of 33 independent and locally operated companies (such as Anthem, BCBS of Texas, BCBS of Illinois, and Capital Blue Cross), benefits are localized. A policy that covers weight-loss formulations seamlessly in California may exclude them entirely in a standard employer-sponsored plan in another region. Reviewing your specific plan documents, formulary drug list, and summary of benefits is the foundational step in determining your coverage parameters.
Formulary Tiers and Drug Classifications
Formularies dictate how much you will pay for a medication based on its tier assignment. Most BCBS plans categorize drugs into distinct tiers, ranging from preferred generic options to specialty tiers that carry high coinsurance rates or fixed copayments:
- Tier 1 / Preferred Generics: Typically lowest cost, though true generic GLP-1 options are currently limited.
- Tier 2 / Preferred Brand Name: Includes established formulations with lower out-of-pocket expenses.
- Tier 3 / Non-Preferred Brand Name: Requires higher cost-sharing or explicit exception requests.
- Tier 4 / Specialty or Excluded: Often houses medications intended strictly for cosmetic weight loss or newer agents requiring rigorous prior authorization.
Formulary exclusions are common for weight-loss medications. Many group health plans purchased by employers choose to completely exclude anti-obesity medications (AOMs) to keep premium costs manageable, even if the base medical policy allows coverage for diabetes management.
Clinical Criteria: Prior Authorization and Step Therapy
Getting a prescription filled for a GLP-1 medication through BCBS almost invariably triggers a prior authorization (PA) requirement. A prior authorization is a formal evaluation process where your prescribing physician must submit clinical documentation proving that the medication is medically necessary according to BCBS guidelines.
For type 2 diabetes indications (e.g., managing blood glucose levels and reducing cardiovascular risk), approval criteria generally focus on a documented diagnosis of type 2 diabetes, often requiring a baseline HbA1c measurement and documentation that lifestyle modifications alone have been insufficient.
For weight management indications (e.g., Wegovy, Saxenda, or Zepbound), the criteria are significantly more rigorous and specific. BCBS plans typically require meeting all of the following parameters:
- Body Mass Index (BMI) Thresholds: An initial adult BMI of 30 kg/m² or greater, or 27 kg/m² or greater in the presence of at least one weight-related comorbid condition, such as hypertension, dyslipidemia, type 2 diabetes, or obstructive sleep apnea.
- Comprehensive Lifestyle Program: Documentation that the patient has actively participated in a structured, multidisciplinary weight management or lifestyle modification program (including diet and exercise counseling) for a specified duration, often ranging from three to six months prior to starting pharmacotherapy.
- Step Therapy Requirements: Many plans enforce step therapy, meaning you must try and fail older, less expensive preferred alternatives (such as metformin, or specific older classes of weight-loss or diabetes medications) before BCBS will authorize coverage for a newer GLP-1 agent.

Cost-Sharing, Copays, and Out-of-Pocket Expenses
Even when a GLP-1 medication is successfully approved through prior authorization, your financial responsibility can vary wildly based on your deductible, copay structure, or coinsurance percentage. Specialty tier medications often carry coinsurance rates ranging from 20% to 50% of the allowed drug cost rather than a flat copayment, which can translate to hundreds of dollars out-of-pocket each month.
| Coverage Scenario | Typical Requirements | Primary Financial Impact | Common Challenges |
|---|---|---|---|
| Type 2 Diabetes Indication | Documented ICD-10 code for diabetes, HbA1c records, chart notes. | Standard brand-name copay or lower-tier specialty coinsurance. | Formulary tier changes moving drugs to non-preferred status. |
| Weight Management Indication | BMI verification, weight-related comorbidities, supervised diet history. | High coinsurance, strict accumulation toward deductibles, potential exclusion. | Complete plan exclusion of anti-obesity medications by employer choice. |
| Commercial Exception Request | Letter of medical necessity, failure of step-therapy agents, physician attestation. | Variable; dependent on independent medical review board decisions. | High denial rates requiring persistent multi-stage appeals. |
| Employer-Sponsored Opt-Out | Dependent on employer group contract rather than baseline BCBS policy. | Patient responsible for 100% of retail cash price unless manufacturer savings cards apply. | Lack of recourse through standard insurance appeals channels. |
Understanding your deductible phase is critical. If your pharmacy benefits are subject to a combined medical and pharmacy deductible, you will pay the full negotiated retail rate of the medication out of pocket until your deductible is fully met, after which coinsurance or copayments take effect.
Step-by-Step Guide to Verifying and Securing Coverage
Proactive navigation can drastically reduce the time it takes to get your prescription approved. Follow this sequential roadmap to verify your benefits and mitigate coverage hurdles:
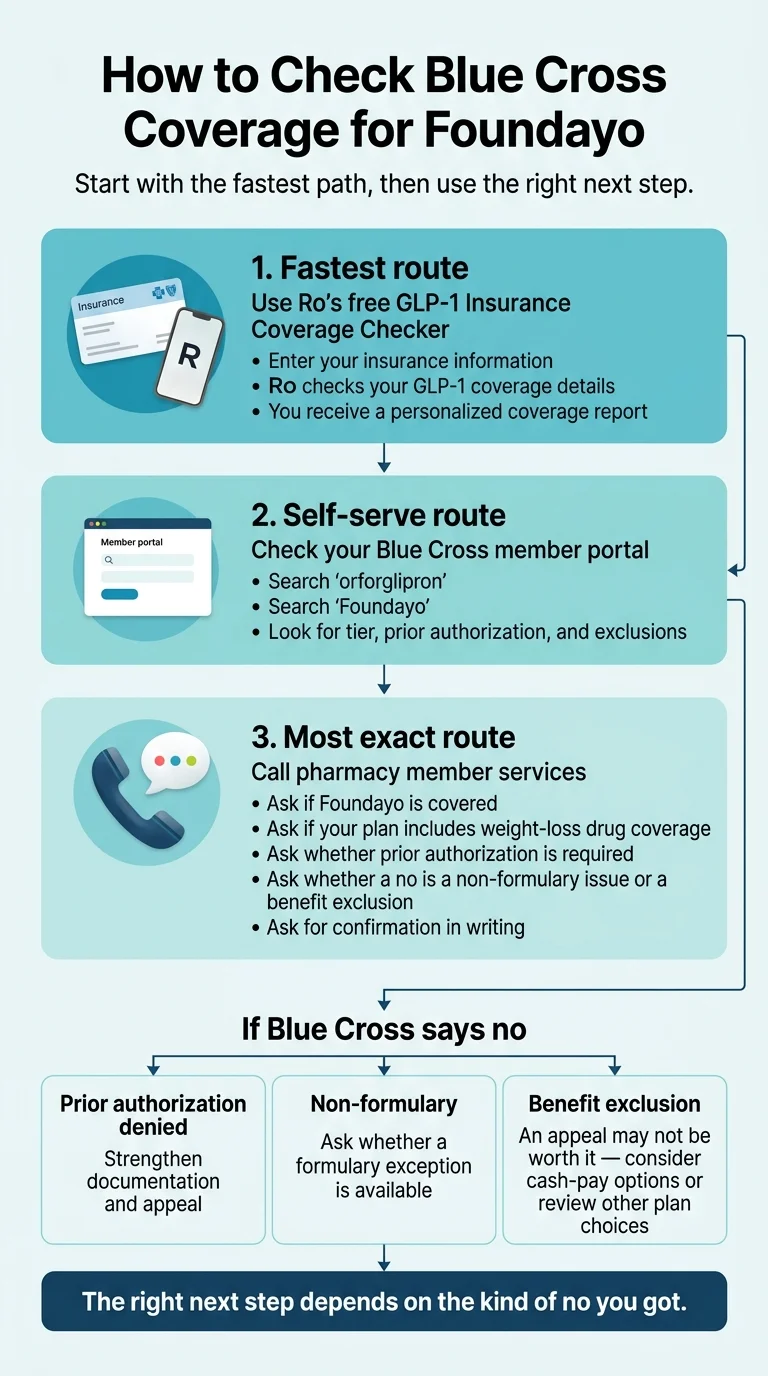
- Request the Formulary Document: Log into your specific BCBS member portal or call the pharmacy services number listed on the back of your insurance card. Ask for the current year formulary list and verify whether your specific medication is listed, excluded, or requires prior authorization.
- Confirm Employer Plan Riders: If your insurance is provided through an employer, ask your human resources or benefits department specifically if your health plan includes an exclusion rider for anti-obesity medications. This clarifies whether a denial is based on standard BCBS clinical guidelines or a specific corporate choice by your employer.
- Collaborate with Your Prescriber: Schedule a detailed consultation with your physician or endocrinologist. Ensure they have your complete medical history, accurate baseline BMI measurements, and documentation of any previous medication trials or lifestyle interventions.
- Submit the Prior Authorization: Have your medical provider submit the prior authorization paperwork promptly, attaching all necessary laboratory results and clinical chart notes that directly address BCBS’s published medical policy guidelines.
- Track the Review Timeline: Monitor the status of the PA through your member portal. Standard reviews typically take between 24 hours to 15 business days depending on state regulations and whether an urgent request is warranted.
Handling Denials and Filing an Appeal
A prior authorization denial is not necessarily the final word on your coverage. Insurance companies frequently issue initial denials due to missing administrative data, incomplete clinical notes, or failure to explicitly meet every single line item of their medical policy.
If your request is denied, review the official denial letter carefully. The letter must legally outline the exact clinical reason for the adverse determination and provide instructions on how to file an appeal.
- Level 1 Appeal (Internal Review): This involves submitting additional clinical documentation, a letter of medical necessity written by your physician, and any peer-reviewed literature supporting the off-label or specialized use of the medication for your unique clinical presentation.
- Level 2 Appeal (External Review): If the internal appeal is upheld, most members have the legal right to request an independent external review. An independent third-party medical expert evaluates the case against accepted clinical standards, bypassing the insurer's internal policies. Their decision is generally binding on the insurance company.
Alternative Financial Strategies When Coverage is Denied
When BCBS completely denies coverage—particularly for weight-loss indications or due to strict employer plan exclusions—patients often have to explore alternative financial pathways:
- Manufacturer Savings and Copay Cards: Many pharmaceutical manufacturers offer commercial savings cards or copay assistance programs that can significantly reduce out-of-pocket costs for commercially insured patients. Note that these programs are legally prohibited for patients enrolled in federal healthcare programs like Medicare or Medicaid.
- Patient Assistance Programs (PAP): Individuals meeting specific financial hardship and income thresholds may qualify for assistance programs directly through drug manufacturers, providing medications at little to no cost.
- Flexible Spending Accounts (FSA) and Health Savings Accounts (HSA): Prescribed medications approved by a physician for the treatment of a specific medical condition qualify as eligible medical expenses, allowing you to use pre-tax dollars to cover your out-of-pocket costs.
Frequently Asked Questions
Does Blue Cross Blue Shield automatically cover Wegovy and Zepbound?
No. Coverage is not automatic. Coverage depends entirely on your specific state BCBS affiliate, your specific plan type (individual vs. employer-sponsored), and whether your plan includes a specific exclusion for weight-loss medications. Prior authorization is universally required.
What is the difference between diabetes coverage and weight-loss coverage with BCBS?
BCBS plans generally view type 2 diabetes management as a standard medical necessity, making coverage for agents like Ozempic or Mounjaro more attainable when diagnosed properly. Conversely, weight management indications (Wegovy, Zepbound) are often classified as lifestyle or anti-obesity benefits, which many employers choose to exclude from their plan contracts.
How long does the BCBS prior authorization process take?
Standard prior authorization reviews typically take between 3 to 14 business days. If your physician certifies that a delay would seriously jeopardize your life, health, or ability to regain maximum function, expedited reviews are often completed within 24 to 72 hours.
Can I appeal a denial if my employer excluded anti-obesity medications?
Unfortunately, if your employer group contract explicitly excludes anti-obesity medications from the plan design, standard insurance appeals through BCBS rarely succeed. In these instances, relief must typically be sought through your employer’s benefits department during the annual open enrollment period by selecting a different tier or plan option if available.
What should I do if my prior authorization expires?
Prior authorizations are typically granted for a limited time frame, such as 6 to 12 months. Before your approval expires, your prescribing physician must submit a continuation-of-care prior authorization demonstrating that you have tolerated the medication well and achieved the clinical benchmarks (such as sustained weight loss or glycemic control) required by BCBS.
Next Actions and Strategic Recommendations
To maximize your chances of securing and maintaining Blue Cross Blue Shield GLP-1 coverage, initiate a direct dialogue with your healthcare provider well before your next prescription refill. Request that your clinic audit your medical records to ensure all documentation—including BMI histories, comorbidity diagnoses, and documented step-therapy failures—is complete and ready for submission. Simultaneously, call your BCBS member services representative to confirm your exact plan formulary tier and specific prior authorization criteria, ensuring you approach the approval process with absolute clarity on your plan's rules.
Image Gallery
Select an image to open it in a new tab.



Lars Thomsen
Global Labor Markets and Economic Strategy Editor
