Auto-Owners life insurance provides financial protection through term, whole, and universal life policies, sold exclusively via independent agents. In 2026, it remains a top-tier choice for those seeking high financial stability (A.M. Best A++ rating) and significant multi-policy discounts when bundling life coverage with existing auto or homeowners insurance policies.
Life insurance is often the most overlooked component of a personal financial plan, yet it serves as the ultimate safety net for your survivors. Auto-Owners Insurance, a Fortune 500 company founded in 1916, has built a reputation for localized service and long-term reliability. Unlike many modern "insurtech" firms that rely on algorithms and direct-to-consumer digital sales, Auto-Owners operates through a network of independent agents across 26 states. This model ensures that when you seek to have "auto-owners life insurance explained," you are receiving advice tailored to your specific jurisdictional laws and personal financial goals.
The Core Philosophy of Auto-Owners Life Insurance
Auto-Owners approaches life insurance through the lens of comprehensive protection. Their "Life Multi-Policy Discount" is one of the most aggressive in the industry, often reducing premiums on other lines of business—like your car or home insurance—so significantly that the life insurance policy essentially pays for itself.
The company focuses on three primary objectives:
- Income Replacement: Ensuring that if a primary earner passes away, the family can maintain their standard of living.
- Debt Clearance: Providing immediate liquidity to pay off mortgages, car loans, and credit card balances.
- Legacy and Estate Planning: Utilizing permanent life products to transfer wealth to the next generation or cover estate taxes.
Types of Auto-Owners Life Insurance Policies
In 2026, Auto-Owners offers a robust portfolio of life products. Understanding the difference between these options is critical to selecting a policy that aligns with your timeline and budget.
Term Life Insurance
Term life insurance is the most straightforward and affordable form of coverage. It provides protection for a specific period, typically ranging from 10 to 30 years.
- Level Term: Your premiums remain the same for the entire duration of the term. This is ideal for young families who need high coverage amounts at a low cost during their peak debt years (e.g., while paying off a mortgage or raising children).
- Renewability: Most Auto-Owners term policies allow you to renew coverage on an annual basis after the initial term expires, though premiums will increase significantly as you age.
- Conversion Privilege: A standout feature of Auto-Owners term policies is the ability to convert to a permanent policy without undergoing a new medical exam. This is vital if you develop a health condition during your term and want to secure lifelong coverage later.
Whole Life Insurance
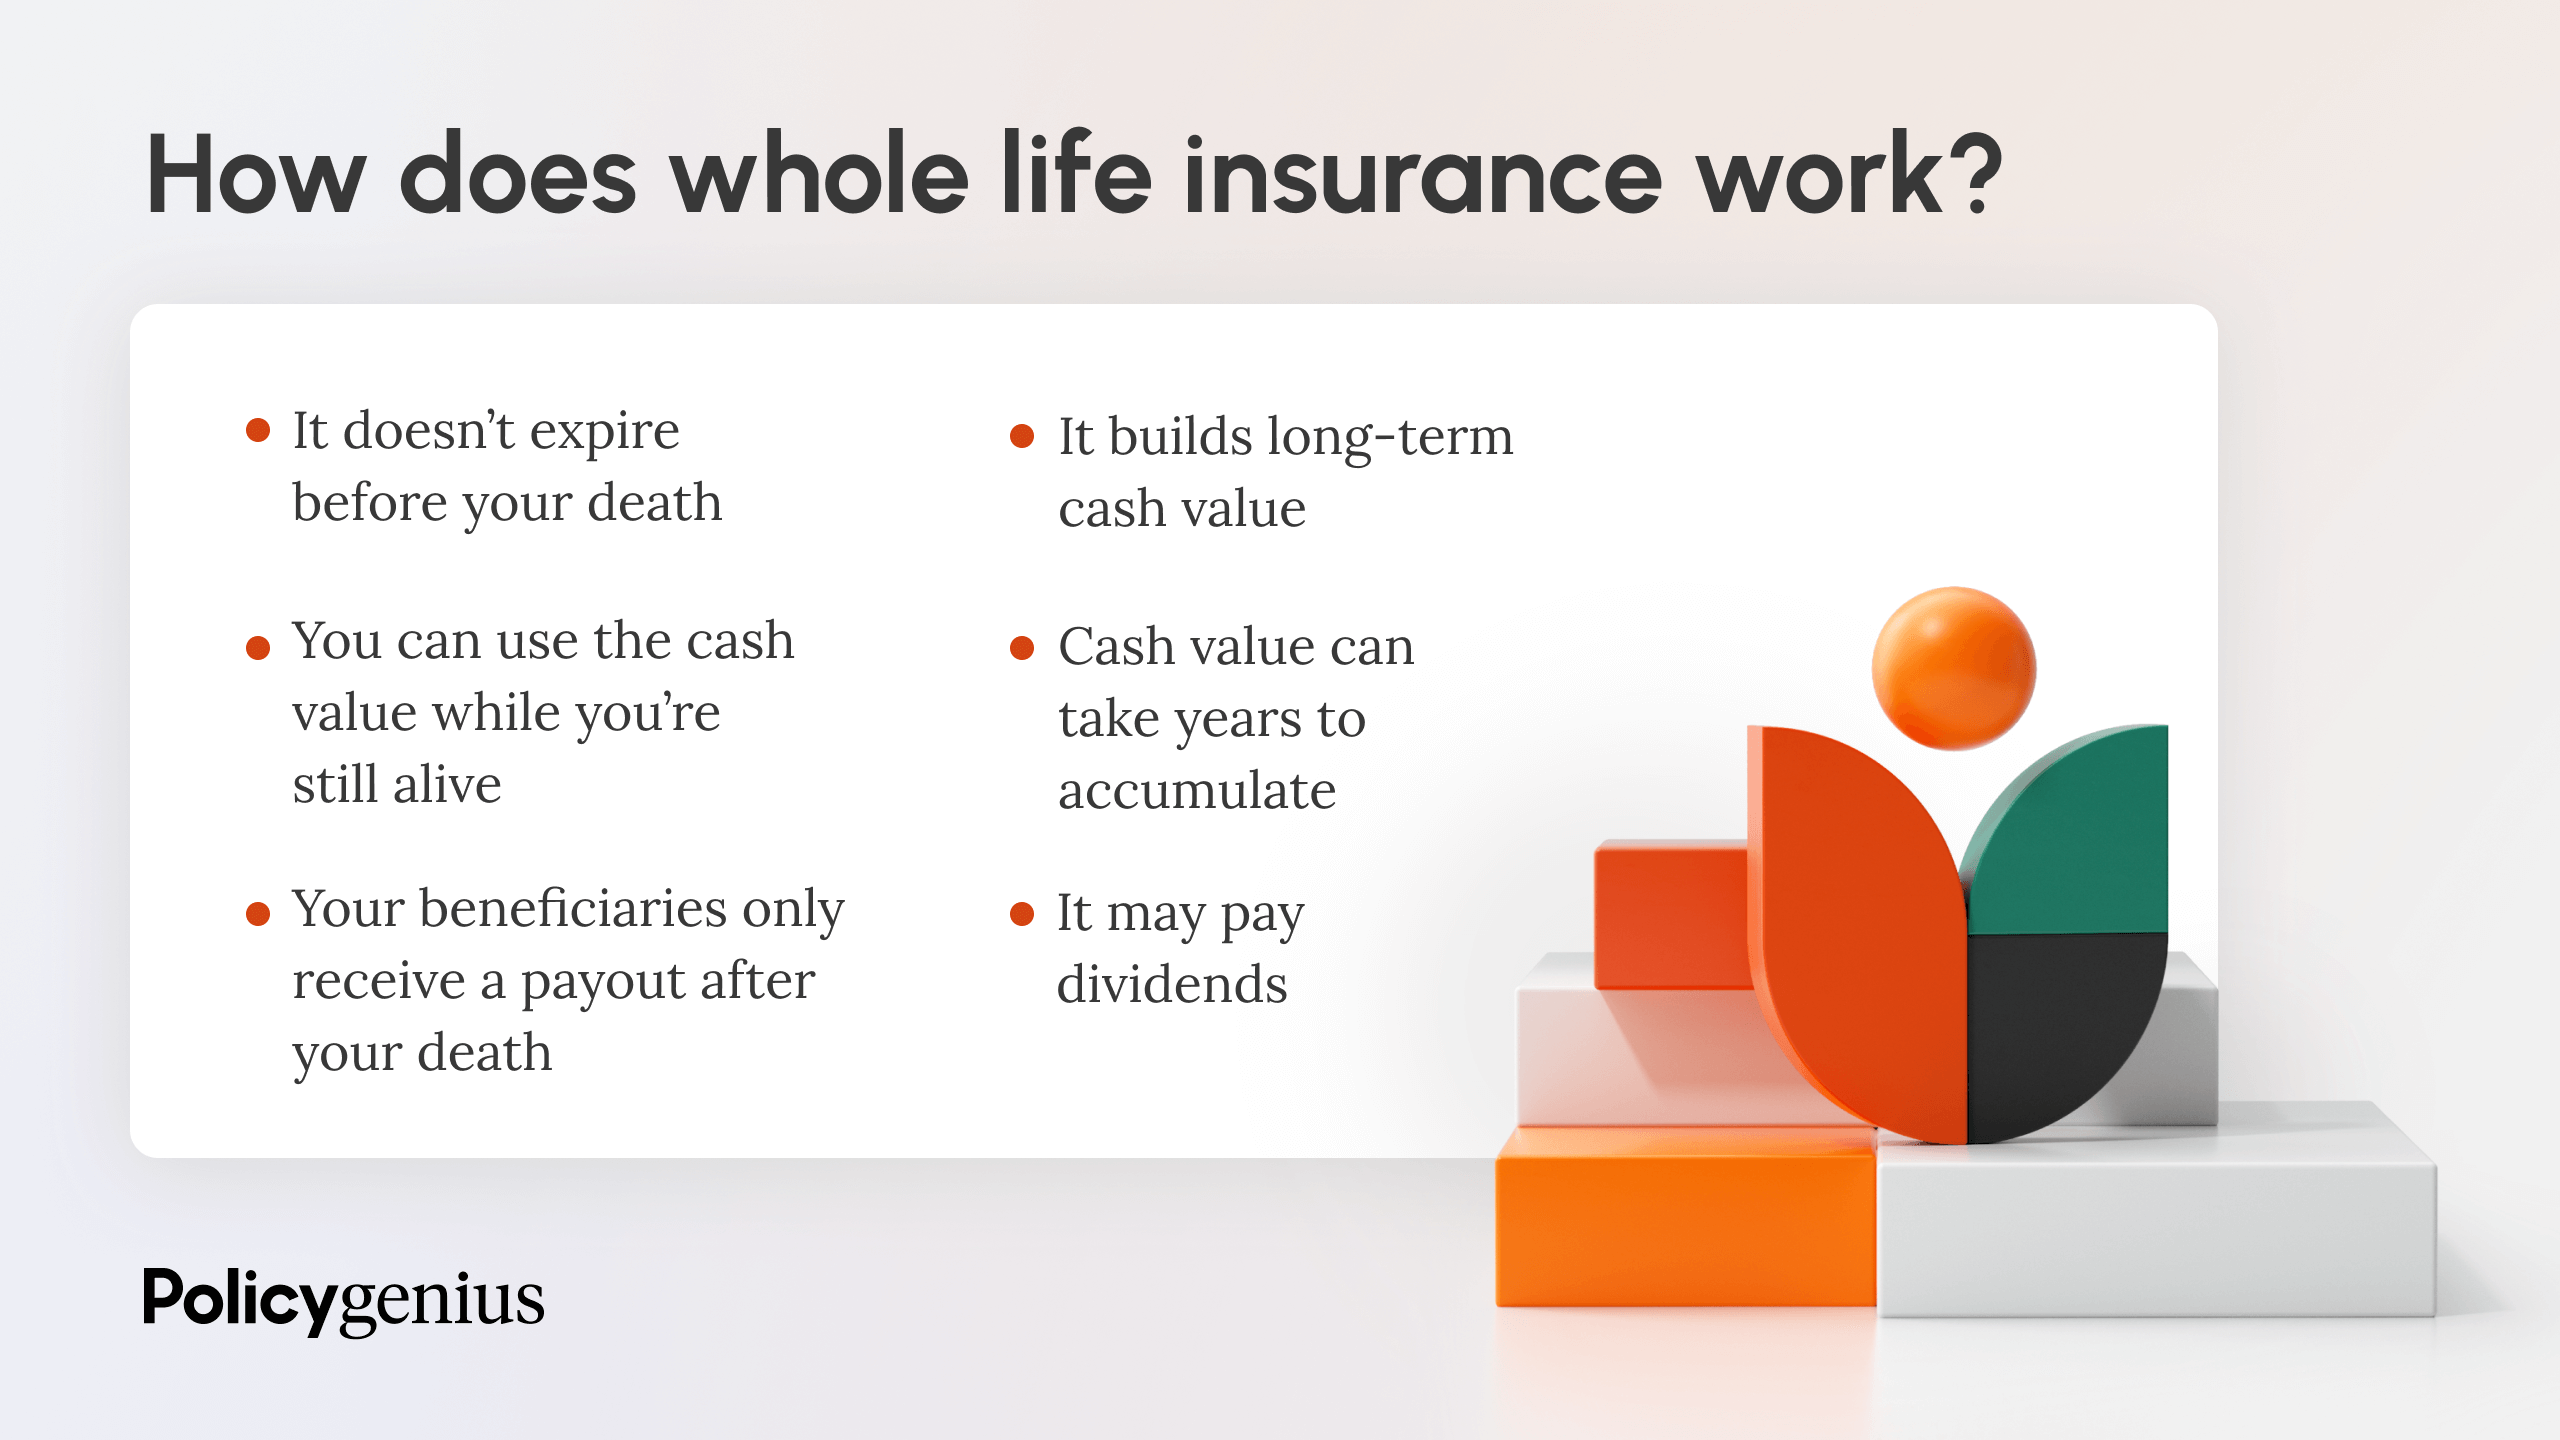
Whole life insurance is a form of permanent coverage that lasts your entire life, provided premiums are paid. It is more expensive than term insurance because it builds cash value.
- Fixed Premiums: Your payment never increases, regardless of changes in your health or the economy.
- Cash Value Accumulation: A portion of your premium is diverted into a savings component that grows at a guaranteed rate. You can borrow against this cash value or surrender the policy for its value in the future.
- Paid-Up Options: Auto-Owners offers specialized whole life products, such as "Paid-Up at 65," where you pay higher premiums during your working years so that the policy is fully funded by the time you retire.
Universal Life Insurance
Universal life insurance offers more flexibility than whole life. It is designed for individuals who want permanent protection but need the ability to adjust their premiums or death benefits as their financial situation evolves.
- Adjustable Premiums: Within certain limits, you can increase or decrease your premium payments.
- Flexible Death Benefits: You can often change the amount of the death benefit to match your current needs.
- Interest-Sensitive Growth: The cash value in a universal life policy grows based on current market interest rates, which can lead to higher growth than whole life in a high-interest environment, though it also carries more risk if rates fall.
Specialized Coverage: Simplified Senior Life
For older adults who may have difficulty qualifying for traditional underwritten policies, Auto-Owners provides a "Simplified Senior Life" product. This is often used for final expense planning (burial insurance).
This product typically features:
- Minimal Underwriting: There is no full medical exam; instead, coverage is based on a series of health questions.
- Lower Coverage Limits: Usually capped at lower amounts (e.g., $10,000 to $50,000) intended to cover funeral costs and small remaining debts.
- Fixed Benefits: The death benefit does not decrease over time, and the policy builds modest cash value.
Comparing Auto-Owners Life Insurance Options
| Feature | Term Life | Whole Life | Universal Life |
|---|---|---|---|
| Duration | Temporary (10-30 years) | Permanent (Lifetime) | Permanent (Lifetime) |
| Premium Cost | Lowest | Highest | Moderate/Flexible |
| Cash Value | None | Guaranteed Growth | Market-Linked Growth |
| Death Benefit | Fixed | Fixed | Flexible/Adjustable |
| Best For | Debt protection & young families | Estate planning & lifelong security | Wealth transfer & flexible budgets |
| Conversion | Usually available | N/A | N/A |
The Multi-Policy Discount Advantage
One of the most compelling reasons to choose Auto-Owners is their "Life Multi-Policy Discount." Unlike many competitors that offer a small 2% or 3% discount for bundling, Auto-Owners often applies the discount to the more expensive policies, such as your auto or homeowners insurance.
For example, if you are paying $3,000 a year for home and auto insurance, adding a $20-per-month term life policy might trigger a 5% to 10% discount on your existing premiums. In some cases, the total savings on your home and auto policies can exceed the cost of the life insurance premium itself. This effectively allows you to secure life insurance at a "net-zero" cost or even a slight profit in terms of total household cash flow.
Eligibility and the Underwriting Process
Auto-Owners requires an application through an independent agent. Because they prioritize precision in pricing, the underwriting process is thorough.
- The Application: Your agent will collect data on your age, lifestyle, occupation, and health history.
- Medical Examination: For many policies, a "paramed" exam is required. A technician will visit your home or office to collect blood and urine samples and record your height, weight, and blood pressure.
- Attending Physician Statement (APS): If you have a history of chronic illness, Auto-Owners may request records from your doctor.
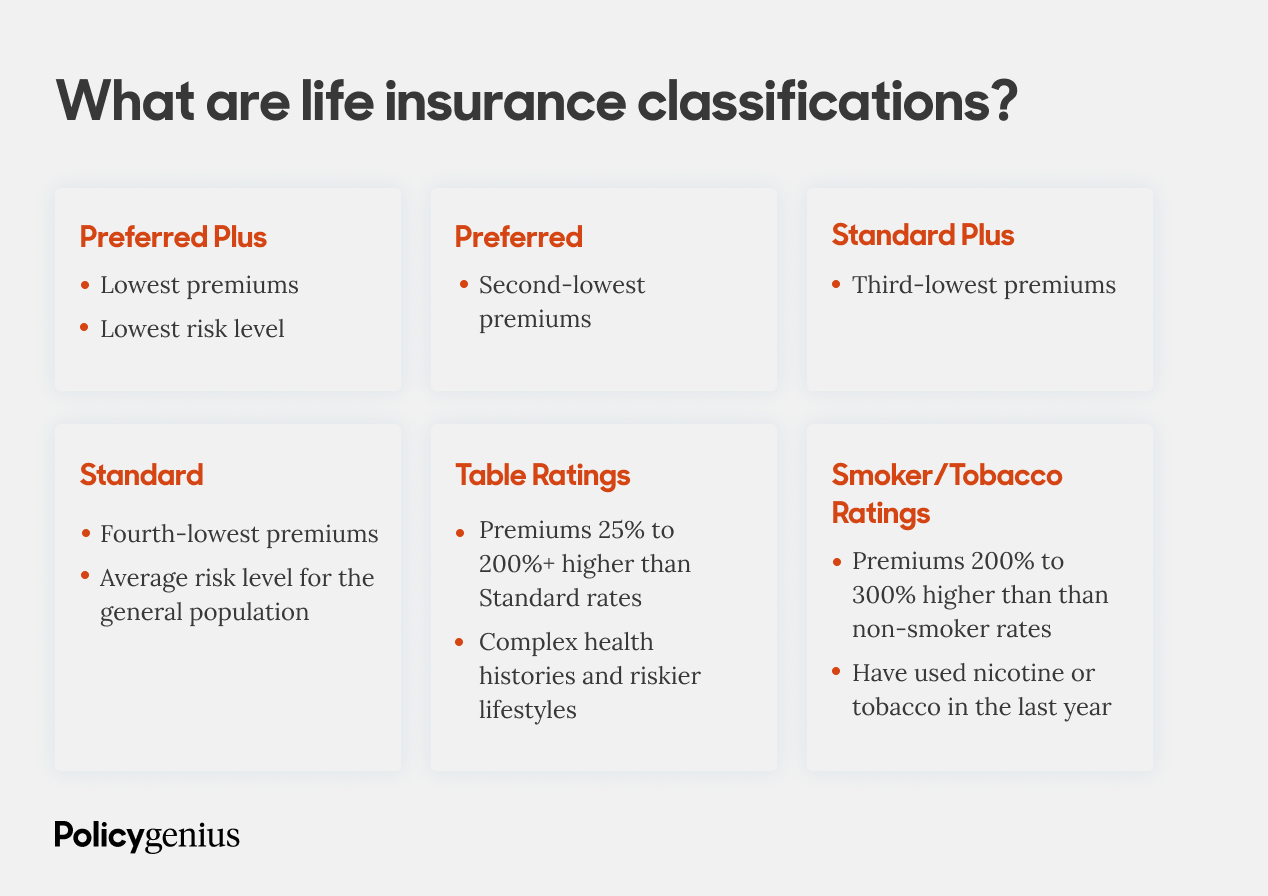
- Rating Classes: Based on the results, you will be assigned a rating class (e.g., Preferred Plus, Preferred, Standard, or Substandard). This rating directly determines your premium.
As of 2026, Auto-Owners has integrated more "accelerated underwriting" for healthy individuals applying for lower face amounts, which may allow some applicants to skip the medical exam entirely based on data from prescription drug databases and motor vehicle reports.
Financial Strength and Reliability
When buying life insurance, you are making a contract that may not be executed for 40 or 50 years. Therefore, the company's financial solvency is paramount. Auto-Owners Insurance Company consistently earns the highest possible ratings from independent agencies:
- A.M. Best: A++ (Superior). This is the highest rating available and indicates a "Superior" ability to meet ongoing insurance obligations.
- Fortune 500: Consistently ranked among the largest corporations in the United States by total revenue.
- Comdex Rating: Usually scores in the high 90s (out of 100), reflecting a composite of all major rating agencies.
These ratings provide peace of mind that the company will have the liquidity to pay death benefits regardless of the economic climate in 2026 and beyond.
How to File a Claim with Auto-Owners
The claims process is where the value of an independent agent becomes most apparent. When a policyholder passes away, the beneficiaries do not have to navigate a complex corporate call center alone.
- Step 1: Contact the Local Agent. The agent who sold the policy is typically the first point of contact. They assist in gathering the necessary documentation.
- Step 2: Submit Proof of Loss. This primarily involves a certified copy of the death certificate and a completed claimant statement.
- Step 3: Review and Payment. Auto-Owners is known for a relatively fast claims turnaround, often processing and issuing payments within 7 to 14 business days once all documentation is received.
- Settlement Options: Beneficiaries can choose to receive a lump-sum check, an interest-bearing account, or structured installments (annuitization).
Common Mistakes to Avoid
When exploring Auto-Owners life insurance, avoid these frequent pitfalls:
- Under-insuring: Many people buy just enough to cover their mortgage, forgetting about inflation, college tuition for children, and the loss of the spouse's Social Security benefits.
- Waiting Too Long: Life insurance premiums increase with every year of age. Securing a policy while young and healthy locks in lower rates.
- Ignoring the Riders: Auto-Owners offers several "riders" or add-ons, such as the Waiver of Premium (which pays your bill if you become disabled) or the Guaranteed Insurability Rider (which lets you buy more coverage later without a health check). Failing to consider these can limit the policy's future utility.
- Assuming You Don't Qualify: Even with health conditions like diabetes or high blood pressure, an independent agent can often find an Auto-Owners product or rating class that fits, especially compared to "big box" insurers.
Frequently Asked Questions
Can I buy Auto-Owners life insurance online?
No. Auto-Owners maintains a strict commitment to the independent agency model. While you can view product information on their website, you must contact a local agent to receive a quote and submit an application. This ensures that a professional evaluates your needs and helps you navigate the underwriting process correctly.
What states is Auto-Owners life insurance available in?
Auto-Owners operates in 26 states, primarily across the Midwest and Southeast United States. If you move to a state where they do not sell new policies, your existing policy remains in force as long as premiums are paid, but you may need to manage the policy through their home office or a neighboring state's agent.
Is there a "grace period" if I miss a premium payment?
Yes, Auto-Owners typically provides a 31-day grace period for life insurance premiums. If the premium is paid within this window, the policy remains in full force. If the policy has cash value (like whole or universal life), the company may use an "Automatic Premium Loan" to pay the bill from the policy's equity to prevent a lapse.
Does Auto-Owners offer "Return of Premium" (ROP) term insurance?
In most jurisdictions, Auto-Owners offers an ROP rider for certain term lengths. This rider refunds 100% of the premiums you paid at the end of the term if you are still living. While this makes the monthly cost significantly higher, it functions as a form of forced savings.
How does the medical exam work in 2026?
The 2026 medical exam process is highly streamlined. For many applicants, it involves a mobile phlebotomist visiting their location for a 20-minute appointment. They check height, weight, pulse, and blood pressure, and collect a small blood and urine sample. Results are usually available to the applicant through a secure digital portal within a week.
Practical Recommendation
If you already have an auto or home insurance policy with Auto-Owners, your first step should be to ask your agent for a "Life-Multi-Policy" quote. The potential savings on your existing premiums can make the addition of life insurance an exceptionally high-value financial move.
For those not currently with Auto-Owners, this company is best suited for individuals who value long-term stability and a personal relationship with a local agent over the "do-it-yourself" digital experience. Begin by calculating your "Total Need" (Debt + Income Replacement + Final Expenses) and present this figure to an independent agent to compare the costs of a 20-year level term versus a flexible universal life policy.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
