
Securing auto insurance in the 60031 ZIP code, which primarily encompasses Gurnee, Illinois, requires an understanding of state-mandated minimum liability limits and the specific risk factors associated with Lake County’s traffic density and weather patterns. Residents must navigate Illinois Department of Insurance requirements while balancing premium costs against the need for comprehensive protection against regional variables like winter road conditions.
Understanding the Illinois Insurance Landscape
To operate a motor vehicle legally in the 60031 area, drivers must comply with the Illinois Vehicle Code. Unlike states with "no-fault" insurance laws, Illinois operates under a "tort" or "at-fault" system. This means that the driver found legally responsible for an accident is responsible for the damages caused to others. Consequently, insurance in Gurnee is not just a personal safeguard but a mandatory financial responsibility requirement to ensure that victims of accidents are compensated.
The state-mandated minimums are often viewed as a baseline rather than a recommendation. As of 2026, Illinois requires drivers to carry liability coverage with at least the following limits:
- $25,000 for bodily injury or death of one person in an accident.
- $50,000 for bodily injury or death of more than one person in an accident.
- $20,000 for damage to the property of others.
While these limits satisfy the state, they are frequently insufficient to cover the costs of modern vehicle repairs or significant medical bills resulting from a serious collision. Most financial advisors and insurance professionals in Northern Illinois recommend higher liability limits, often suggested at 100/300/50 coverage (100k bodily injury per person, 300k per accident, and 50k property damage), to protect personal assets from potential litigation in the event of an at-fault accident.
Regional Factors Influencing Premiums in 60031
Auto insurance rates in Gurnee are influenced by several localized factors that insurance carriers evaluate when assessing risk.
Traffic Density and Commuter Patterns The 60031 ZIP code is uniquely impacted by its proximity to major transit corridors, including I-94 and various state routes that facilitate heavy commuting toward Chicago and Milwaukee. High traffic volume naturally correlates with a higher statistical probability of minor fender-benders and congestion-related incidents. Insurance companies utilize granular actuarial data to adjust premiums based on these localized accident frequencies.
Environmental Risks Lake County experiences significant seasonal variance. Harsh winters in Northern Illinois present a constant risk for ice-related incidents, snow accumulation, and reduced visibility. Insurance carriers factor these regional climate risks into their comprehensive coverage pricing. Because comprehensive insurance covers non-collision damage—such as glass breakage from road debris, fire, theft, or weather-related incidents—the frequency of winter-related road claims in Illinois can exert upward pressure on premiums for comprehensive policies.
Essential Coverage Types
Beyond the state-mandated liability, Gurnee drivers should understand the full suite of available coverage types to determine their necessary level of protection.
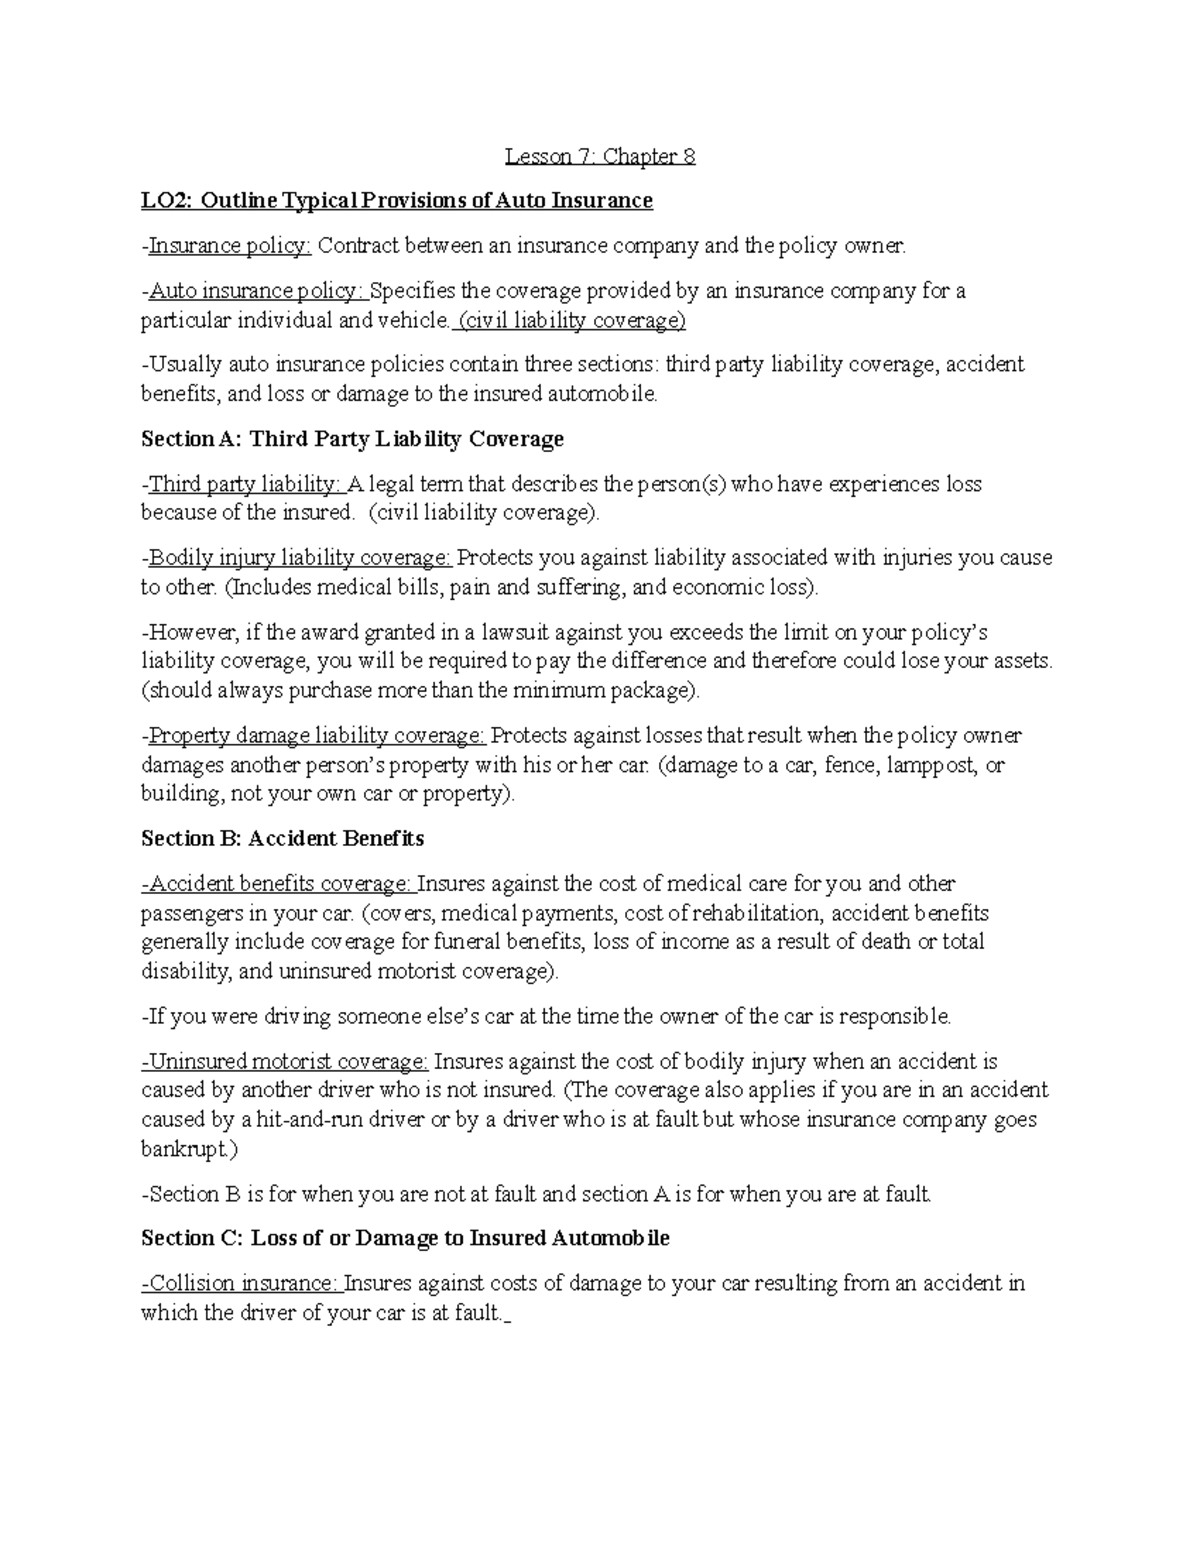
| Coverage Type | Description | Necessity Level |
|---|---|---|
| Bodily Injury Liability | Covers medical costs for others if you are at fault. | Mandatory/High |
| Property Damage Liability | Covers repair/replacement of others' property. | Mandatory/High |
| Uninsured/Underinsured Motorist | Protects you if the at-fault driver has no or low insurance. | Highly Recommended |
| Collision | Covers your vehicle repairs regardless of fault. | Recommended for newer cars |
| Comprehensive | Covers theft, fire, and weather damage. | Recommended for newer cars |
| Medical Payments (MedPay) | Covers medical bills for you and passengers. | Optional |
Uninsured Motorist (UM) coverage is particularly important in Illinois. Even with mandatory insurance laws, a significant portion of drivers operate vehicles without active policies. UM coverage ensures that you are not left paying out-of-pocket for medical expenses or vehicle repairs if you are struck by an uninsured driver.
Steps to Managing Your Auto Insurance
To effectively manage your policy, you should adopt a proactive approach to verification and renewal.
- Verify Financial Responsibility: Always keep proof of insurance in your vehicle. Illinois law requires that you present this documentation upon request by law enforcement. Failure to provide proof of insurance can lead to fines, suspension of your driving privileges, and registration revocation.
- Annual Reviews: In 2026, insurance markets are dynamic. It is advisable to review your policy every 12 months or following major life changes, such as moving to a new address, marriage, or purchasing a new vehicle.
- Credit-Based Insurance Scoring: Illinois allows insurance companies to use credit information as a factor in determining premiums. Maintaining a healthy credit profile can often lead to more competitive rates from major carriers operating in the 60031 region.
- Discount Opportunities: Inquire about specific discounts. Most carriers offer reduced rates for multi-policy bundling (e.g., combining auto with homeowners or renters insurance), safe driving programs, or vehicles equipped with advanced safety features and anti-theft technology.
Common Pitfalls and Troubleshooting
Drivers often make the mistake of prioritizing the lowest premium without reading the declarations page. A policy that appears cheap may have high deductibles or limited coverage that leaves the policyholder financially exposed in a total-loss scenario.
If you encounter issues such as a denied claim or an unexpected premium spike, your first point of contact should be your insurance agent or the company's customer service department. If a resolution cannot be reached internally, you may contact the Illinois Department of Insurance. They provide resources for consumers to file complaints regarding unfair claim denials or deceptive marketing practices.
Frequently Asked Questions
Is the minimum liability coverage in Illinois enough for a typical driver? In most cases, no. While the 25/50/20 limits satisfy state law, they are often insufficient. If you are at fault in an accident involving a luxury vehicle or multiple injuries, the costs will quickly exceed those minimums, leaving you personally liable for the remaining balance.
How does my vehicle choice affect insurance in Gurnee? Vehicles with high safety ratings and lower repair costs generally attract lower premiums. Conversely, high-performance vehicles or those with expensive, proprietary parts (like certain luxury imports) often cost more to insure because the cost to repair or replace the vehicle is significantly higher for the insurer.
Does my location in 60031 change my rates compared to neighboring ZIPs? Yes. Insurance companies divide regions into "rating territories." Differences in crime rates, local traffic congestion, and historical claim data in neighboring areas can result in varying premiums for the same level of coverage.
What happens if I let my insurance lapse? Illinois monitors insurance status through an electronic verification system. If your insurance lapses, the state may notify you to provide proof of coverage. If you cannot do so, your vehicle registration will likely be suspended, and you will be required to pay a reinstatement fee and provide proof of continuous insurance to resolve the matter.
Should I choose a higher deductible to lower my monthly premium? Increasing your deductible—the amount you pay out-of-pocket before insurance covers the rest—can lower your monthly premium. However, you should only select a high deductible if you have sufficient emergency savings to cover that amount in the event of an accident.
Are there specific discounts for commuters in Northern Illinois? Many insurers offer "telematics" programs that track driving habits via a mobile app or plugin device. If you are a safe driver who avoids erratic braking or late-night driving, these programs can often result in significant discounts on your annual premiums.
Final Recommendation
The best way to secure your financial position regarding auto insurance in 60031 is to prioritize higher liability limits over a low monthly premium. Evaluate your assets annually, ensure your policy includes robust Uninsured Motorist coverage, and utilize independent comparison tools to ensure your current carrier is still providing the best value for your specific vehicle profile. If you have questions about your specific policy, consult your declarations page or reach out to your licensed insurance producer to perform a coverage gap analysis.

Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
