To claim benefits from a Prudential annuity or life insurance policy associated with the defunct W.T. Grant Co., you must verify your status as a vested former employee or a designated beneficiary. Because the company liquidated in 1976, these benefits are now managed through Prudential’s legacy group insurance division or the Pension Benefit Guaranty Corporation (PBGC).
The W.T. Grant Company, once a titan of the American "five-and-dime" retail landscape, left behind a complex web of financial obligations following its historic bankruptcy in the mid-1970s. For former employees and their heirs, the search for "lost" retirement benefits often leads to Prudential, the primary insurer for the company's group benefit plans. As of 2026, these records are a half-century old, yet the legal obligation to pay out vested annuities remains. Understanding the intersection between W.T. Grant’s liquidation, the Pension Benefit Guaranty Corporation (PBGC), and Prudential’s ongoing administration is essential for successfully recovering these funds.
The Historical Context of W.T. Grant and Prudential
The W.T. Grant Company was one of the largest retailers in the United States until its collapse. In 1975, the company filed for Chapter 11 bankruptcy, which eventually transitioned into a total liquidation in 1976. At the time, it was the second-largest bankruptcy in U.S. history. This event was a watershed moment for pension law, as it occurred shortly after the 1974 passage of the Employee Retirement Income Security Act (ERISA).
Prudential Life Insurance Company of America served as the primary carrier for W.T. Grant’s group life insurance and retirement annuity programs. When the company ceased operations, the pension plan faced significant funding challenges. To protect employees, the plan was handled in two primary ways:
- Annuity Purchases: For many employees who were already retired or were nearing retirement with fully vested benefits, the W.T. Grant pension trust purchased individual or group annuity certificates from Prudential. These were "carve-outs" that removed the liability from the company’s books and placed the responsibility for payment directly on Prudential.
- PBGC Assumption: For portions of the plan that were underfunded or for employees whose benefits had not been fully converted to private annuities at the time of the final liquidation, the PBGC stepped in as the "insurer of last resort."
Distinguishing between a benefit held by Prudential and one held by the PBGC is the first hurdle in the recovery process.
Understanding Group Annuities vs. Life Insurance Policies
In the context of W.T. Grant Co., the term "life insurance annuities" can be confusing. Usually, these refer to one of two distinct financial products:
Group Pension Annuities
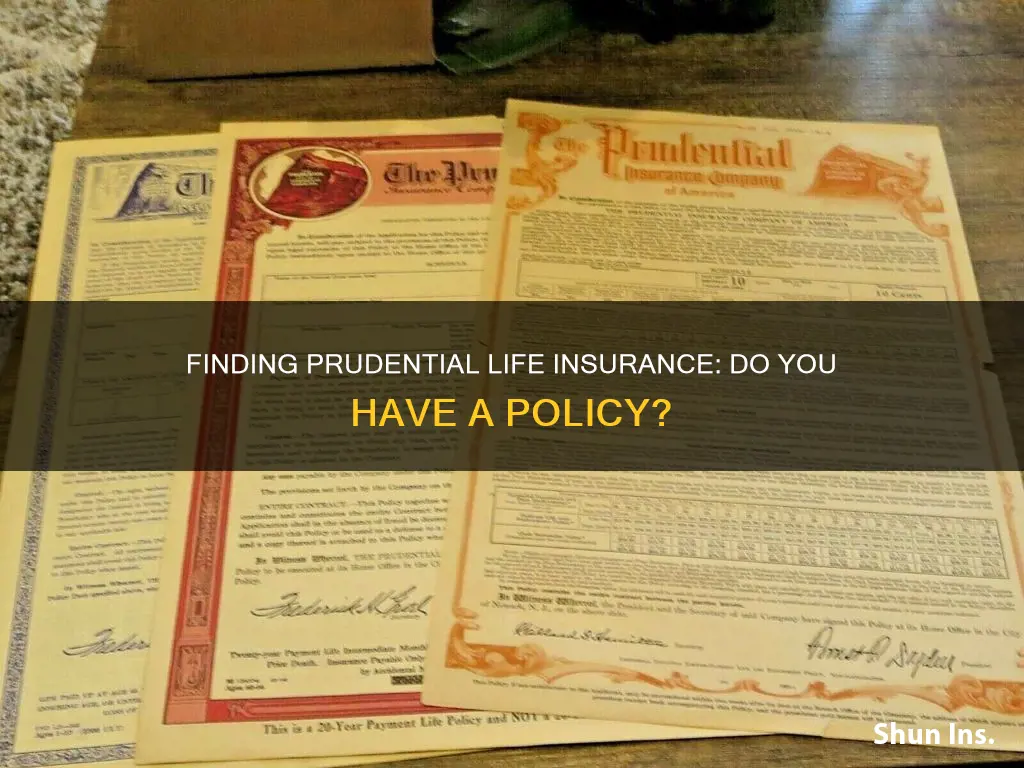
These are payments intended to provide retirement income. If you worked for W.T. Grant for a significant period (typically ten years or more, depending on the vesting rules of the era), the company likely contributed to a defined benefit pension plan. Upon the company's dissolution, these benefits were often converted into a "Group Annuity." You would have received a certificate from Prudential indicating your monthly benefit amount or a lump-sum value payable at age 65.
Life Insurance with Cash Value
Some management-level employees at W.T. Grant were eligible for life insurance policies that carried an investment component or "cash value." While most group term life insurance ends when employment terminates, certain executive plans or "paid-up" life insurance policies may have survived the bankruptcy. These are less common for general floor staff but are worth investigating for those in corporate or managerial roles.
How to Verify Eligibility for a W.T. Grant Annuity in 2026
Verification requires a "paper trail" that connects the individual to the defunct retailer. Given that W.T. Grant has not existed for decades, you cannot contact the employer. Instead, you must rely on third-party verification.
Necessary Information for Search
To begin a search with Prudential or the PBGC, you must have the following data points ready:
- Full Legal Name: Including any maiden names used during the years of employment.
- Social Security Number: This is the primary key used by Prudential to locate legacy group records.
- Dates of Employment: Approximate start and end years at W.T. Grant.
- Store Number or Location: W.T. Grant operated hundreds of stores; knowing the specific location can help narrow down regional payroll records.
- Annuity Certificate Number: If you have the original paper certificate issued by Prudential in the 1970s, the process is significantly faster.
The Role of the PBGC
If Prudential claims they have no record of the annuity, the next step is the PBGC. The W.T. Grant Company Pension Plan (Plan #00125700) is a "trusteed plan" under the PBGC. This means the federal government took over the administration of the plan because the company could no longer support it. The PBGC maintains a database for "unclaimed pensions" specifically for defunct companies like Grant's.
Navigating the Claims Process with Prudential
Prudential’s retirement and group insurance landscape has changed significantly over the years. In 2022, Prudential sold its full-service retirement record-keeping business to Empower. However, many "legacy" group annuity contracts—where Prudential is the actual insurer guaranteeing the payment—remained with Prudential’s Group Insurance or Institutional Annuities divisions.
Steps to Initiate a Claim:
- Contact Prudential Group Insurance: Specifically ask for the "Group Annuity" or "Pension Takeover" department.
- Request a Search: Provide the Social Security number of the former employee. If the individual is deceased, you will need to provide a death certificate and proof that you are the legal beneficiary or executor of the estate.
- Submit Documentation: If a record is found, Prudential will send a claim kit. This typically includes a tax withholding form (W-4P) and an election form choosing between a monthly payment or, in some cases of small balances, a lump-sum payout.
- Verification of Vesting: Prudential will verify if the employee met the "vesting" requirements at the time of the 1976 bankruptcy. If the employee left the company before becoming vested (usually before 10 years of service), no benefit will be payable, even if deductions were seen on old pay stubs.
Documentation and Evidence Checklist
Because these records are incredibly old, many are held on microfiche or in deep-storage archives. Providing any physical evidence from the 1970s can prevent a claim from being summarily denied due to "no record found."
| Document Type | Importance | Source |
|---|---|---|
| Prudential Certificate | High | Original mailings sent to employees in 1976-1977. |
| W.T. Grant Pay Stubs | Medium | Personal archives; shows pension deductions. |
| Social Security Statement | High | SSA.gov; provides proof of years worked at Grant's. |
| W-2 Forms (Historical) | High | Shows "Pension Plan" box checked. |
| Death Certificate | Essential | Necessary for beneficiary/heir claims. |
| Marriage Certificate | Essential | Necessary to prove name changes or spousal rights. |
Common Challenges and Troubleshooting
"No Record Found"
This is the most common response. It often happens because the record was moved to the PBGC or because the employee was not "vested." In 1976, vesting rules were much stricter than they are today. Many employees worked for 5 or 8 years and lost all rights to their pension when the company folded because they hadn't reached the 10-year threshold.
The Empower Transition
As mentioned, Prudential's 2022 sale to Empower moved many retirement accounts. If Prudential has no record, contact Empower's legacy service desk. They may have the "record-keeping" data even if Prudential holds the "insurance" risk.
Deceased Participants
If you are searching for a parent’s or spouse’s annuity, you must establish "Succession of Ownership." Most W.T. Grant annuities were set up as "Life Only" or "Joint and Survivor." If it was "Life Only" and the participant passed away, the annuity typically terminates, and no further payments are due to heirs. However, if there was a "Period Certain" (e.g., 10 or 20 years) or a "Life Insurance" component, there may be a residual death benefit.
Legal and Regulatory Protections
The recovery of these benefits is governed by ERISA. This federal law mandates that once a benefit is vested, it cannot be taken away due to bankruptcy or company closure.
If you believe Prudential is wrongfully denying a claim, you have several avenues:
- State Department of Insurance: File a "Missing Policy" search request with the insurance department in the state where the W.T. Grant store was located or where the employee resided.
- NAIC Life Insurance Policy Locator: The National Association of Insurance Commissioners (NAIC) provides a free tool that asks insurers to search their records for a specific Social Security number.
- Pension Rights Center: This non-profit organization provides legal assistance to individuals trying to track down lost pensions from defunct companies.
Tax Implications of Legacy Annuities
When a W.T. Grant annuity is finally located in 2026, the payout often includes decades of accrued value or a series of back-payments if the individual passed the "normal retirement age" (usually 65) years ago.
- Lump Sums: Receiving a large lump sum for a 50-year-old annuity can create a significant tax liability in the year of receipt. These are typically treated as ordinary income.
- Interest: In some cases, if the delay in payment was due to an insurer's error, interest may be added. This interest is also taxable.
- Inherited Annuities: If you receive the funds as a beneficiary, the "Income in Respect of a Decedent" (IRD) rules apply. You will likely owe income tax on the distributions, as the original contributions by W.T. Grant were made pre-tax.
Frequently Asked Questions
What happened to the W.T. Grant pension plan after 1976?
The plan was partially funded. Fully vested benefits for those near retirement were often used to purchase group annuities from Prudential. The remaining underfunded liabilities were taken over by the Pension Benefit Guaranty Corporation (PBGC).
How can I find out if I am a beneficiary of a W.T. Grant policy?
You must contact Prudential’s legacy group insurance department or use the PBGC's "Unclaimed Pension" search tool. You will need the Social Security number of the deceased employee to perform a search.
Does Prudential still hold the money for W.T. Grant employees?
Only for those whose benefits were specifically converted into Prudential annuity contracts. If the benefit stayed within the general pension trust, it moved to the PBGC. If it was a 401(k)-style plan (which were rare in 1976), the funds might have been distributed during the liquidation.
Is there a time limit (statute of limitations) on claiming these annuities?
Generally, no. Under ERISA, vested pension benefits do not expire. However, the longer you wait, the harder it becomes to locate the historical records needed to prove your claim. If a policy is considered "abandoned," the funds may eventually be turned over to state unclaimed property divisions (escheatment).
Can I claim my W.T. Grant annuity if I don't have the original paperwork?
Yes, but it is more difficult. Prudential and the PBGC can search by Social Security number. However, if their digital records are incomplete, having a physical pay stub or a 1970s-era benefit statement is often the only way to "force" a deeper manual search of the archives.
Final Recommendation for Claimants
If you are searching for a Prudential annuity related to W.T. Grant Co. in 2026, start by performing a dual search. First, use the PBGC Trusteed Plan Search for "W.T. Grant" to see if your name or your relative's name appears in their database of unclaimed pensions. Second, contact Prudential’s Institutional Annuity Service Center at 1-800-621-1089 (or their current 2026 equivalent) to request a "Group Annuity Search" using the participant's Social Security number. If both entities deny having the record, check the Unclaimed Property website for the state where the employee last worked, as the funds may have been escheated if Prudential lost contact with the policyholder.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
