How Working Life Insurance Works: Mechanics, Coverage, and Policies Explained
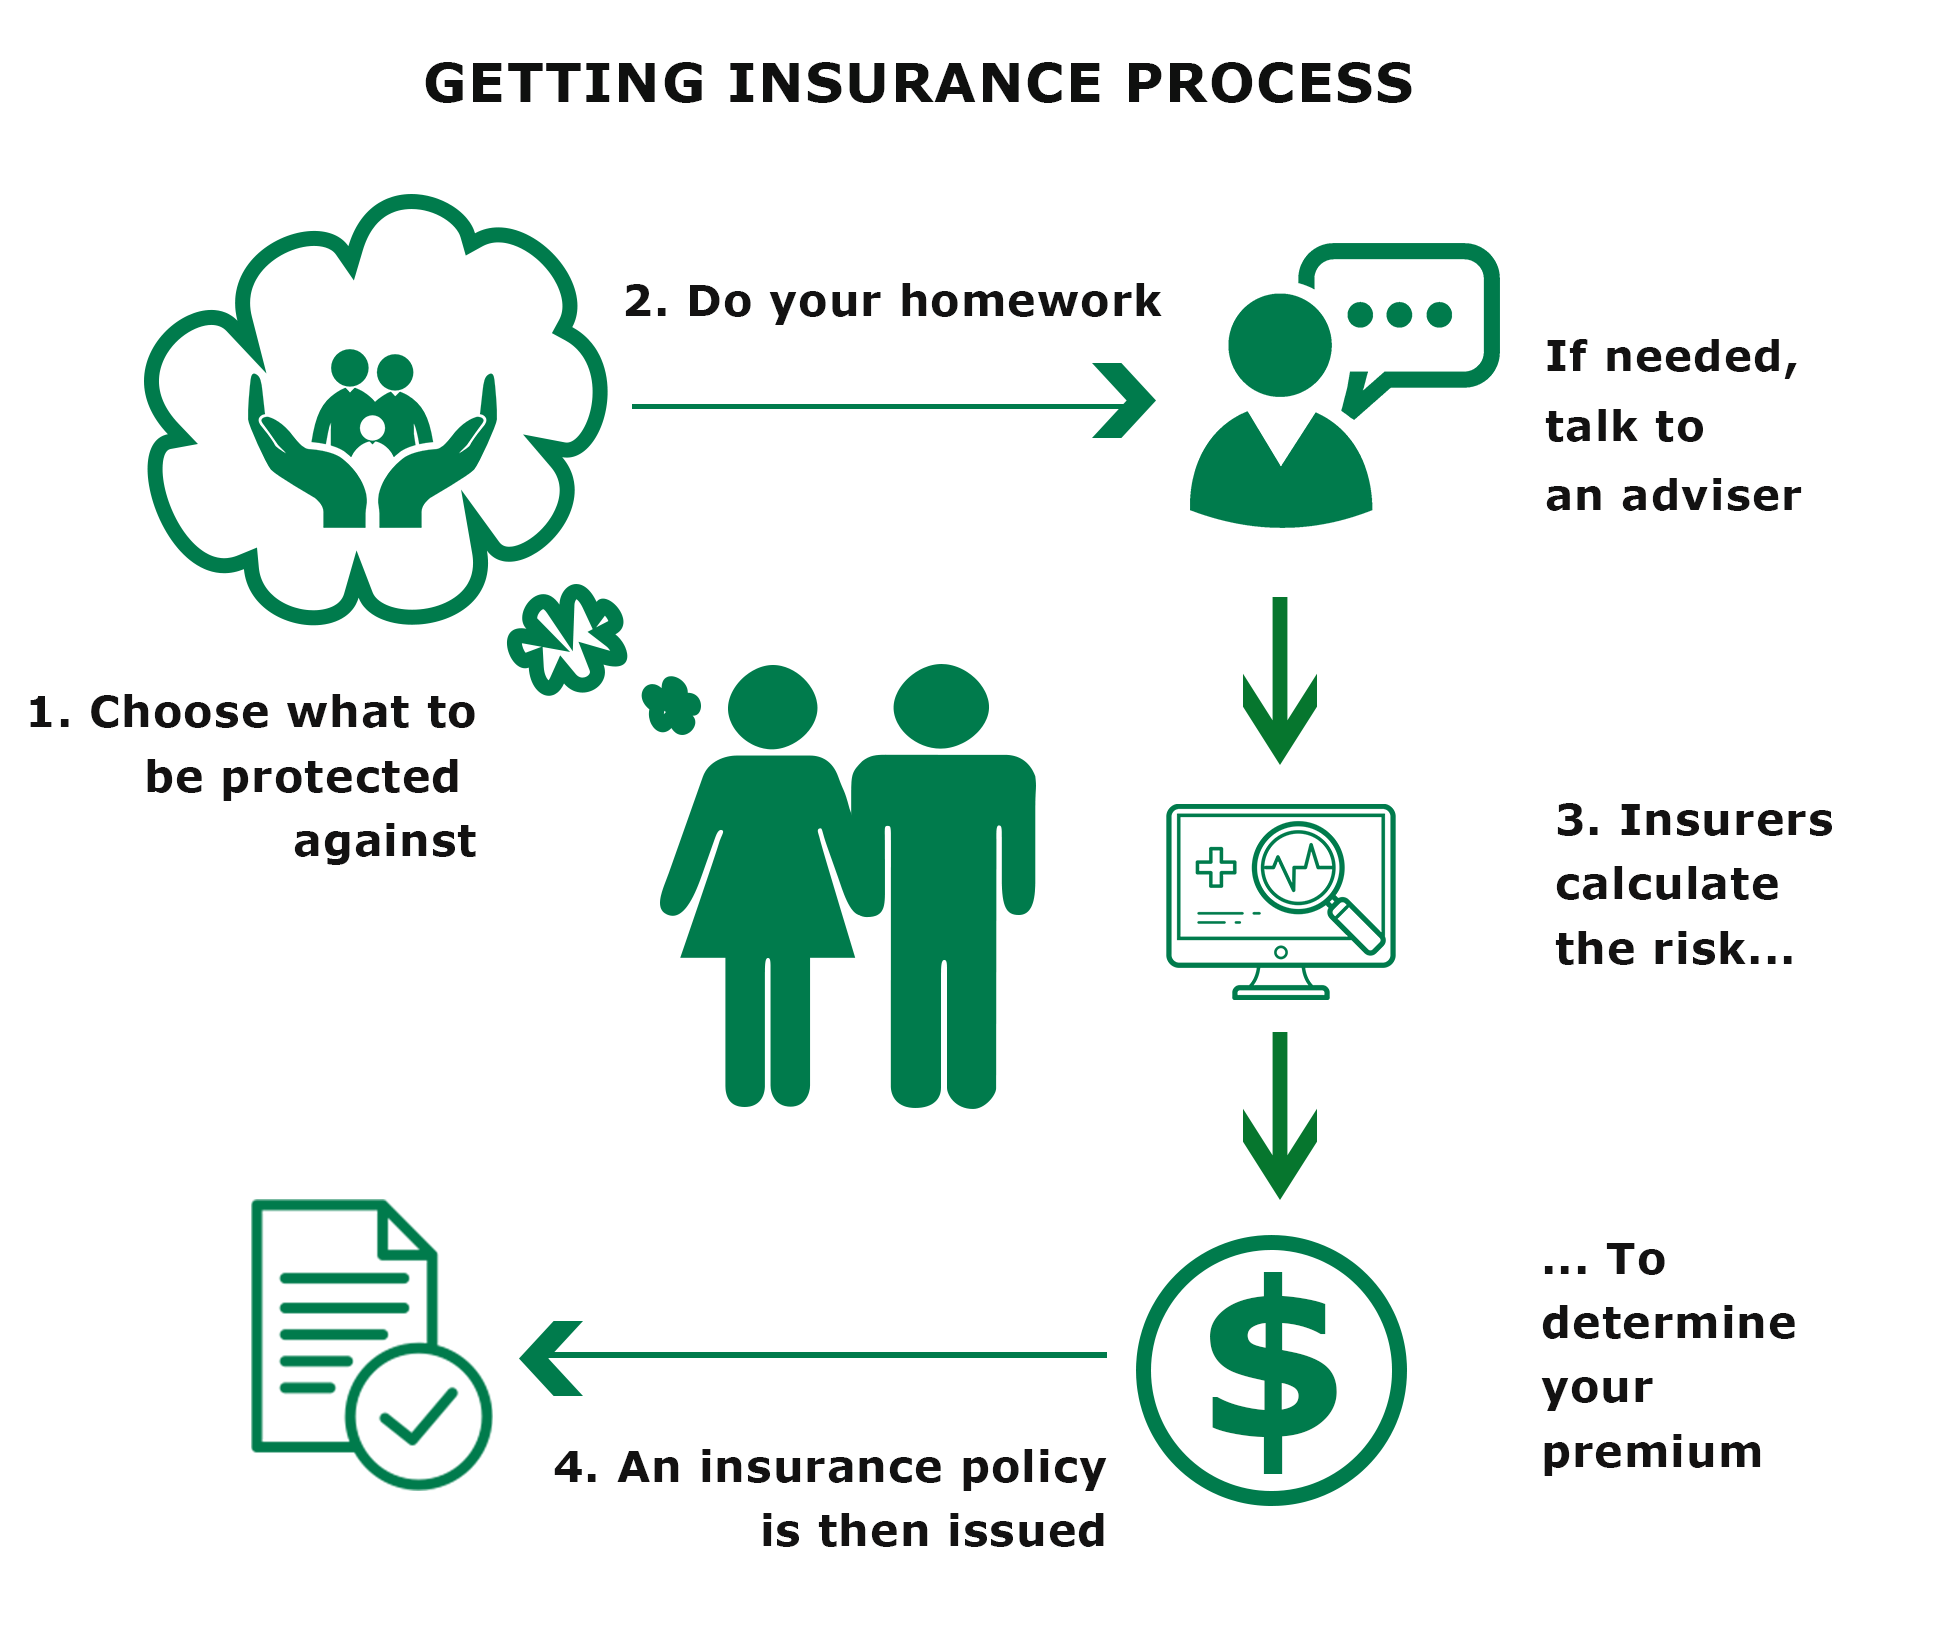
Working life insurance functions as a specialized form of coverage designed to provide financial protection during an individual's active employment years, bridging the gap between standard group benefits and complex individual permanent policies. Understanding how this product operates requires examining its underwriting criteria, premium structures, payout mechanisms, and how it interacts with workplace dynamics.
Understanding the Fundamentals of Working Life Insurance
At its core, working life insurance is designed to offer financial security to working professionals and labor force participants while they are actively earning an income. Unlike traditional whole life policies that remain active regardless of employment, or standard term policies that can sometimes carry rigid health screening requirements, working life insurance often ties its availability or preferential terms to active employment status or specific working age brackets.
The primary purpose of this coverage is income replacement and debt neutralization. When a policyholder passes away during their working years, surviving dependents face immediate financial shocks, including the loss of primary income, outstanding mortgage balances, vehicle loans, and future child-rearing or educational expenses. Working life insurance steps in to provide a lump-sum tax-free benefit—known as the death benefit—to designated beneficiaries. This capital injection ensures that the household can maintain its standard of living, settle liabilities, and fund long-term financial goals without the destabilizing pressure of sudden income cessation.
Navigating this niche requires distinguishing between employer-sponsored group variants and standalone policies marketed specifically to working-age adults. While group policies provided through an employer are convenient, they are rarely portable and often provide limited coverage multiples. Understanding the mechanical differences between these options helps consumers avoid coverage gaps during job transitions.
Types of Working Life Insurance Coverage
Working life insurance is not a single, monolithic product; rather, it encompasses several structural configurations tailored to the needs of active earners. Choosing the right structure depends on employment stability, budget constraints, and long-term financial objectives.
Group Working Life Insurance
Frequently offered as an employee benefit, group life insurance covers a collection of individuals under a single master contract.
- Mechanics: Employers usually pay all or part of the premium. Underwriting is often guaranteed issue or simplified issue up to a certain threshold, meaning employees do not need to undergo rigorous medical exams.
- Limitations: Coverage amounts are typically capped at a multiple of annual salary (e.g., 1x to 3x salary). Crucially, the policy is tied to employment; leaving the company usually terminates the coverage, though some plans offer a conversion option to an individual policy at significantly higher rates.
Individual Term Working Life Insurance
For workers seeking higher coverage limits independent of their employer, individual term policies provide a robust alternative.
- Mechanics: The policyholder purchases a policy directly from an insurer for a specific duration (e.g., 10, 20, or 30 years) that coincides with their working and earning years.
- Underwriting: Requires full medical underwriting, including health questionnaires and sometimes physical exams. However, this process secures locked-in, level premiums that remain affordable for healthy applicants.
Simplified Issue and Guaranteed Acceptance Policies
Designed for workers who may have pre-existing health conditions or who wish to bypass medical exams entirely.
- Mechanics: Approval is granted based on answers to a few health questions or granted automatically regardless of health status.
- Trade-offs: These policies generally feature lower maximum face values, higher premium costs per dollar of coverage, and a graded death benefit period where full payouts apply only after the policy has been active for a specified duration (such as two years).

Underwriting, Eligibility, and Application Processes
Securing a working life insurance policy involves a structured evaluation process by the insurance carrier's underwriting department. This process determines the applicant's risk profile and calculates the appropriate premium rate.
- Needs Analysis
- Determine required coverage amount
- Application Submission
- Complete health & lifestyle forms
- Underwriting Evaluation
- Medical records, exams, & databases
- Offer & Policy Issuance
- Review rates, sign, and pay premium
The application journey begins with a needs analysis, where the applicant calculates their financial obligations, outstanding debts, and the number of years remaining until retirement. Once an insurer is selected, the applicant completes a detailed application detailing their age, occupation, medical history, family medical history, driving record, and lifestyle habits such as tobacco use or extreme sports participation.
For fully underwritten policies, the insurer may require a paramedical exam, which includes drawing blood and taking urine samples, blood pressure measurements, and height-and-weight checks. The underwriter then reviews attending physician statements (APS) and checks database clearinghouses like the Medical Information Bureau (MIB) to verify health disclosures.
Once underwriting is complete, the applicant receives a formal offer. Premiums are determined by these findings: healthier applicants and younger workers secure lower rates (preferred or standard classes), while older applicants or those with managed chronic conditions face higher rates (table ratings).
Comparing Policy Structures: Group vs. Individual
Evaluating the structural differences between workplace group coverage and private individual policies is essential for comprehensive financial planning.
| Feature | Group Working Life Insurance | Individual Working Life Insurance |
|---|---|---|
| Source | Provided via employer or labor union | Purchased independently from a broker or carrier |
| Underwriting | None or minimal (Guaranteed Issue) | Full medical underwriting required |
| Portability | Generally non-portable (ends upon job separation) | Fully portable (remains active regardless of employment) |
| Cost | Often subsidized or low-cost for basic tiers | Fixed rates based on age and health at time of purchase |
| Coverage Limits | Restricted (often 1x–2x annual salary) | Customizable (hundreds of thousands to millions) |
This comparison highlights why relying solely on workplace group insurance can be risky. While group coverage serves as an excellent foundational layer of protection, individual policies provide the customization and permanence required to safeguard a family against long-term income disruption.
Premium Costs and Financial Considerations
The cost of working life insurance varies widely depending on several foundational variables. Understanding these cost drivers helps policyholders optimize their coverage without overextending their monthly budgets.
- Age: Premium rates increase incrementally with each year of chronological age. Locking in a term policy early in one's working life secures substantially lower long-term rates than waiting until middle age.
- Health Status: Tobacco use, high blood pressure, elevated cholesterol, and a history of chronic illnesses significantly drive up premium costs. Conversely, maintaining a healthy Body Mass Index (BMI) and clean medical records yields favorable pricing tiers.
- Occupation and Avocations: Workers in high-risk environments—such as commercial fishing, construction, aviation, or explosives handling—may face occupational flat extras (surcharges) or exclusions. Similarly, engaging in hazardous hobbies like scuba diving, skydiving, or rock climbing impacts underwriting decisions.
- Coverage Amount and Duration: Higher death benefits and longer term lengths naturally command higher monthly or annual premiums.
Financial planners frequently recommend the "Income Multiple" rule of thumb—multiplying annual gross income by 10 to 15—as a starting point for determining coverage size, adjusted upward for outstanding debts and dependents' educational needs.
Common Misconceptions and Troubleshooting
Misunderstandings regarding how working life insurance operates can lead to devastating coverage gaps. Clarifying these misconceptions ensures policyholders maintain adequate protection.
- Myth: "My employer's policy is all I will ever need."
- Reality: Average employer-sponsored group life policies are often insufficient for a family with a mortgage and growing children. Furthermore, losing or changing jobs strips away the coverage instantly.
- Myth: "Term insurance pays out if I outlive the term."
- Reality: Standard term policies are pure protection vehicles without a cash value savings component. If the insured survives the term, the policy expires without payout unless it includes a specific return-of-premium rider.
- Myth: "I am young and healthy, so I can skip buying insurance now."
- Reality: Rates are tied directly to the age at application. Delaying purchase results in higher baseline pricing when policies are eventually secured.
When troubleshooting an existing policy—such as addressing missed premium payments, navigating a grace period, or updating beneficiary designations—policyholders should contact their insurance carrier's customer service department or licensed financial advisor immediately to prevent policy lapse.
Practical Next Steps for Securing Coverage
Evaluating and establishing working life insurance requires a methodical, step-by-step approach to ensure maximum financial protection and cost-efficiency.
- Audit Existing Benefits: Review current employer-sponsored group policies to determine exact death benefit limits, conversion privileges, and whether coverage is truly portable.
- Calculate Financial Liabilities: Sum up outstanding mortgages, car loans, credit card debt, future educational funds for dependents, and total annual income replacement needs over the target working timeline.
- Shop the Market: Obtain quotes from multiple reputable, financially stable insurance carriers. Working with an independent insurance broker can simplify comparing various product offerings and underwriting guidelines.
- Complete Health Assessments Accurately: Disclose all medical history honestly during the application process. Inaccurate disclosures can complicate claims processing or void coverage during the contestability period.
- Review Annually: Revisit coverage levels following major life events, such as marriage, the birth of a child, purchasing a home, or significant career changes.
By carefully assessing needs, understanding structural mechanics, and securing appropriate individual coverage alongside workplace benefits, working professionals can establish a resilient financial safety net for their families.
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
